
Home Insurance Claims Tips: Navigating Repairs And Reimbursements
Filing a home insurance claim can feel overwhelming, especially when you’re dealing with damage to your property. The process involves multiple steps, from documenting the damage to negotiating with adjusters, and getting it right makes a real difference in what you receive.
We at Evaristo Insurance have helped countless Connecticut homeowners navigate claims successfully. These home insurance claims tips will walk you through each stage so you know exactly what to do and what to expect.
Know Your Policy Before You File
Review Your Coverage Limits and Deductibles
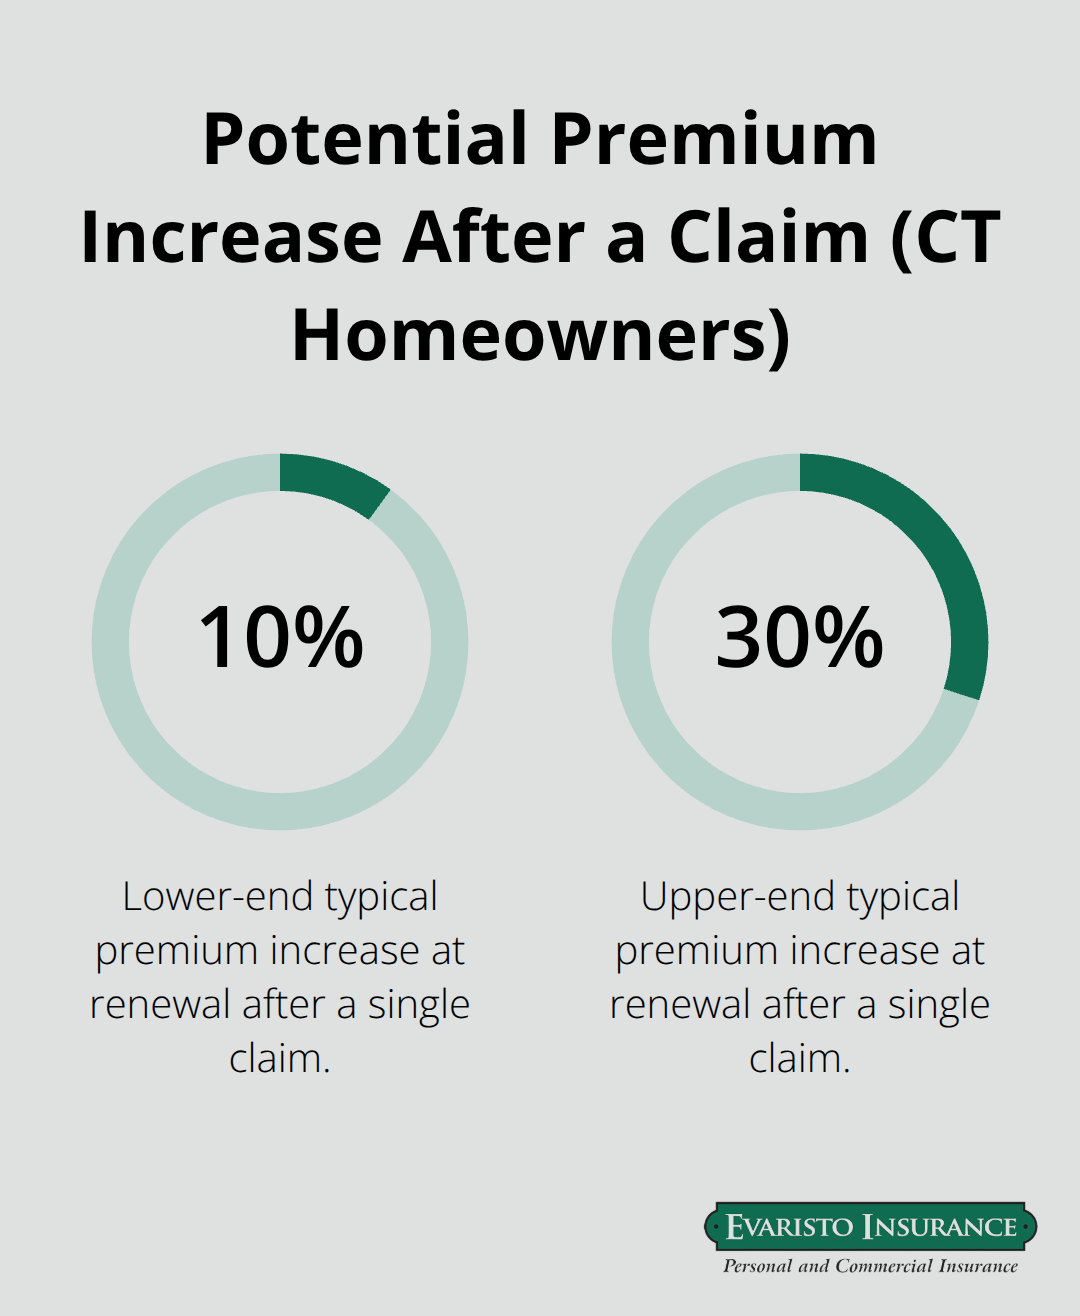
Most Connecticut homeowners never read their policies until damage happens, and that’s when they discover gaps or surprises. Standard homeowners policies cover fire, windstorms, lightning, theft, and vandalism, but they absolutely do not cover earthquakes or flooding-you need separate policies for those risks. Your deductible matters far more than most people realize. According to NerdWallet analysis, deductibles typically range from $500 to $2,000 depending on your policy limits. Here’s what matters: if your repair costs fall below your deductible, filing a claim doesn’t make financial sense. The Insurance Information Institute recommends filing only when repair costs reach two to three times your deductible. This matters because filing a claim can increase your premiums by 10% to 30% at renewal and you may lose discounts like claims-free credits.
Understand What Your Policy Excludes
Water damage represents a frequent claim cause, but coverage often excludes certain types of water damage, especially from negligence or long-term wear. Mold growth and moisture seeping through foundation walls trigger common denial reasons. Connecticut homeowners should understand whether your policy carries separate deductibles for specific perils like wind or hail. Pull out your actual policy documents right now and locate three specific things: your coverage limits for dwelling and personal property, your exact deductible amount, and any exclusions that apply to water damage or mold.
Know Your Additional Coverage Options
Your policy also tracks what’s covered under loss of use or additional living expenses coverage, which reimburses hotels, meals, and other day-to-day costs while your home remains uninhabitable. This coverage has its own limits, so know those numbers before disaster strikes. If you have valuables like jewelry or art, verify whether they’re covered under standard limits or if you need a separate rider-standard policies often cap coverage for these items far below their actual value.
Keep Your Documents Accessible and Clarify Confusion
Store your policy documents in an accessible location, ideally both in print and digitally stored in the cloud. When you contact an insurer after damage, having your policy number and coverage details ready speeds up the entire process. If your policy language confuses you, don’t guess-ask your agent to clarify coverage specifics and set realistic expectations about what will and won’t be covered. An independent agency like Evaristo Insurance can review your existing coverage and help ensure it actually matches your home’s current value and your financial situation, because underinsurance remains surprisingly common among Connecticut homeowners.
Now that you understand what your policy covers, the next step involves acting quickly when damage actually occurs-and the first hours after an incident determine how smoothly your claim will proceed.
Act Fast When Damage Strikes
The hours immediately following property damage determine how smoothly your claim proceeds and whether you’ll receive full reimbursement. Most homeowners waste this critical window by hesitating, cleaning up debris, or waiting to contact their insurer. Don’t. Reporting your claim quickly is essential because many policies impose deadlines for filing, often within 30 days of the incident.
Document Everything Immediately
Start by assessing what happened and identifying which areas suffered damage, then grab your phone and camera before doing anything else. Take extensive photos and videos of all damaged areas from multiple angles, capturing both wide shots of affected rooms and close-ups of specific damage. Photograph your personal belongings too, especially items in less-obvious locations like closets, basements, or storage areas. This visual documentation becomes your strongest evidence during the claims process because adjusters rely heavily on what they can see and verify.
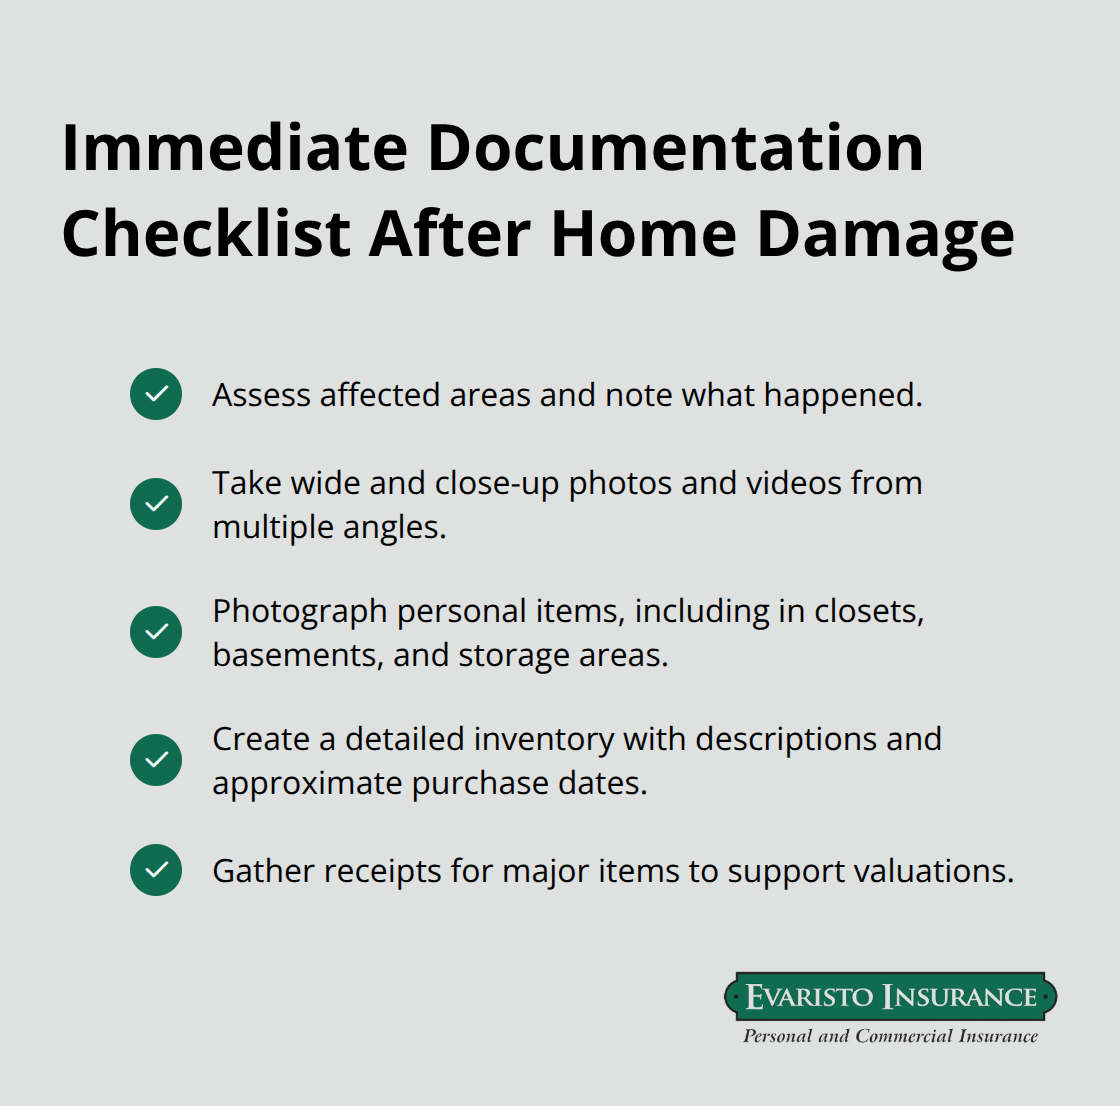
Create a detailed written inventory listing every damaged item, including descriptions, approximate purchase dates, and values if you have them. If you possess receipts for major items, gather those immediately. Thorough documentation speeds the entire process and prevents delays caused by missing information.
Contact Your Insurer Without Delay
Contact your insurance company without delay using whatever method works fastest. Most insurers maintain 24/7 claim hotlines, online portals, or mobile apps specifically designed for immediate reporting. Have your policy number ready along with basic details: your name, contact information, the date and type of loss, and a clear description of the damage. Your insurer will assign a claim number and an adjuster to your case, and this person becomes your primary contact throughout the process.
Prevent Further Damage and Preserve Evidence
While waiting for the adjuster to arrive, take reasonable temporary repairs to prevent further damage, such as placing tarps over roof holes or shutting off water after a leak. Save every receipt for these mitigation efforts because most policies reimburse these costs as part of your claim settlement. Do not enter a damaged home until emergency personnel or local government officials clear it for safety. Preserve damaged items when possible so the adjuster can inspect them as part of the assessment.
Handle Theft or Vandalism Claims
If theft or vandalism caused the damage, file a police report immediately and provide that report to your insurer as part of your documentation package. These steps transform you from a passive claimant into an organized, credible one, which adjusters recognize and respect. Your preparation now sets the stage for the next critical phase: working directly with the adjuster assigned to your case and ensuring you receive fair compensation for your losses.
How to Work with Your Adjuster for Fair Settlements
Your adjuster represents the bridge between your claim and your payout, so treating this relationship strategically matters far more than most homeowners realize. The adjuster’s job involves assessing damage and determining what your policy covers, but their assessment isn’t the final word on what you should accept. Connecticut homeowners who prepare thoroughly and ask the right questions consistently receive higher settlements than those who passively accept initial offers.
Organize Your Documentation Before the Inspection
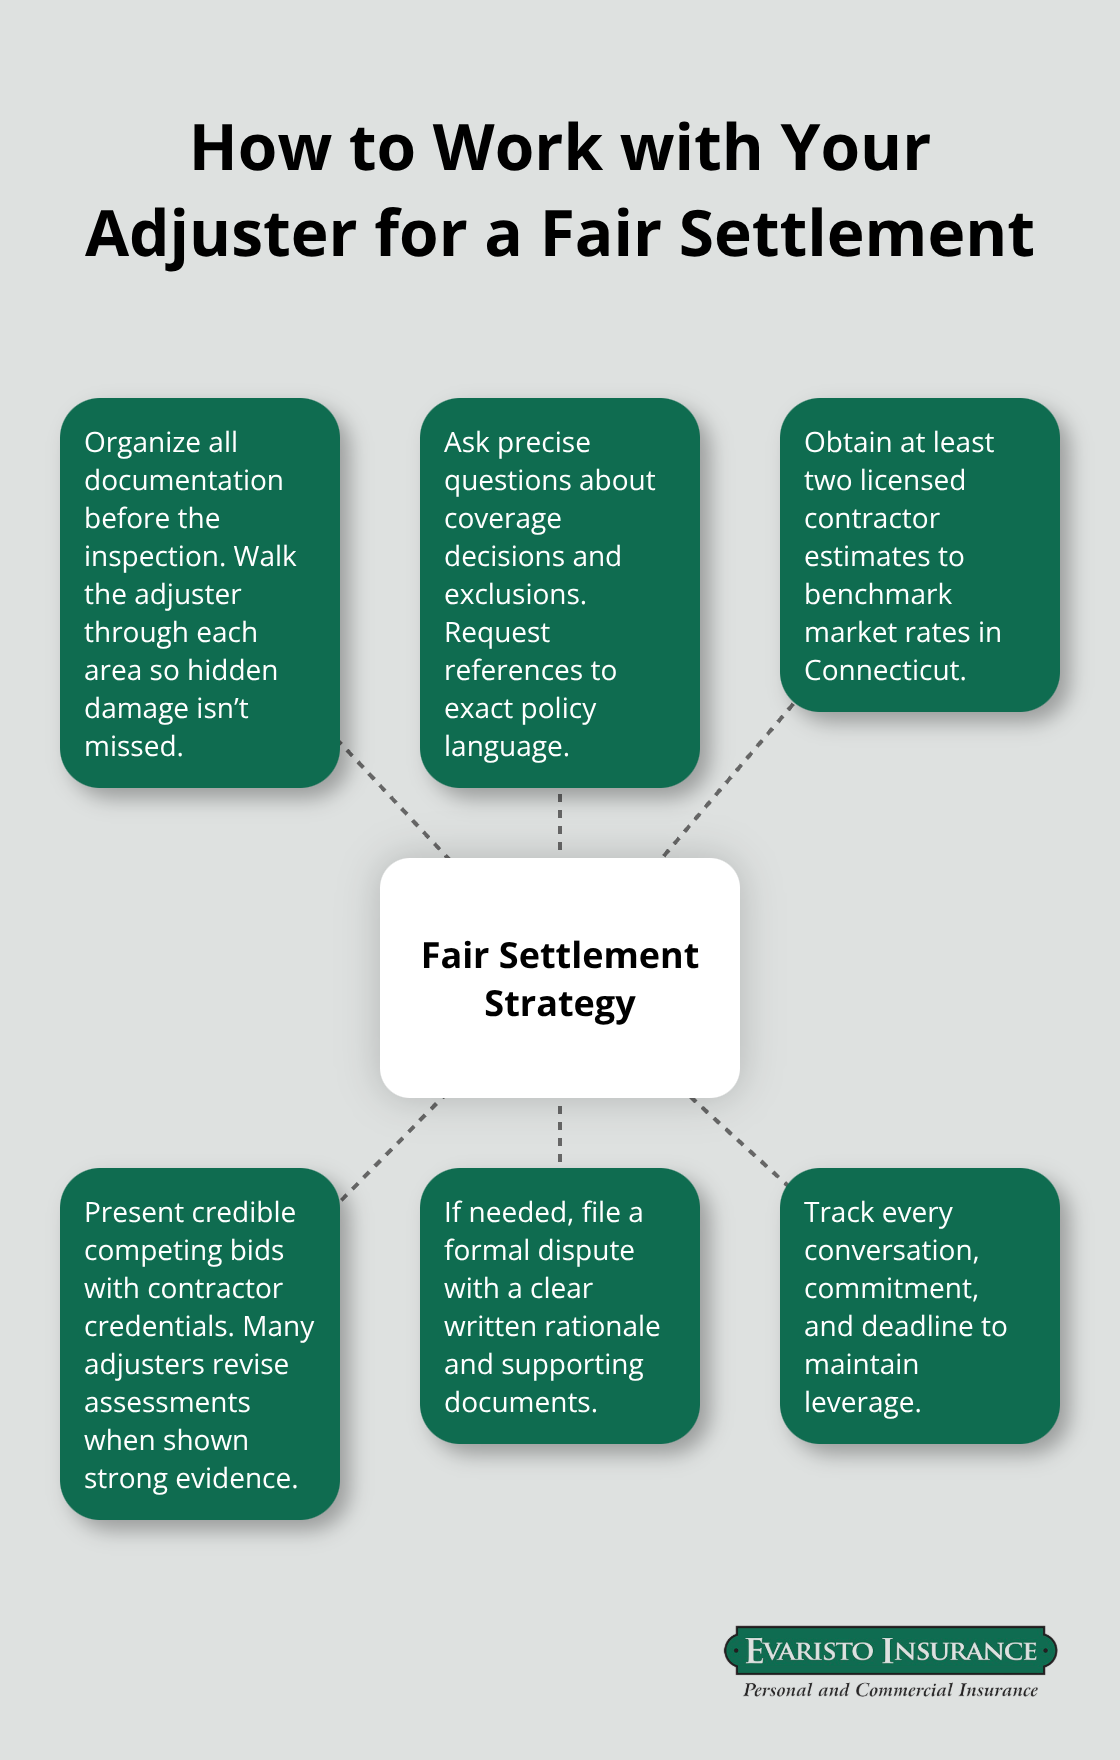
Start by organizing every piece of documentation you gathered immediately after the damage occurred. Create a single folder containing photos, videos, your itemized inventory with values, receipts for damaged items, and records of any temporary repairs you completed. When the adjuster arrives, be present and walk them through the damage yourself rather than leaving them to explore alone. Point out damage they might miss, especially in less-obvious areas like attic spaces, crawl spaces, or behind walls.
Ask Specific Questions About Coverage Decisions
The adjuster will explain what your policy covers and what it excludes, so ask specific questions about any coverage decisions you don’t understand. If they mention exclusions, ask them to show you exactly where those exclusions appear in your policy language. Don’t accept vague answers. Request clarification on any terms or coverage limits that seem unclear, and take notes during the conversation so you maintain an accurate record of what the adjuster told you.
Obtain Independent Repair Estimates
Once the adjuster provides their damage assessment and repair estimate, obtain independent repair estimates from licensed contractors before accepting their figures. Get at least two additional bids so you can compare costs and identify whether the adjuster’s estimate aligns with actual market rates in Connecticut. Your contractor’s bid must be reasonable as compared to market conditions for work that replaces your home with materials. Licensed contractors in your area can provide realistic pricing that reflects current labor and material costs.
Present Competing Estimates and Dispute if Necessary
If your independent estimates exceed the adjuster’s assessment significantly, present those estimates directly to your adjuster with documentation showing contractor licensing and experience. Many adjusters will adjust their initial assessment upward when presented with credible competing estimates. If the adjuster’s offer remains substantially lower than your independent estimates, you can formally dispute the settlement. Gather all your documentation, your contractor estimates, and a clear written explanation of why you believe the offer falls short, then submit this to your insurer’s claims department.
Your advocacy for fair compensation doesn’t end with the adjuster’s inspection.
Final Thoughts
Successfully navigating a home insurance claim requires preparation, documentation, and persistence. The home insurance claims tips we’ve shared throughout this guide all point to one fundamental truth: homeowners who act quickly, organize their evidence, and ask tough questions receive fair settlements. You now understand your policy’s coverage limits and exclusions before damage occurs, you know exactly what to do in the critical hours after an incident, and you understand how to work strategically with adjusters to secure appropriate reimbursement.
Connecticut homeowners often face unique challenges with wind and hail damage, water intrusion, and coverage gaps that leave them underinsured. Local expertise makes a real difference when you need it most. Evaristo Insurance can help you review your existing coverage, compare multiple top carriers, and find protection that actually matches your home’s value and your financial situation.
If your claim history has become complicated or you’ve experienced multiple losses, we can help you navigate markets that specialize in higher-risk situations and work with carriers willing to provide coverage when others won’t. Contact us to discuss your specific situation with agents who understand Connecticut’s insurance landscape and your home’s protection needs.
Disclaimer: This blog post is for general informational purposes only and does not represent actual coverage, policy terms, or legal requirements. Insurance details vary by individual and jurisdiction. Please consult a licensed insurance professional for advice specific to your situation.

