
Maximizing Protection With Business Owners Insurance Coverage
Running a business in Connecticut means facing real risks-from severe weather to employee claims to theft. Business owners insurance coverage protects against these threats, but only if you choose the right policy for your operation.
At Evaristo Insurance, we’ve helped countless Connecticut business owners find the protection they actually need. The sections below break down what’s covered, which risks matter most in our state, and how to select a policy that won’t leave gaps.
What Business Owners Insurance Actually Covers
Core Coverage in a Business Owners Policy
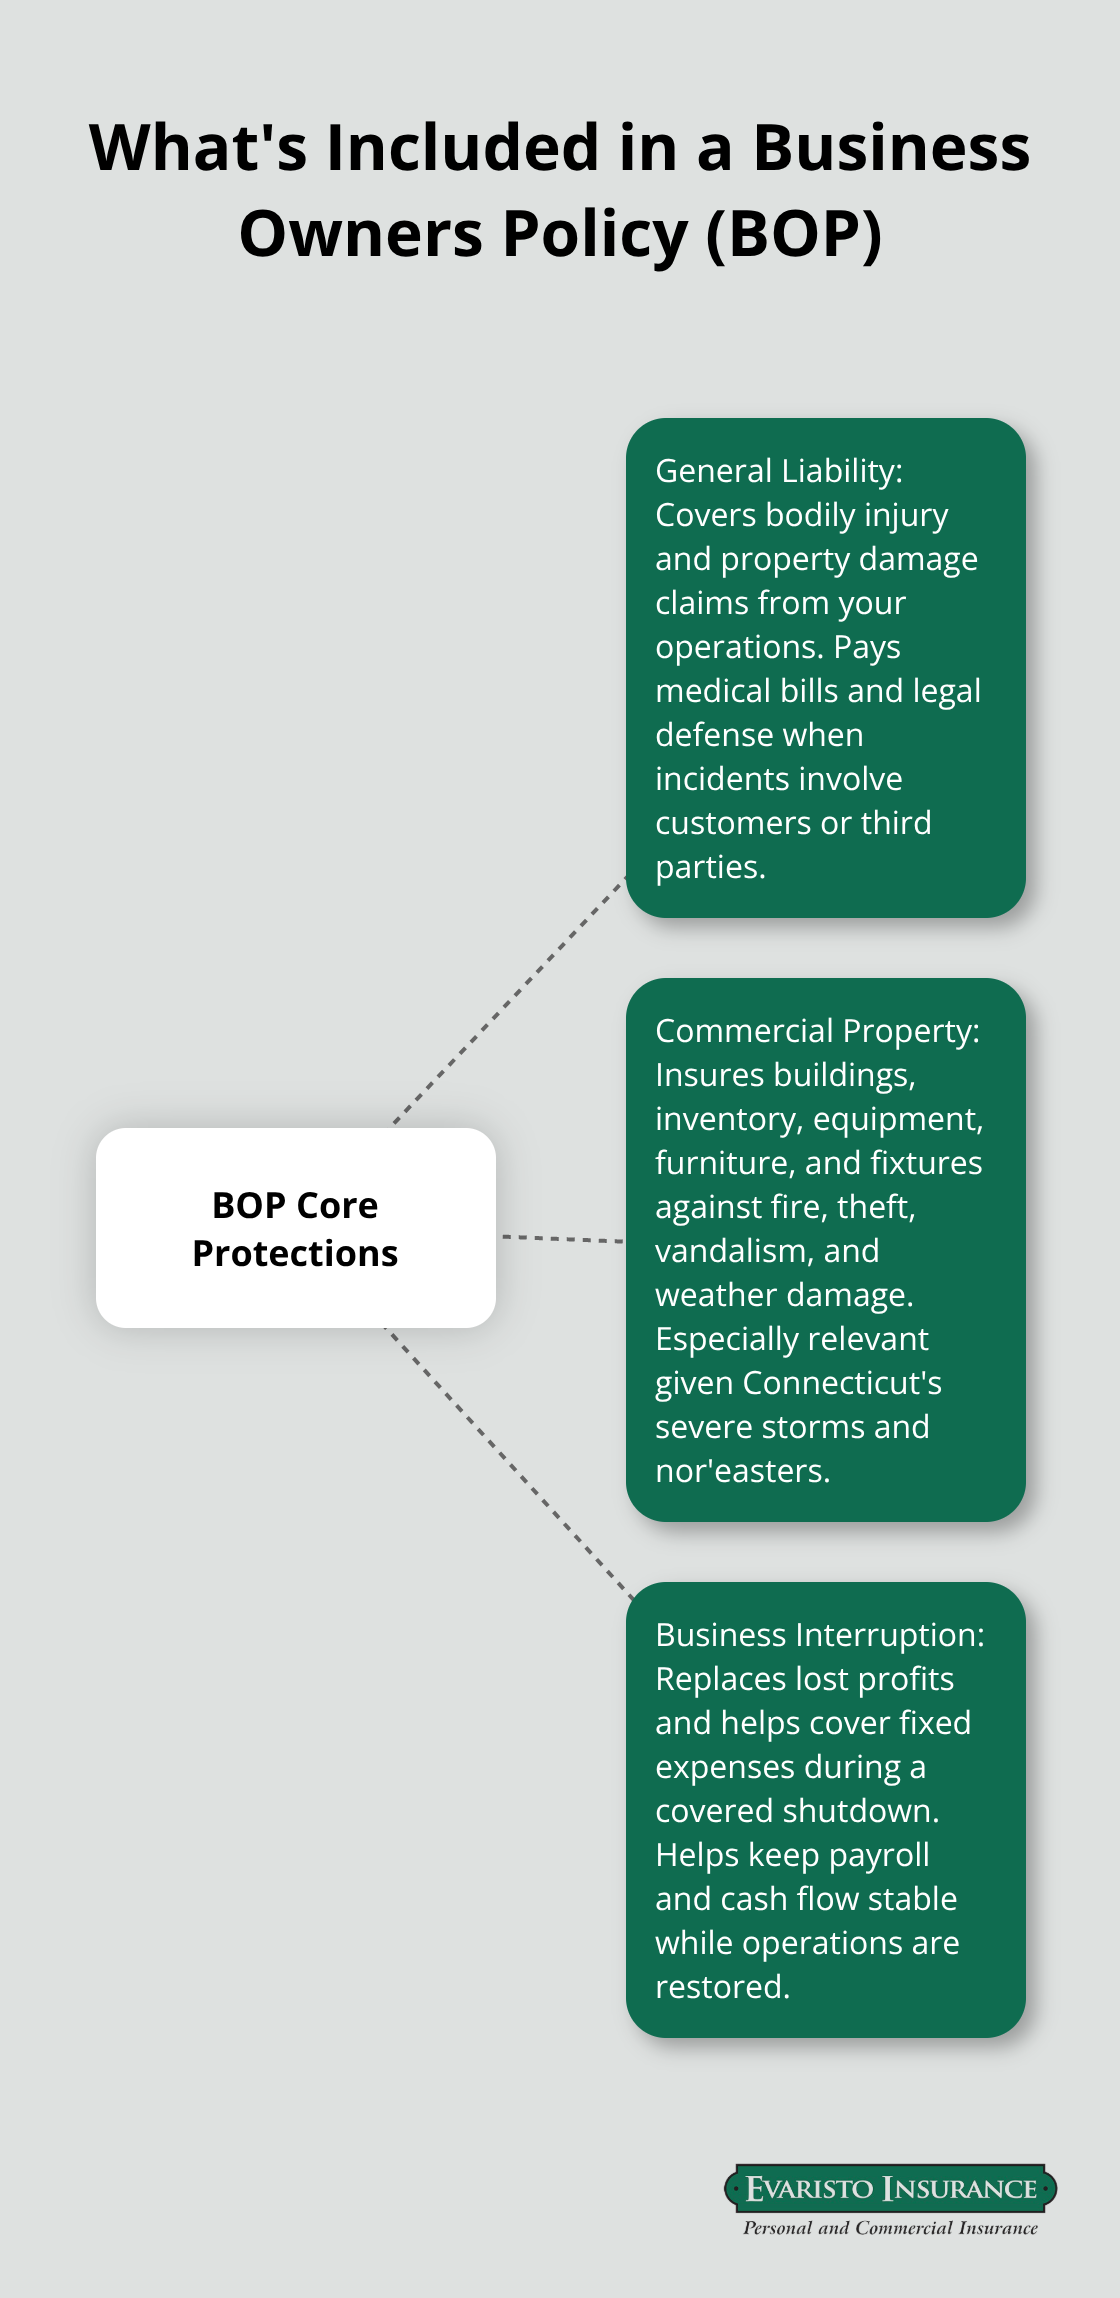
A Business Owners Policy, or BOP, combines three core protections into one policy: general liability, commercial property coverage, and business interruption. In Connecticut, this combination addresses the most common threats to small and mid-sized operations. General liability covers bodily injury and property damage claims that arise from your business activities-if a customer slips on your floor or your equipment damages their property, this pays their medical bills and legal defense costs. Commercial property protection covers your building, inventory, equipment, furniture, and fixtures against fire, theft, vandalism, and weather damage, which matters significantly in Connecticut given our exposure to severe storms and nor’easters. Business interruption coverage delivers real value that many owners overlook: if a covered event forces you to close temporarily, this coverage pays your lost profits, fixed costs, and additional expenses incurred during the downtime period, helping you stay afloat when operations halt.
Cost Efficiency Through Bundling
According to Insureon data, typical Connecticut small-business owners pay around $48 monthly for general liability and $78 monthly for workers’ compensation. A bundled BOP costs considerably less than purchasing policies separately, making it the most affordable path to comprehensive protection for most operations.
Specialized Add-Ons for Your Operation
Beyond the core coverage, specialized add-ons address risks specific to your business. Hired and non-owned auto coverage fills a critical gap if your team uses personal vehicles for business purposes, since standard personal auto policies exclude business driving and your company remains liable for accidents. Employment Practices Liability Insurance protects against discrimination, harassment, wrongful termination, and other workplace disputes-essential if you have employees in Connecticut. Cyber liability coverage has become non-negotiable for data-heavy businesses because Connecticut data breach laws require notification of affected customers, and those notification costs plus forensics, legal fees, and credit monitoring can devastate an uninsured business. Equipment breakdown coverage reimburses repair or replacement costs when essential machinery fails, along with lost income during downtime. Professional liability insurance protects service-based businesses against claims of errors, omissions, or negligence and is often tied to licensing requirements for Connecticut professionals.
Matching Coverage to Your Industry
The decision to add these options depends entirely on your industry, operations, and risk exposure. A restaurant faces different threats than a consulting firm, and a construction contractor needs different protection than a retail shop. Your specific risks determine which add-ons make financial sense and which ones you can safely skip.
Finding the Right Protection for Your Business
Identifying which coverages actually protect your operation requires honest assessment of how you work day-to-day. The wrong policy leaves you exposed to your biggest threats, while the right one covers what matters most without wasting money on unnecessary protection. Your next step involves evaluating your specific industry risks and comparing how different carriers handle the coverage options that matter most to your operation.
What Threatens Connecticut Businesses Most
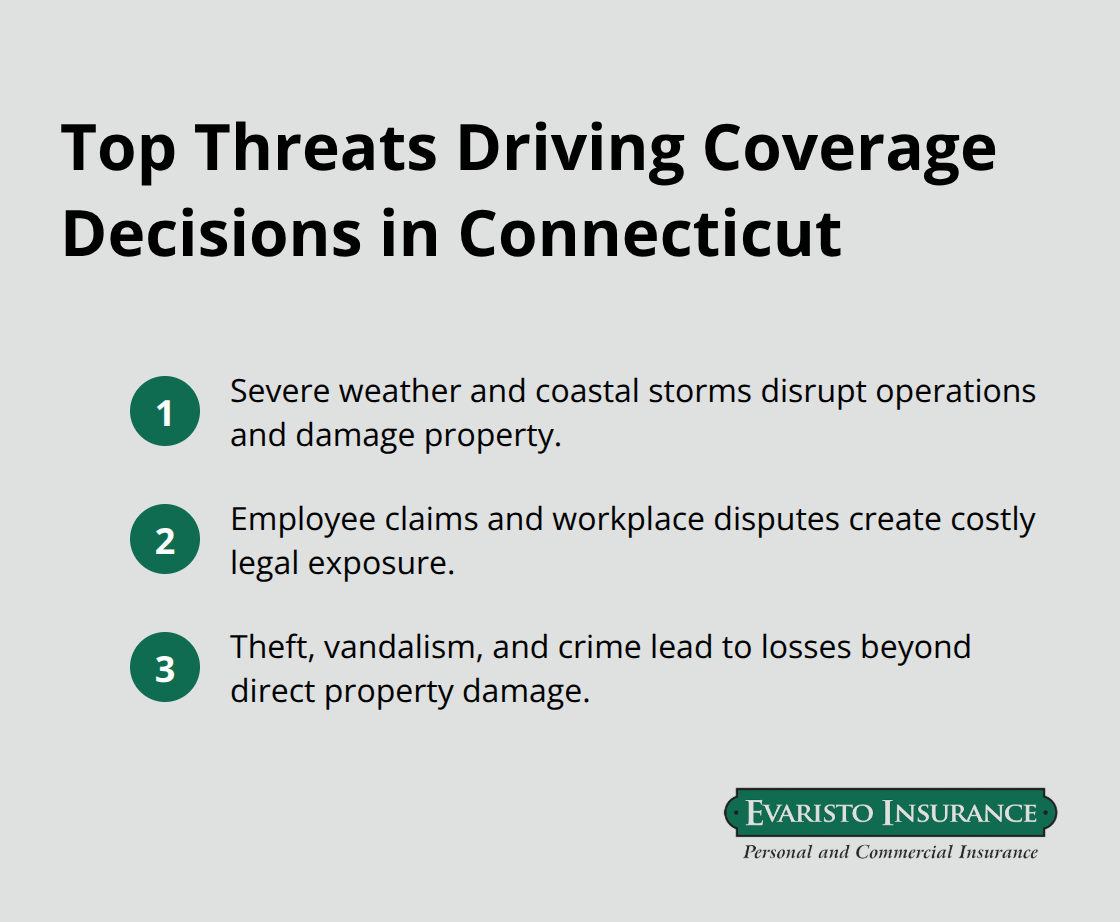
Connecticut’s geography and economy create specific vulnerabilities that generic business insurance policies often underestimate. Our location along the Atlantic coast exposes operations to nor’easters, hurricane damage, and flooding that can halt businesses for weeks. The National Weather Service data shows Connecticut experiences an average of 9.0 severe weather events annually, with nor’easters causing the most property damage to commercial structures.
Storm Damage and Weather Exposure
If your building floods or a storm damages your roof and inventory, standard property coverage pays for repairs. Business interruption coverage is what keeps your payroll flowing while you rebuild. Many Connecticut owners discover too late that they skipped this add-on, then face months without revenue while their insurance only covers physical damage. Weather damage is predictable in Connecticut; it’s not a question of if but when your operation will face storm exposure. Restaurants in coastal towns, warehouses in flood zones, and retail shops with aging roofs face higher risk than others, and your premiums should reflect that reality.
Employee Claims and Workplace Disputes
Employee-related claims represent the second major threat, particularly in Connecticut where workforce protections remain strict. Workers’ compensation is mandatory for any business with employees in Connecticut according to the CT Workers’ Compensation Commission, and claims for workplace injuries, repetitive strain, and occupational illness occur regularly across industries. Beyond workers’ comp, Employment Practices Liability Insurance protects your business when employees file discrimination, harassment, or wrongful termination lawsuits-claims that have become increasingly common and expensive to defend. A single employment lawsuit costs $50,000 to $150,000 in legal fees alone, even if you win.
Theft, Vandalism, and Crime Loss
Theft and vandalism round out the third major threat: Connecticut businesses lose inventory, equipment, and cash to break-ins and employee theft regularly. Commercial property coverage reimburses these losses, but the disruption to operations and customer service damage often exceeds the insurance payout. These three threat categories-severe weather, employee claims, and crime-should drive your coverage decisions and shape how you work with an insurance professional to build the right protection strategy.
Matching Coverage to Your Actual Business Reality
Start With Your Daily Operations
Connecticut businesses operate across wildly different risk profiles, which means the coverage that protects a plumbing contractor differs completely from what a consulting firm needs. Walk through your daily operations and identify where things actually go wrong. A restaurant owner faces slip-and-fall claims, food contamination disputes, and equipment breakdowns that shut down service. A contractor manages job site injuries, property damage to client spaces, and disputes with subcontractors. A retail shop worries about customer injuries, inventory theft, and weather damage to merchandise. Your industry determines which coverage options move from optional to essential.
Start with what your specific operation exposes you to rather than accepting generic business templates. If you employ people, workers’ compensation is non-negotiable in Connecticut-the law requires it for any business with employees. If your team drives personal vehicles for work, hired and non-owned auto coverage stops being optional and becomes mandatory protection. If you store customer data, cyber liability isn’t theoretical-Connecticut data breach notification laws make it a practical necessity.
Coverage Limits and Deductibles Shape Your Protection
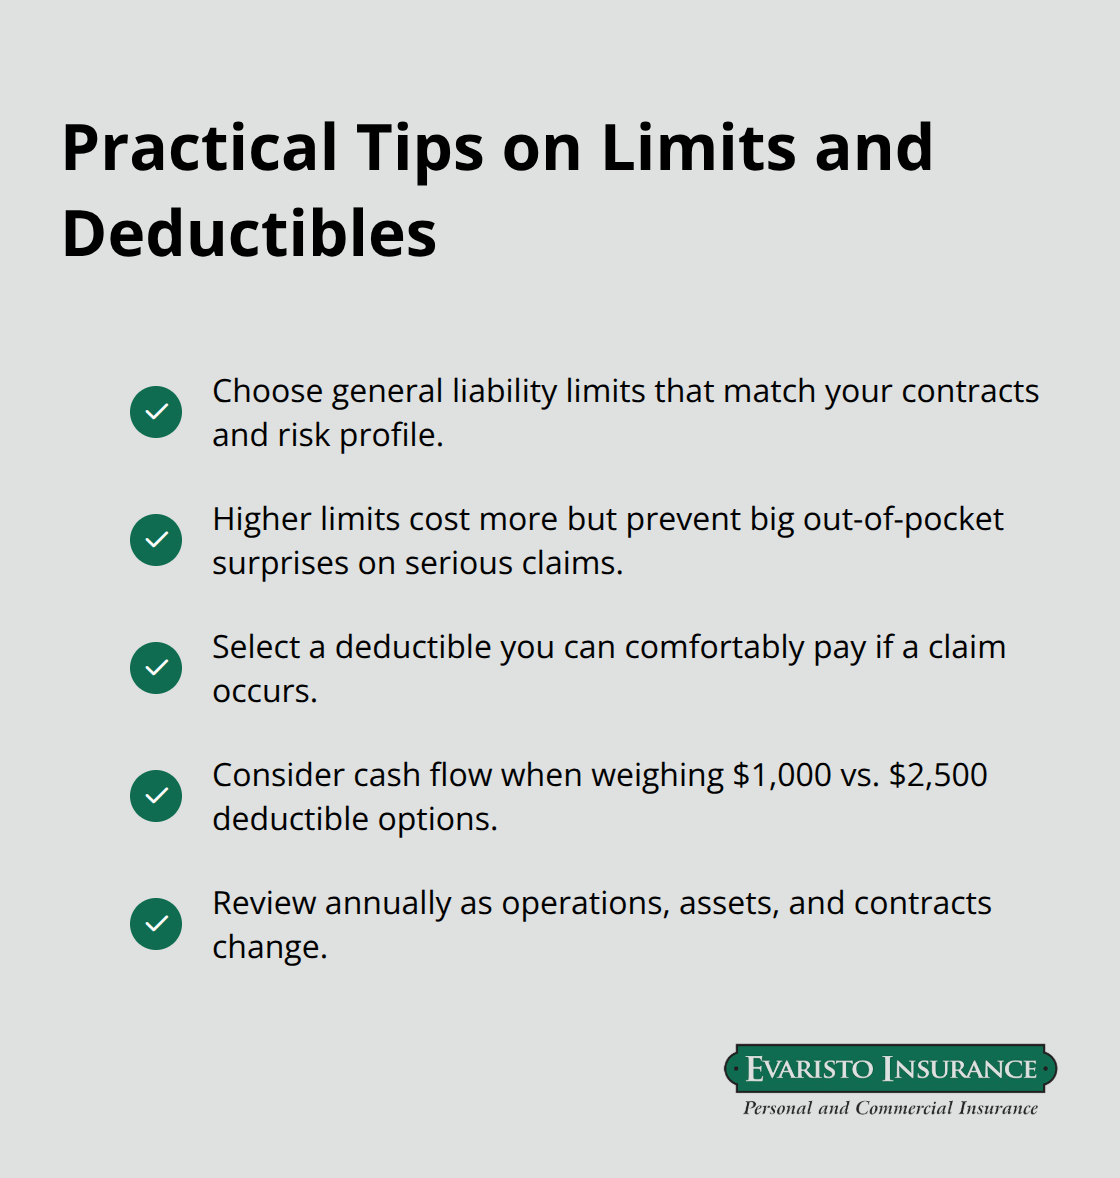
The coverage limits and deductibles you select matter just as much as which policies you buy. Typical Connecticut small businesses choose general liability limits between $300,000 and $1 million depending on their risk exposure and customer contracts. Higher limits cost more but protect you when a serious claim exceeds lower thresholds; lower limits save money but leave you personally liable for anything above the policy cap.
Deductibles work the opposite way: choosing a $2,500 deductible instead of $1,000 reduces your premium significantly, but you’ll pay more out of pocket when you file a claim. The right deductible balances your cash flow situation against your ability to absorb losses without financial stress.
Compare Quotes Across Multiple Carriers
Comparing quotes across multiple carriers reveals dramatic differences in how insurers price the same coverage for the same business. One carrier might quote $150 monthly for a contractor’s general liability while another charges $220 for identical limits-the difference stems from their underwriting approach, claims history with your industry, and risk appetite. This process surfaces coverage gaps that single-carrier quotes often miss. One insurer might bundle commercial property insurance into their BOP while another treats it as a separate add-on; one might offer equipment breakdown coverage while another doesn’t. When you stack quotes side by side, you spot which carriers actually understand your industry and which ones apply generic templates to your specific situation.
Work With a Local Agent Who Knows Connecticut
The final step-and the one most Connecticut owners skip-involves working with a local agent who understands both state regulations and your actual operations. A local agent knows that a West Hartford retail business faces different flooding risk than a Bristol plumbing contractor, and that knowledge shapes coverage recommendations. They verify you meet Connecticut’s legal requirements, identify coverage gaps before claims happen, and advocate for you when disputes arise with carriers. The alternative-buying insurance online based on price alone-feels efficient until you file a claim and discover your coverage doesn’t apply to your specific situation.
Final Thoughts
Business owners insurance coverage protects your Connecticut operation from the threats that actually matter: severe weather, employee disputes, theft, and the financial collapse that follows when operations halt unexpectedly. The right policy combines general liability, commercial property protection, and business interruption into one coordinated strategy rather than leaving gaps that surface only after disaster strikes. Your coverage limits, deductibles, and specialized add-ons should reflect your specific industry risks, not generic templates that ignore how your business actually operates.
Local expertise makes the difference between adequate protection and wasted premiums. A Connecticut agent understands that nor’easters hit our state regularly, that employment law disputes cost tens of thousands to defend, and that your industry faces risks your competitors in other states never encounter. They know state regulations, verify your legal compliance, and identify coverage gaps before claims happen. An online quote might feel cheaper initially, but it often leaves you exposed to exactly the losses you thought were covered.
Contact Evaristo Insurance for a quote that reflects your specific business, review the coverage options that address your biggest vulnerabilities, and implement protection before the next storm, employee dispute, or theft occurs. Our local offices in Ellington and West Hartford work with you to assess your actual operations and match coverage to your real risks. Your business deserves business owners insurance built for Connecticut, not generic policies designed for everywhere and nowhere.
Disclaimer: This blog post is for general informational purposes only and does not represent actual coverage, policy terms, or legal requirements. Insurance details vary by individual and jurisdiction. Please consult a licensed insurance professional for advice specific to your situation.

