
Landlord Insurance Options: Customizing Coverage For Your Rentals
Owning rental properties in Connecticut means protecting your investment from unexpected losses. The right landlord insurance options can make the difference between a manageable setback and a financial crisis.
At Evaristo Insurance, we help local property owners build coverage that matches their specific rental situations. This guide walks you through the protection available and how to customize it for your properties.
What Landlord Insurance Actually Protects
Landlord insurance in Connecticut protects your rental property from the specific risks that standard homeowners policies ignore. Property damage coverage pays for repairs when fire, wind, theft, or vandalism damages your building or structures. Liability protection shields you financially when a tenant or visitor gets injured on your property and sues for medical costs or lost wages. Connecticut has approximately 2.2 million renters according to U.S. Census data, which means thousands of landlords here face tenant-related claims annually.
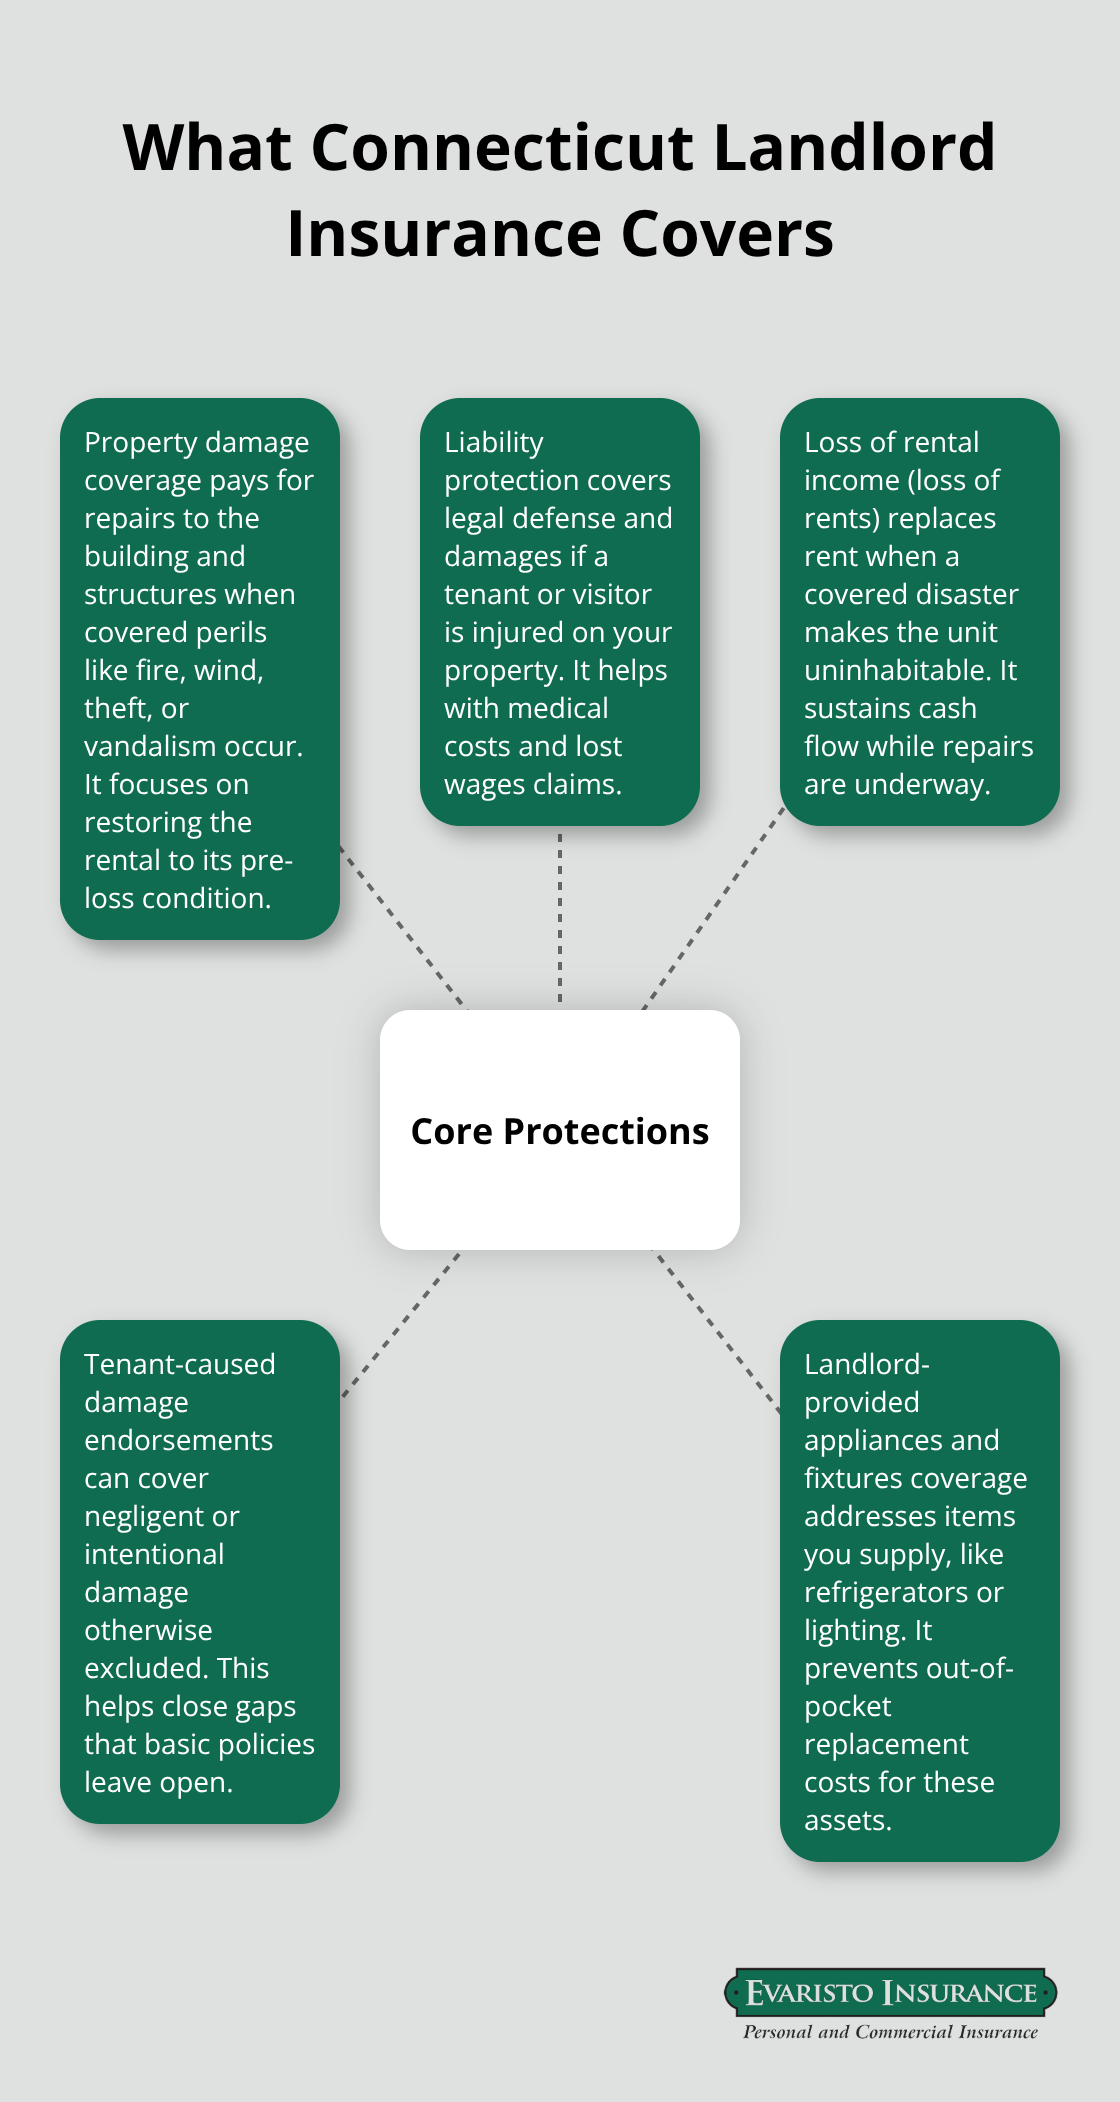
Loss of rental income coverage-sometimes called loss of rents-reimburses you when a covered disaster makes the property uninhabitable and tenants cannot pay rent. This matters because a single month without rental income can strain cash flow for properties with tight margins. Additional coverages address gaps that basic policies miss: water damage from tenant negligence, malicious acts by tenants, and damage to appliances or fixtures you provided. Many landlords skip these add-ons thinking they’re unnecessary, but that’s a mistake. A tenant’s intentional water damage or stolen air conditioning unit can cost thousands, and standard policies often exclude tenant-caused losses.
Coverage Limits Matter More Than You Think
Most Connecticut landlords underestimate their liability exposure. If a tenant’s guest falls down poorly maintained stairs and suffers a permanent injury, medical costs plus pain-and-suffering damages can easily exceed $500,000. Your basic policy limit of $100,000 or $300,000 won’t cover it, leaving you personally liable for the difference. Try liability limits of at least $300,000 for single-unit properties and $500,000 to $1,000,000 for multi-unit buildings. Property damage limits should reflect your building’s replacement cost, not its market value-replacement cost is what it actually costs to rebuild today, which runs higher than most landlords expect. An older Connecticut rental home might have a market value of $250,000 but a replacement cost of $350,000 or more depending on local construction costs.
When Standard Policies Fall Short
Tenants cause damage that weather and accidents don’t. Intentional damage, theft of your fixtures, or failure to maintain the property creates liability your homeowners policy specifically excludes. High-value rentals need specialty endorsements covering expensive appliances, updated systems, or premium finishes you’ve installed. Landlords with multiple properties should evaluate whether individual policies make sense or if a multi-unit package policy delivers better rates and coordinated coverage. Property management employment in Connecticut is expected to grow 1.80% between 2023 and 2025, reflecting the state’s active rental market, and property management companies almost universally choose comprehensive landlord policies over standard homeowners coverage because the protection gap is simply too wide. Understanding what your current coverage actually includes-and what it leaves exposed-sets the foundation for the next critical decision: which type of landlord insurance policy fits your portfolio.
Which Landlord Policy Type Fits Your Connecticut Portfolio
Connecticut landlords operate in vastly different situations, and cookie-cutter policies create expensive gaps. A single-family rental in Stamford faces different risks than a six-unit apartment building in Hartford or a luxury property in Fairfield. Basic landlord policies work for straightforward situations: you own one or two single-family homes, tenants are stable, and your property sits in a low-crime area. These policies typically cost between $400 and $800 annually and cover the essentials-property damage, liability, and loss of rents.
Basic Policies: When Simple Coverage Works
The trade-off with basic landlord policies is straightforward: minimal coverage means minimal cost, but you absorb risk on anything outside the basic categories. Many Connecticut landlords start here and outgrow this protection within two years as their portfolio expands or they experience a claim that reveals coverage holes. If your rental situation remains simple-one or two properties, stable tenants, low-crime neighborhoods-basic coverage handles your needs without unnecessary expense.
Multi-Unit Policies: Where Savings Add Up
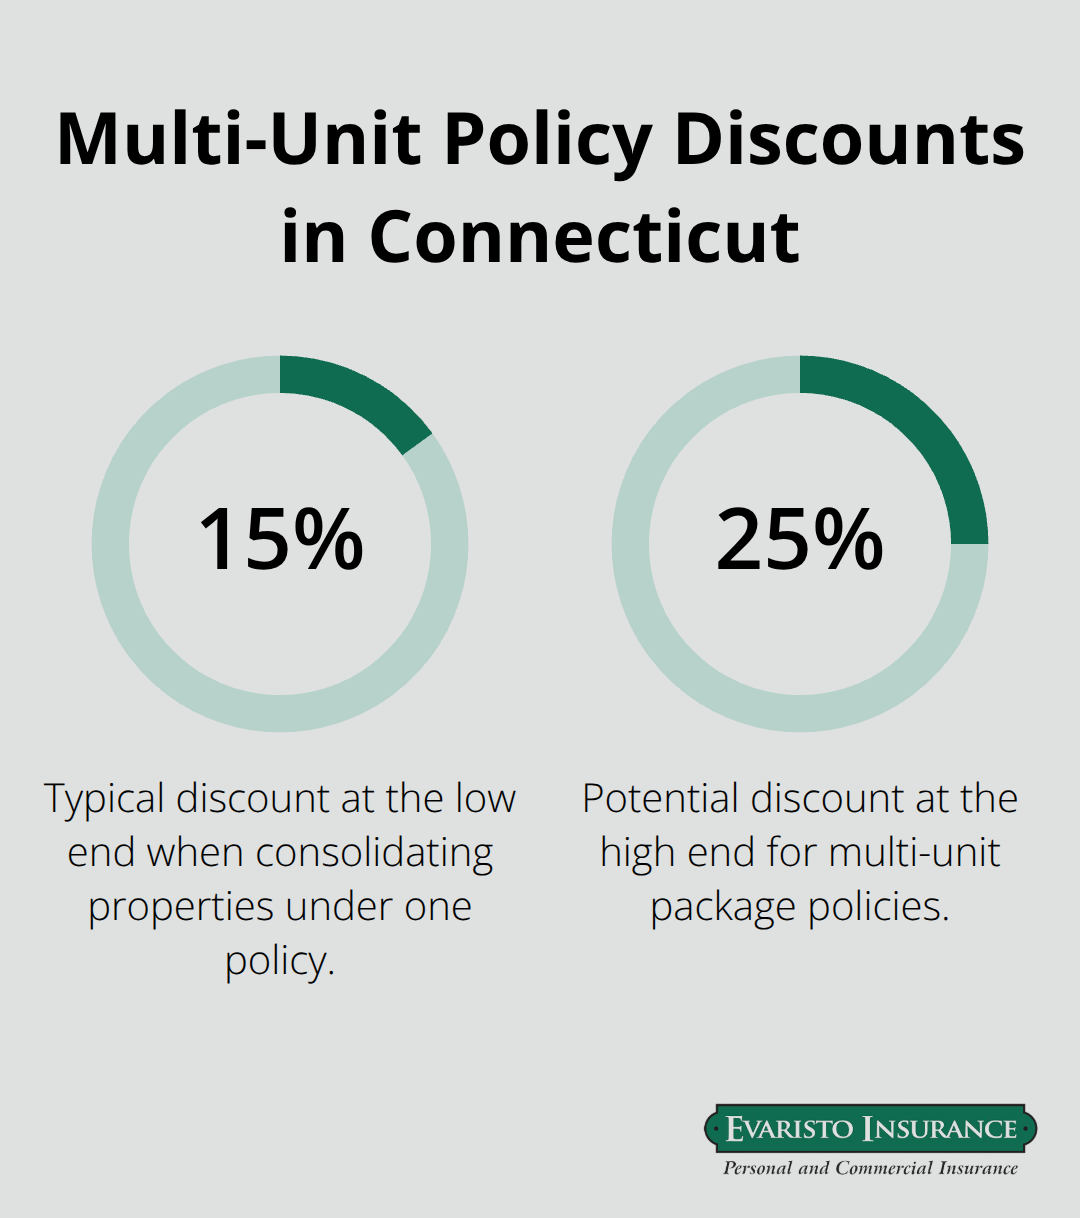
If you own multiple units or plan to acquire more properties, a multi-unit landlord policy makes financial sense immediately. Insurance carriers offer 15 to 25 percent discounts when you consolidate coverage across several properties under one policy rather than purchasing individual landlord policies for each unit. A landlord with three single-family homes paying $1,500 annually across three separate policies might pay $1,050 to $1,275 with a multi-unit package. Beyond the premium savings, multi-unit policies simplify administration-one renewal date, one deductible strategy, and coordinated coverage limits across your entire portfolio.
Specialty Policies: Protecting High-Value Rentals
High-value properties demand specialty landlord policies with endorsements that standard coverage ignores entirely. If your rental includes granite countertops, a newly installed HVAC system, premium appliances, or updated electrical wiring, the replacement cost exceeds what basic liability limits protect. Specialty policies for high-value rentals also address loss of rents more generously, sometimes covering 12 to 18 months of income instead of the standard 6 to 12 months. Connecticut’s active rental market means these properties attract serious tenant applications, but they also attract serious loss exposure.
Matching Policy Type to Your Growth Plan
The decision between these three structures comes down to your specific holdings and growth trajectory. Your current portfolio size and future acquisition plans should drive which policy type you select. Once you identify which structure fits your situation, the next step involves customizing that policy to address your unique property risks and coverage needs.
Customizing Coverage to Match Your Actual Rental Risks
Start by documenting exactly what sits on your Connecticut property and what could go wrong. Walk through each rental unit and photograph the condition of the roof, foundation, plumbing, electrical systems, and HVAC equipment. Note the age of each major system because a 25-year-old roof presents vastly different risk than a 5-year-old one, and insurers price accordingly.
Assess Your Property’s Specific Exposure
If your rental sits in a flood-prone area-Connecticut experiences significant flooding, particularly in communities near rivers and coastal regions-you need separate flood coverage because standard landlord policies exclude water damage from flooding. Document tenant turnover rates too. High turnover creates more opportunities for damage during move-outs, more liability claims from incoming and outgoing tenants, and more loss of rental income if units sit vacant between leases.
Calculate your actual monthly rental income because that number drives your loss of rents coverage limit. A three-unit building generating $4,500 monthly needs loss of rents coverage that replaces at least that amount, not a generic $3,000 limit that leaves you short. Review your property’s replacement cost with a local contractor or your insurance agent-don’t estimate.
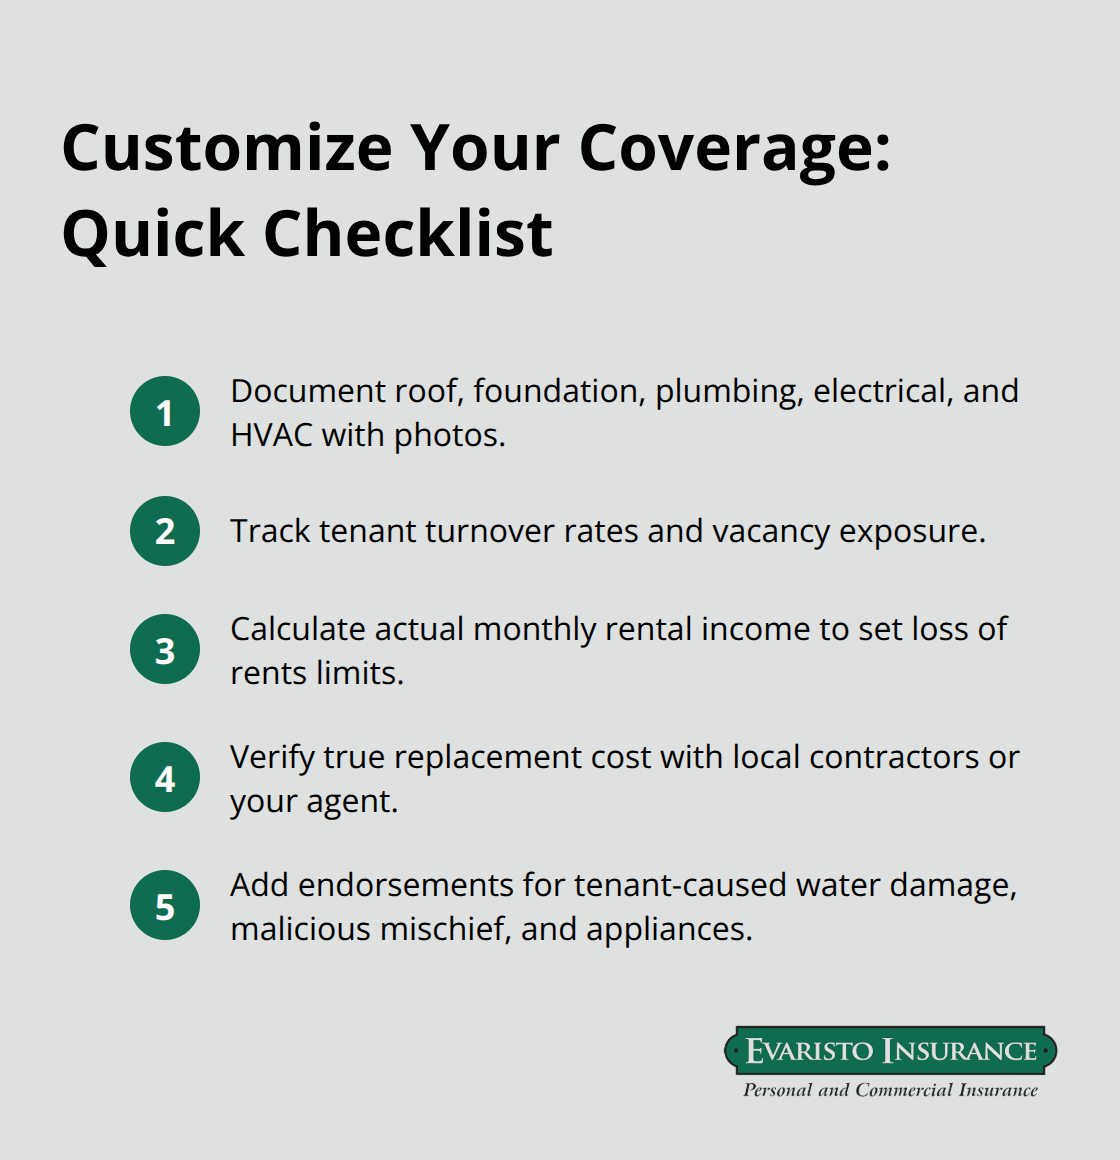
Connecticut construction costs run higher than national averages depending on your town, and underestimating replacement cost means underinsuring your property. A property that cost $300,000 to purchase might cost $425,000 to rebuild after a total loss due to current labor and material prices in your area.
Set Coverage Limits Based on Real Exposure, Not Guesswork
Liability limits require honest assessment of tenant quality and property condition. A poorly maintained property with frequent tenant complaints attracts litigation-prone tenants and multiplies injury claims. Connecticut’s court system awards significant damages in personal injury cases, and catastrophic injuries can reach substantial amounts. If your property has known maintenance issues, liability limits should start at $500,000 minimum, not $300,000.
High-crime neighborhoods increase theft and vandalism risk, meaning property damage limits need coverage for not just the building but also fixtures and appliances you’ve installed. An upgraded rental with new stainless steel appliances, updated flooring, and quality lighting fixtures costs thousands to replace, and basic coverage limits won’t absorb those losses. Seasonal rental properties face different exposure than year-round rentals-vacant properties attract break-ins and weather damage, so winter months in Connecticut demand coverage that reflects that increased risk.
Talk to your local insurance agent about your specific neighborhood, tenant demographics, and property condition rather than accepting standard limits that might protect someone else’s rental but not yours.
Add Endorsements Where Standard Coverage Stops
Standard landlord policies exclude damage tenants cause intentionally or through negligence with property you provided. A water damage endorsement covers tenant-caused leaks and flooding, which happens far more often than most landlords anticipate-Connecticut’s humid climate and older rental stock mean plumbing failures are common. Malicious mischief coverage protects against intentional damage by tenants, which matters more than landlords think because proving intentional versus accidental damage creates disputes that leave you uninsured.
If your rental includes appliances you own-refrigerators, washers, dryers, dishwashers-add an endorsement covering those specifically because standard policies treat tenant-provided versus landlord-provided appliances differently. High-value endorsements make sense if your rental contains expensive upgrades like granite counters, premium appliances, or updated systems that exceed standard replacement cost calculations. Loss assessment coverage protects you if your condo association or homeowners association levies special assessments for building damage, which Connecticut property owners face occasionally when shared structures need major repairs.
Final Thoughts
Selecting the right landlord insurance options requires matching your coverage to your actual property risks, not settling for generic limits that work for someone else’s rental. Connecticut landlords who customize their policies around documented replacement costs, realistic liability exposure, and specific tenant situations avoid the expensive gaps that create financial crises. The difference between adequate protection and inadequate coverage often emerges only after a claim, when you discover what your policy actually covers and what it leaves exposed.
Working with a local insurance agent who understands Connecticut’s rental market gives you a significant advantage over online quotes and national carriers. Your agent can assess your specific neighborhood’s risk profile, review your property’s condition and systems, and recommend coverage limits based on local construction costs and court award patterns rather than national averages. An agent familiar with Connecticut properties knows which endorsements matter for your situation and which ones you can skip without creating exposure.
Start with documentation about your properties: replacement cost estimates from local contractors, photos of major systems and conditions, and your actual monthly rental income figures. Contact Evaristo Insurance with this information so we can review your current coverage and recommend customizations that address your real exposure. The right landlord insurance options protect your rental income and your personal assets from the specific risks your Connecticut properties face.
Disclaimer: This blog post is for general informational purposes only and does not represent actual coverage, policy terms, or legal requirements. Insurance details vary by individual and jurisdiction. Please consult a licensed insurance professional for advice specific to your situation.

