
Rideshare Vehicle Coverage: Insuring Your Ride-Sharing Career
Driving for Uber or Lyft in Connecticut means your personal auto insurance won’t protect you when the app is on. That gap between accepting rides and picking up passengers leaves you exposed to serious liability risks.
At Evaristo Insurance, we know rideshare vehicle coverage isn’t optional-it’s the foundation of a sustainable driving business. This guide walks you through your coverage options and how to pick the right protection for your income.
Why Your Personal Auto Policy Leaves You Unprotected
Personal Policies Exclude Commercial Activity
Your personal auto insurance policy protects you during personal, non-commercial driving. The moment you turn on a rideshare app in Connecticut, you cross into commercial territory, and your insurer stops covering you. This isn’t a gray area or a technicality-it’s explicitly stated in virtually every personal auto policy sold in the state.
Insurance companies classify rideshare driving as a commercial activity because you operate a vehicle for compensation, which fundamentally changes the risk profile from their perspective. If you get into an accident while driving for Uber or Lyft with your personal policy as your only coverage, your claim will face denial, leaving you personally liable for medical bills, vehicle damage, and legal costs.
The Dangerous Coverage Gap Between App-On and Passenger Pickup
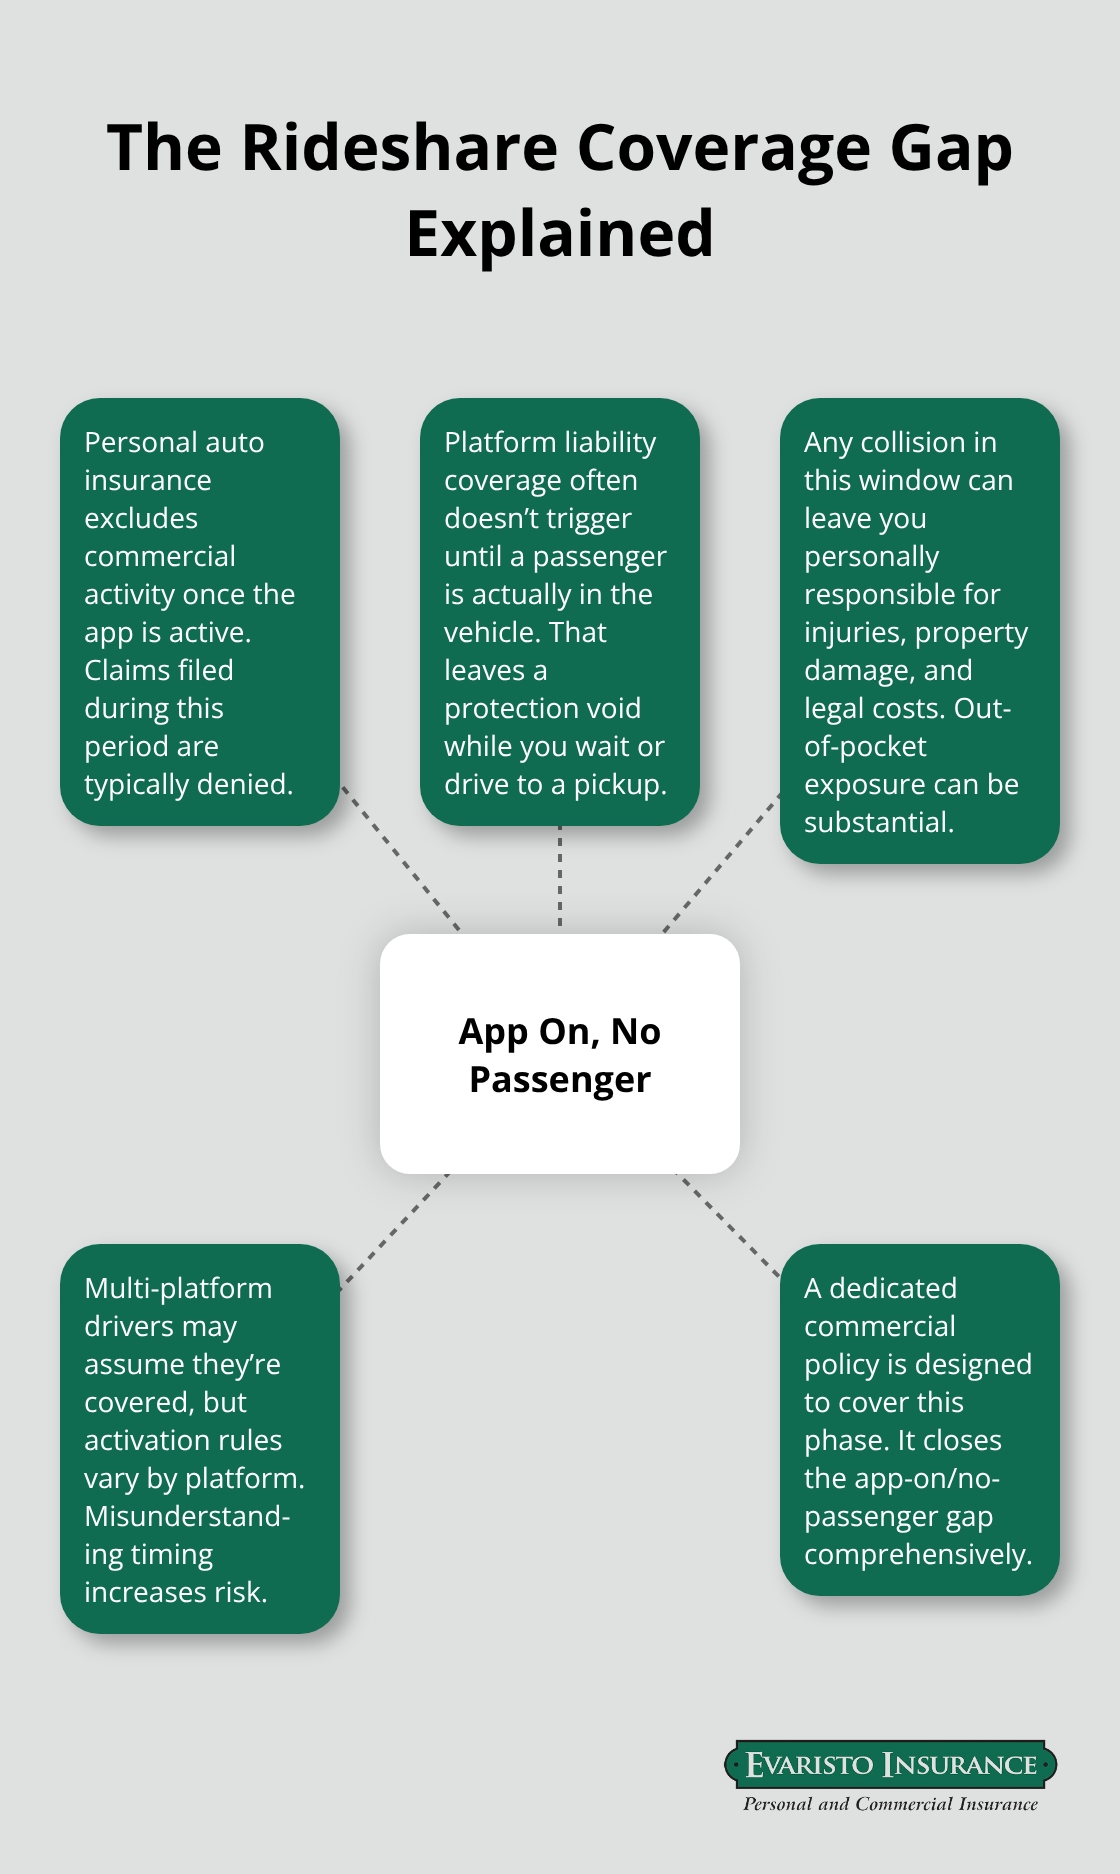
A coverage gap emerges during the period when your app is active but you haven’t yet picked up a passenger. Many Connecticut rideshare drivers don’t realize that this in-between time-when you wait for a request or head to meet a passenger-exposes you to significant liability with zero protection.
Your personal policy won’t cover you because the app is on. The rideshare platform’s limited liability coverage typically doesn’t activate until a passenger actually sits in your vehicle. If another driver hits you during this window, or if you cause an accident, you operate without meaningful insurance protection. This gap represents one of the most overlooked risks in rideshare driving.
Passenger Liability Risks Personal Policies Can’t Handle
Carrying passengers for payment introduces liability risks that personal policies simply weren’t designed to handle. A passenger injured in your vehicle, a third party hit by your car while transporting someone for money-these situations create legal exposure that far exceeds what a standard personal auto policy provides.
Connecticut requires rideshare drivers to carry appropriate commercial coverage, and insurance companies take this requirement seriously when processing claims. The liability exposure you face as a rideshare driver demands protection specifically built for commercial transportation. Understanding your coverage options becomes the next step in protecting both your vehicle and your income.
What Rideshare Coverage Actually Costs in Connecticut
Three Coverage Paths with Different Price Tags
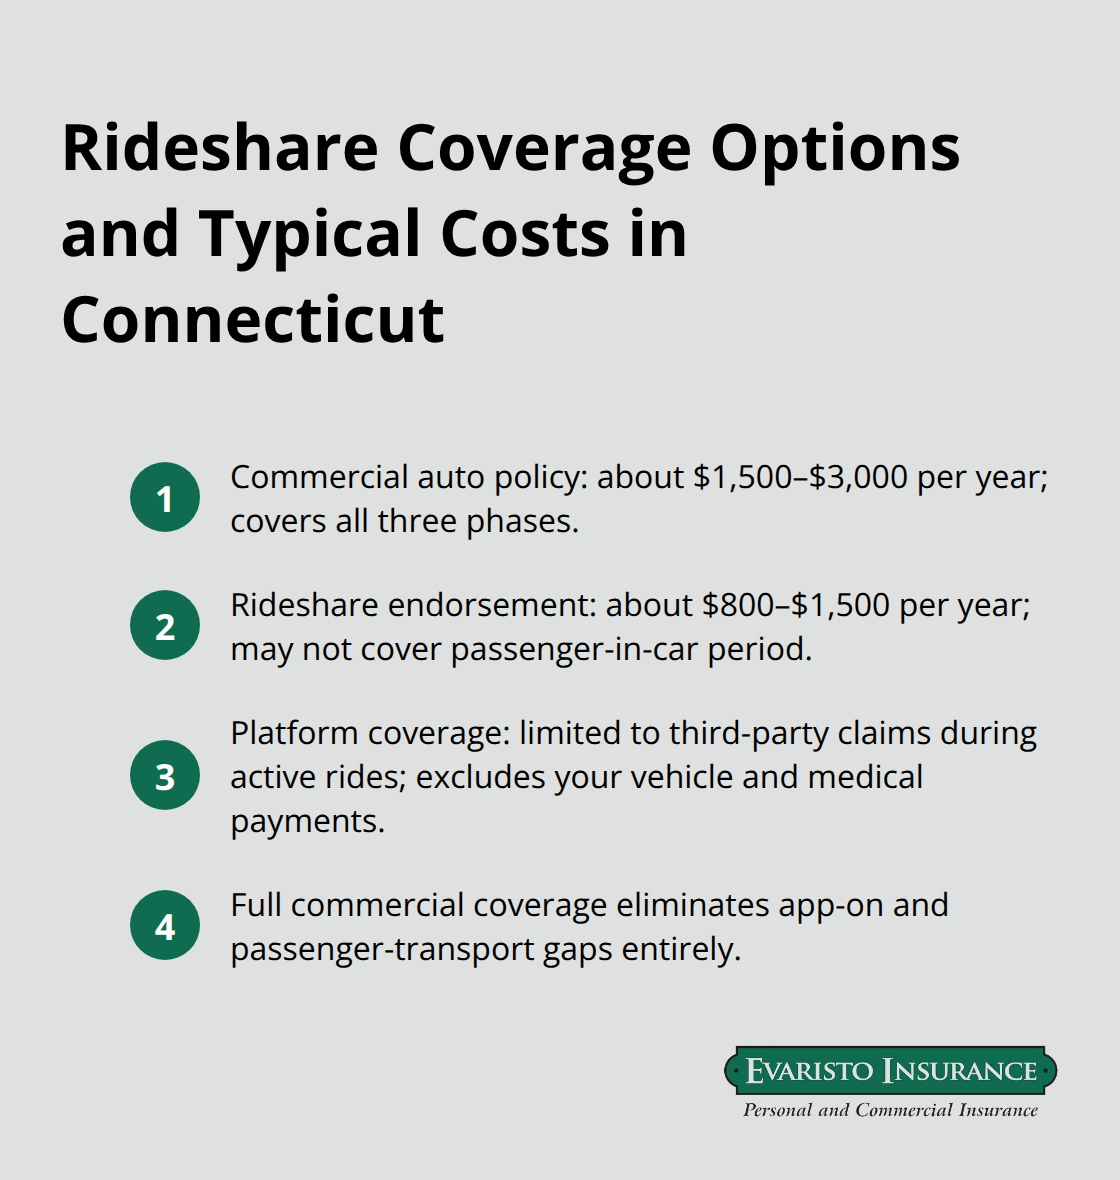
Connecticut rideshare drivers can choose from three main coverage approaches, and costs vary significantly based on your platform and driving volume. Commercial auto policies from major carriers like State Farm, Allstate, and Hartford add $1,500 to $3,000 annually to your existing personal auto insurance, depending on your driving record and coverage limits. These full commercial policies protect you during all three phases of rideshare work: when your app is on but you wait for a ride, when you transport passengers, and when you drive for personal reasons between shifts. The broader protection eliminates the coverage gaps that rideshare-specific endorsements leave open.
Rideshare Endorsements: The Budget Option with Real Limitations
Rideshare-specific endorsements and add-ons offer a more affordable middle ground, typically running $800 to $1,500 per year. These endorsements attach to your existing personal policy and fill the gap between when your app activates and when a passenger enters your vehicle. However, this approach carries a critical limitation: once a passenger sits in your car, many endorsements still fail to cover you adequately because they function as supplements rather than comprehensive commercial coverage.
Platform Coverage Creates Confusion
Uber and Lyft provide their own limited liability coverage during active rides, but this protection only covers third-party claims, not damage to your vehicle or medical payments for you or your passengers. If you drive for multiple platforms simultaneously, each one’s insurance activates at different points and carries different coverage limits, creating confusion about which policy protects you in any given moment. Connecticut drivers who take rideshare seriously should reject the endorsement approach and invest in a full commercial auto policy instead, because the modest annual savings disappear instantly if you face a significant claim during the app-on-but-passenger-not-yet-picked-up window.
Finding Your Right Coverage Level
The choice between these options depends on your actual mileage, which platforms you use, and how much risk you’re willing to accept. A driver who works part-time for a single platform might find an endorsement acceptable, while someone who drives full-time for multiple services needs comprehensive commercial coverage. Your driving record also matters significantly-drivers with accidents or violations pay substantially more for any coverage type. Understanding exactly when coverage activates and what gaps remain in each option matters far more than simply choosing the cheapest option available.
Matching Coverage to Your Actual Rideshare Operation
Track Your Mileage to Determine Coverage Needs
The coverage you need depends entirely on how you actually drive, not on generic recommendations. Start by tracking your mileage for two weeks during your normal rideshare schedule, then multiply that by 26 to estimate your annual rideshare miles. A Connecticut driver averaging 200 miles per week during rideshare work logs roughly 10,400 miles annually, which qualifies as part-time activity. Someone hitting 600 miles weekly reaches 31,200 annual miles, crossing into territory where full-time commercial coverage becomes non-negotiable. Your insurance company will ask for this number anyway when you apply, so gathering actual data now prevents surprises later.
Choose Your Coverage Strategy Based on Driving Volume
Part-time drivers working a single platform might accept the coverage gaps in a rideshare endorsement, while full-time operators juggling Uber and Lyft simultaneously face too much exposure with anything less than comprehensive commercial auto insurance. The endorsement approach costs $800 to $1,500 annually but leaves you unprotected during the app-on-but-passenger-not-yet-picked-up window. Full commercial auto policies from major carriers run $1,500 to $3,000 per year and eliminate these gaps entirely. Your actual mileage determines which option makes financial sense-a driver logging 10,000 annual rideshare miles operates in a different risk category than someone hitting 35,000 miles.
Set Your Deductible and Coverage Limits Strategically
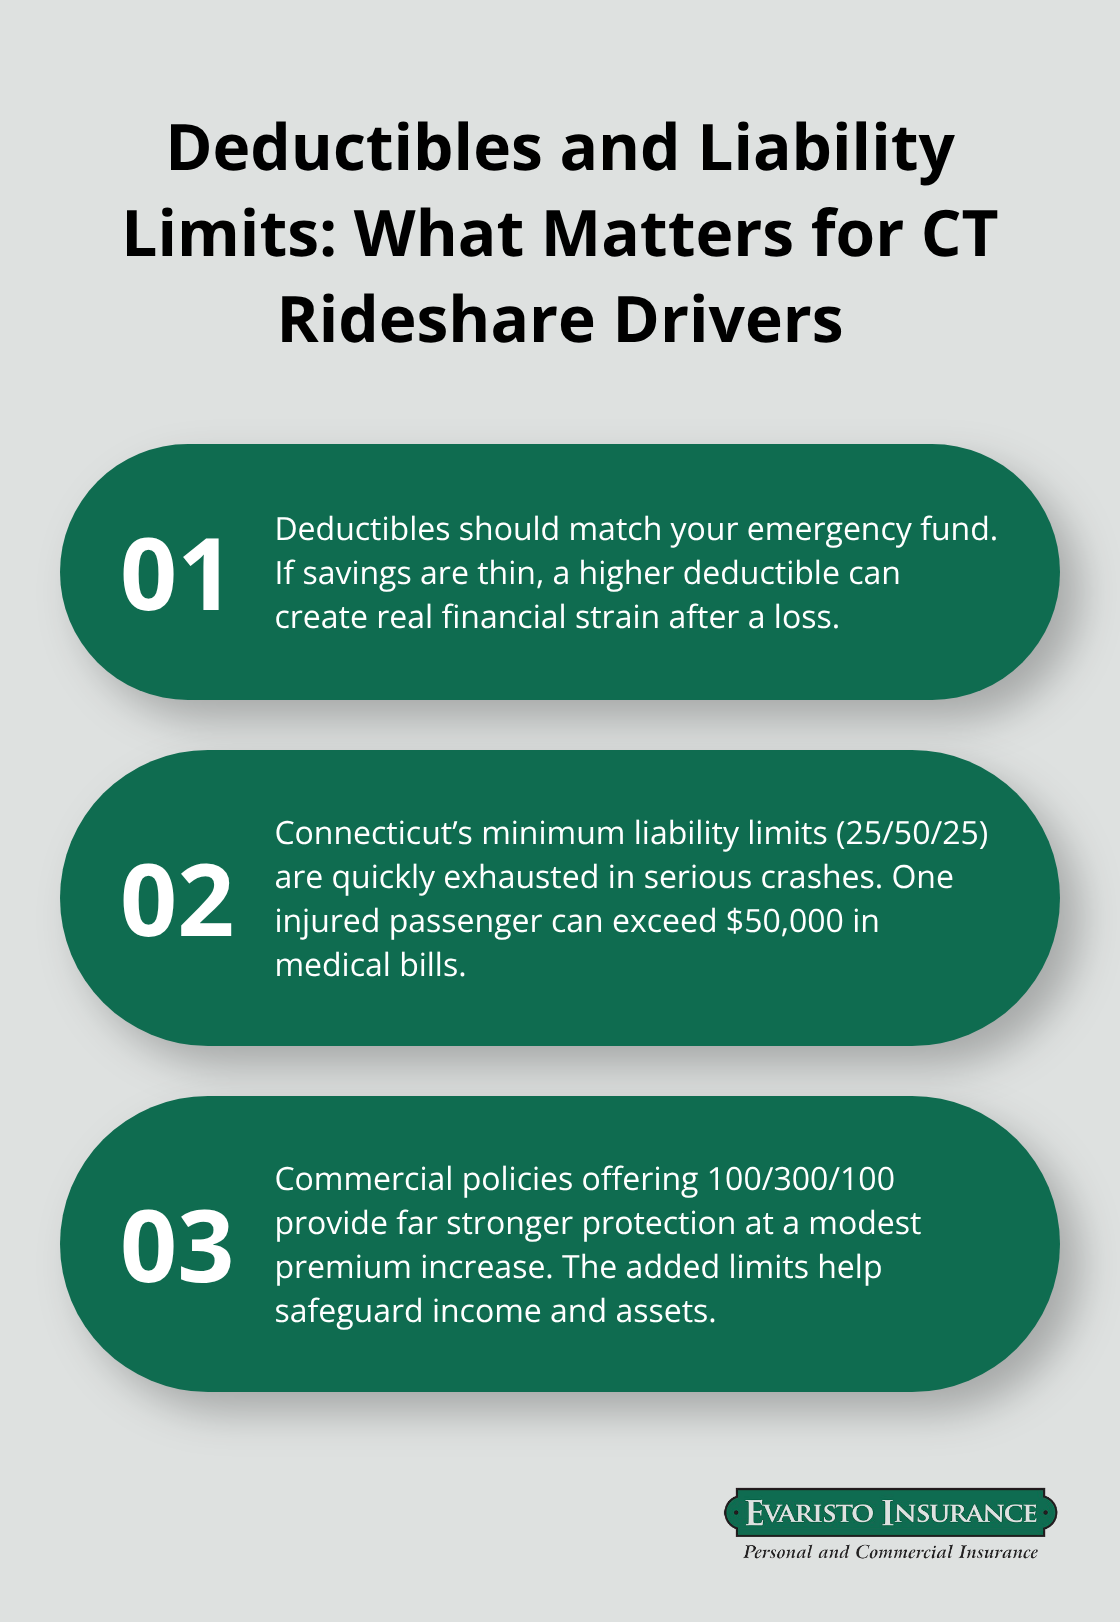
A $500 deductible sounds reasonable until you total your vehicle and realize you’re paying that amount out of pocket while your rideshare income disappears during repairs. Connecticut rideshare drivers should evaluate their emergency fund before selecting a deductible level. If you have less than $2,000 in savings, a $1,000 deductible creates genuine financial danger when a claim hits. Coverage limits matter equally-standard Connecticut minimum liability is $25,000 per person and $50,000 per accident for bodily injury, plus $25,000 for property damage. These minimums evaporate instantly in serious accidents. A single injured passenger with medical bills exceeding $50,000 leaves you personally liable for the difference. Commercial auto policies typically offer 100/300/100 limits at modest cost increases, and that extra protection justifies the expense.
Compare specific quotes showing your deductible options and coverage limits side-by-side rather than focusing solely on premium price.
Understand What Platform Coverage Actually Protects
Uber’s contingent liability coverage activates once a passenger enters your vehicle but maxes out at $100,000 per accident-insufficient for serious injuries. Lyft’s coverage mirrors this approach. Neither platform covers your vehicle damage, medical payments for you, or the app-on-but-passenger-not-yet-picked-up gap that caused accidents in thousands of cases. If you drive for both platforms, you face the confusion of tracking which coverage applies in any given moment. Connecticut drivers who treat rideshare as genuine income cannot rely on platform coverage alone. Commercial auto policies from major carriers fill these gaps comprehensively and protect your vehicle, your income, and your personal assets when something goes wrong.
Final Thoughts
Rideshare vehicle coverage protects your income and personal assets when accidents happen, and Connecticut drivers cannot afford to ignore this protection. Your personal auto insurance explicitly excludes rideshare activity, platform coverage maxes out at $100,000 per accident and covers only third-party claims, and the gap between app-on and passenger-pickup leaves you exposed during thousands of accidents annually. Full commercial auto policies from major carriers eliminate these gaps entirely and cost $1,500 to $3,000 annually depending on your driving record and coverage limits.
Your coverage decision depends on three concrete factors: your actual annual rideshare mileage, your emergency fund relative to potential deductibles, and your willingness to accept the gaps that endorsements leave open. Part-time drivers logging under 15,000 miles annually face different risk profiles than full-time operators hitting 30,000 or more miles, and your deductible choice matters far more than premium price alone. A $500 deductible sounds affordable until you’re paying it while your vehicle sits in the shop and your rideshare income stops.
Evaristo Insurance compares multiple carriers to find rideshare vehicle coverage matching your actual driving patterns and budget. We’ve served Connecticut since 1989 as a family-owned independent agency, and we understand the rideshare landscape across the state. Contact us to review your specific situation and receive quotes that reflect your real mileage and coverage needs.
Disclaimer: This blog post is for general informational purposes only and does not represent actual coverage, policy terms, or legal requirements. Insurance details vary by individual and jurisdiction. Please consult a licensed insurance professional for advice specific to your situation.

