
Homeowners Insurance Coverage Options: Finding The Right Fit
Your homeowners insurance coverage options directly impact how protected your family and assets truly are. Many Connecticut homeowners either over-insure or under-insure simply because they don’t understand what’s available to them.
At Evaristo Insurance, we’ve helped hundreds of local families build policies that match their actual needs and budgets. This guide walks you through the coverage choices that matter most.
What Your Standard Policy Actually Covers
Standard homeowners insurance in Connecticut covers four critical areas, and understanding exactly what falls under each one prevents costly gaps later. Dwelling coverage protects the structure itself-your walls, roof, foundation, and attached structures like a garage. This is the foundation of your policy, and insurers price it based on your home’s replacement cost, not market value. If your home would cost $450,000 to rebuild today, that’s what your dwelling coverage should reflect. Personal property coverage reimburses you for belongings inside your home, typically at 70% of your dwelling limit unless you upgrade to replacement cost coverage. Most Connecticut homeowners miss this detail: standard personal property coverage pays actual cash value, meaning a five-year-old television worth $800 new depreciates to maybe $200. Upgrading to replacement cost coverage costs roughly 10–15% more but pays what you’d actually spend to replace that television today. Personal liability protection covers legal costs and damages if someone is injured on your property and sues you. Connecticut standard policies typically include $100,000 in liability coverage, which frankly is insufficient for most homeowners. If a guest falls on your icy driveway in January and requires surgery, $100,000 disappears fast once legal fees and medical bills accumulate. Loss-of-use coverage-sometimes called additional living expenses-pays for temporary housing if your home becomes uninhabitable after a covered loss. Most policies include this at 20% of your dwelling coverage, which translates to roughly $9,000 for a $450,000 home. That covers maybe three months in a rental if you’re careful, but Connecticut’s tight rental market means you could easily exceed that in a major loss.
The Coverage Gaps Standard Policies Leave Open
Water damage presents the biggest trap. Standard homeowners insurance excludes sewer backup and flooding entirely. Flood damage affects Connecticut homeowners regularly, yet most rely on standard coverage that won’t pay a dime. You need separate flood insurance if you’re in a designated flood zone, and honestly, you should consider it even outside those zones since water finds ways standard maps don’t predict.
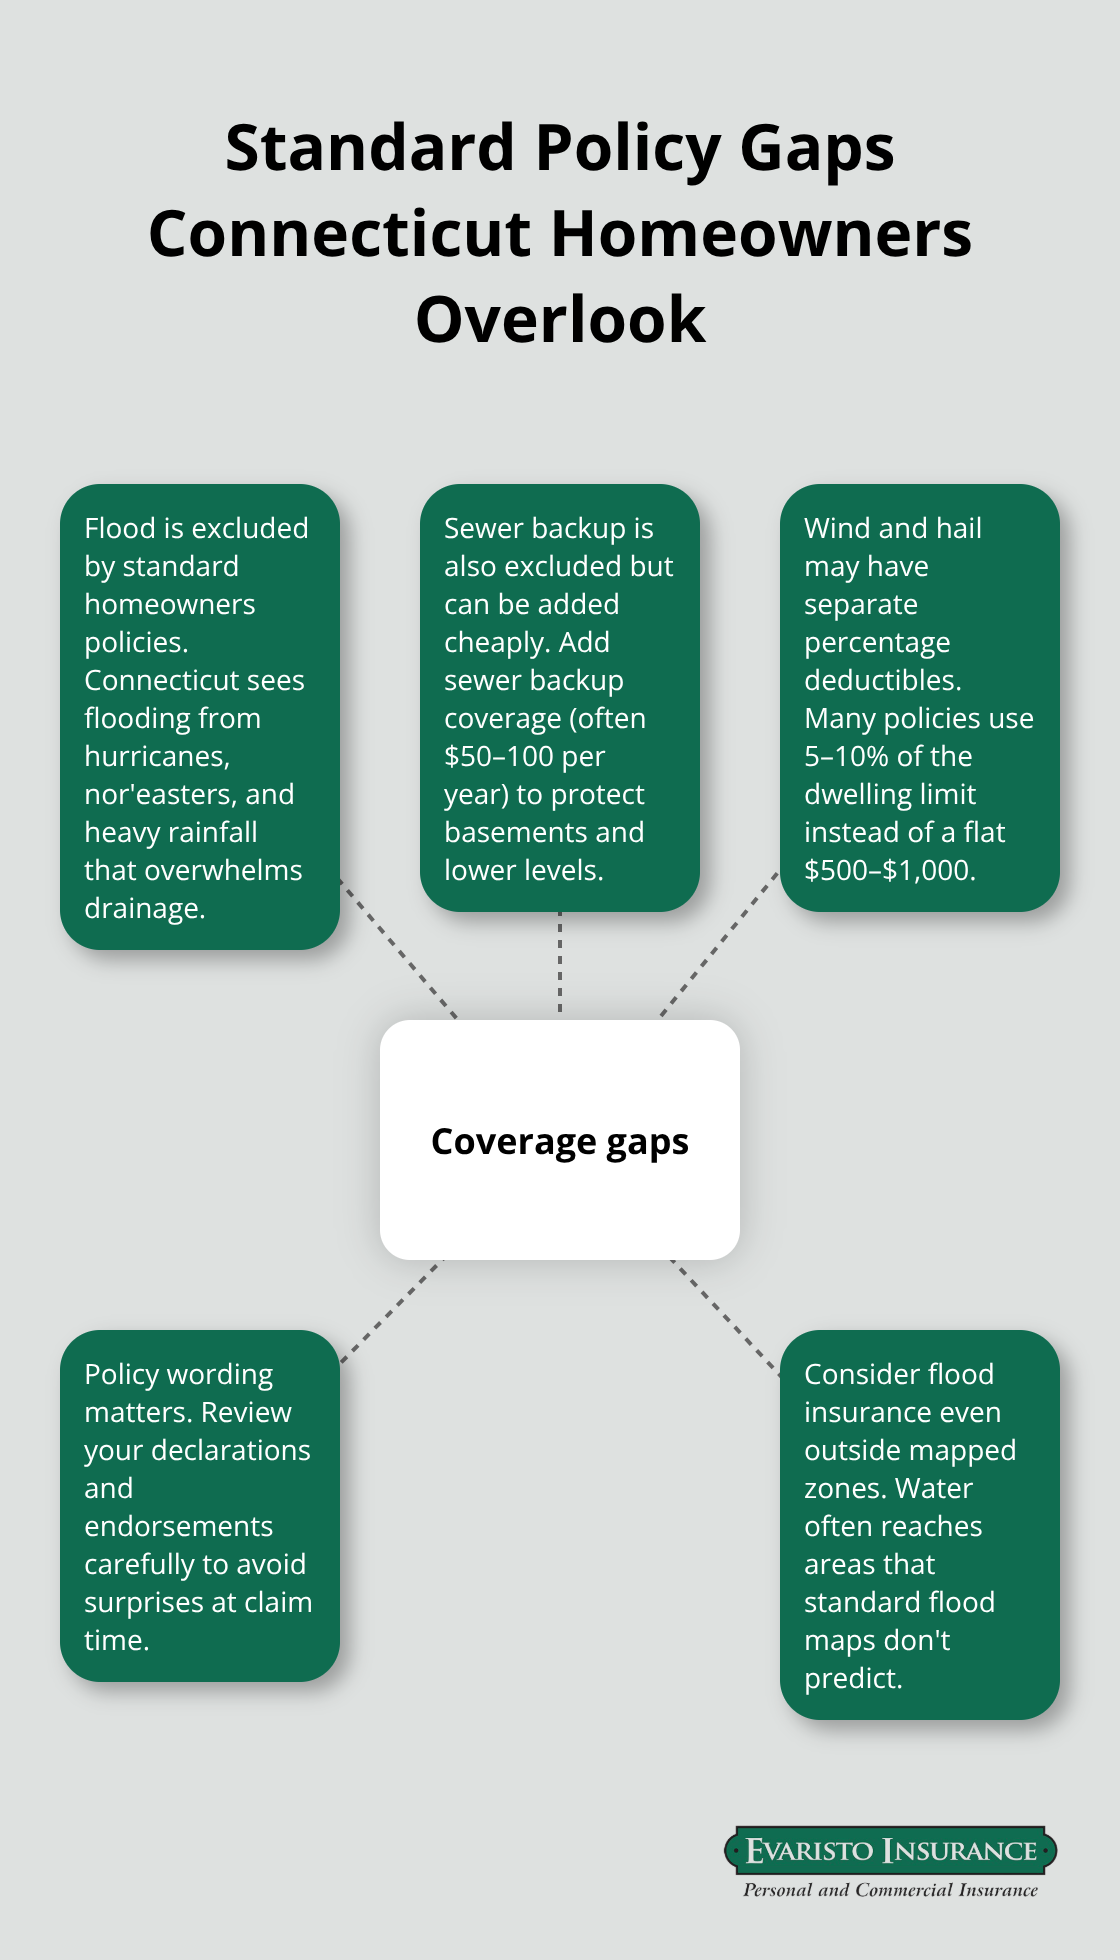
Sewer backup coverage is an inexpensive add-on-typically $50–100 per year-that covers damage when your home’s drainage system backs up, a real risk in older Connecticut neighborhoods with aging municipal systems. Wind and hail damage is covered, but many policies carry separate deductibles for these perils, sometimes 5–10% of your dwelling coverage instead of the standard $500–1,000. A $450,000 home with a 5% wind deductible means you’re out $22,500 before insurance pays anything for hurricane damage. Review your specific policy language carefully here.
Why Liability Coverage Needs Serious Attention
Personal liability is where Connecticut homeowners most consistently under-protect themselves. $100,000 sounds substantial until one accident happens. A guest injured on your property can sue not just for medical bills but for pain and suffering, lost wages, and permanent disability costs. An umbrella liability policy extending your protection to $1 million costs roughly $150–250 annually and stacks on top of your homeowners coverage. This is the single best value protection you can add. Medical payments coverage-typically $1,000–5,000-covers immediate medical expenses for guests regardless of fault, which often prevents lawsuits before they start. Some Connecticut homeowners skip this to save $20 per year, then face a significant lawsuit when a neighbor’s child hits their head on a deck beam.
Moving Forward with Your Coverage Assessment
The gaps between what you think you’re covered for and what you actually are covered for can cost your family tens of thousands of dollars. Your next step involves looking closely at your home’s specific characteristics-its age, location, and what’s inside it-to identify which additional coverages matter most for your situation.
Beyond Standard Protection
Flood Risk in Connecticut Requires Separate Coverage
Flood damage ranks as Connecticut’s most underestimated homeowners insurance gap, and the numbers prove it. The National Flood Insurance Program reports that standard homeowners policies exclude all flood damage, yet Connecticut experiences flooding from hurricanes, nor’easters, and localized heavy rainfall that overwhelms drainage systems. If you live within a designated flood zone, your mortgage lender requires separate flood insurance. Outside those zones, most Connecticut homeowners assume they’re safe, but flood damage occurs regularly in areas never mapped as high-risk.
Flood insurance through the National Flood Insurance Program takes effect after a 30-day waiting period, so you should purchase coverage before storm season arrives. Premiums vary based on flood zone and home elevation, but basic coverage often starts around $400–800 annually for moderate-risk properties. This protection covers damage that standard policies explicitly exclude, making it essential for any Connecticut homeowner in or near flood-prone areas.
Sewer Backup Coverage Protects Older Neighborhoods
Sewer backup deserves equal attention because standard policies completely exclude it, yet it happens frequently in Connecticut’s older neighborhoods. Municipal sewer systems in towns like Hartford, New Haven, and Stamford date back decades, and when heavy rain overwhelms those systems or tree roots infiltrate pipes, your home’s drains back up into basements and lower levels. Sewer backup coverage costs $50–100 per year and covers both repairs and contents damage, making it one of insurance’s best values.
This add-on protects your home regardless of age or neighborhood, though older properties face higher risk. The cost remains minimal compared to the potential damage from sewage backing into your living spaces, which can reach tens of thousands of dollars in cleanup and restoration.
Earthquake Insurance and Connecticut’s Seismic Risk
Earthquake insurance and high-value item coverage address different risk profiles entirely. Connecticut sits outside major seismic zones, so earthquake coverage isn’t essential for most homeowners, though it remains available as a separate policy if you want additional protection. Your location and home characteristics should drive this decision rather than general anxiety about seismic activity.
Protecting Valuable Items Beyond Standard Limits
Valuable items present a far more practical concern for Connecticut homeowners. Standard personal property coverage caps certain categories like jewelry at $1,500–2,500 total, which means that inherited diamond ring or your spouse’s watch collection receives minimal protection. Scheduled personal property endorsements cost roughly $100–200 annually per $10,000 in coverage and protect specific items at replacement cost without depreciation.
Fine art, collectibles, electronics, and musical instruments have similar sublimits under standard policies. If you own items worth more than your policy’s standard limits, scheduled endorsements prevent devastating underinsurance. Connecticut homeowners with significant collections should request an inventory appraisal and work with an agent to schedule high-value items properly, protecting what matters most without overpaying for blanket coverage you don’t need.
Matching Additional Coverage to Your Specific Situation
The additional coverages available to you depend entirely on what you own and where you live. A homeowner in a flood-prone area near the coast faces different risks than someone in an elevated inland location. Similarly, someone with valuable jewelry collections needs different protection than a homeowner with modest belongings. Your next step involves comparing homeowners insurance policies to identify which of these additional options actually applies to your Connecticut home and your specific circumstances.
How to Choose the Right Coverage for Your Connecticut Home
Calculate Your Home’s True Replacement Cost
Start with your home’s replacement cost, not what you could sell it for today. Market value and rebuilding cost diverge significantly in Connecticut’s real estate landscape. A home worth $450,000 on the market might cost $520,000 to rebuild from scratch because construction labor and materials have increased faster than property values. Contact local contractors for rebuild estimates or use the Rebuilding Cost Calculator from the National Association of Insurance Commissioners to establish an accurate dwelling coverage limit. Underestimating replacement cost leaves you personally liable for the gap after a total loss.
Inventory Your Personal Property and Set Limits
Once you establish dwelling coverage, calculate personal property limits through a complete home inventory. Most Connecticut homeowners guess at this number and end up underinsured. Walk through each room and photograph items, noting approximate replacement costs for electronics, furniture, clothing, and kitchen appliances. Standard policies limit personal property to 70% of dwelling coverage, which means a $450,000 home includes roughly $315,000 in belongings coverage. If your actual possessions exceed that amount, you need higher limits or scheduled endorsements for valuable items.
Assess Your Liability Exposure Honestly
Liability exposure requires honest assessment of your property’s risk factors. If you have a pool, trampoline, or frequently host guests, your lawsuit risk increases substantially. Connecticut homeowners with these features should carry at least $300,000 in liability coverage, not the standard $100,000, and seriously consider adding an umbrella policy for $1 million in additional protection. The umbrella costs roughly $150–250 annually and becomes essential if you have significant assets to protect.
Compare Quotes from Multiple Carriers
Obtain quotes from at least three different insurers before making a decision, comparing identical coverage levels across each quote. State Farm, Travelers, and Allstate all serve Connecticut, and their prices vary dramatically based on your specific home and location. Don’t assume the lowest price offers the best value; instead, compare what each policy actually covers. One insurer might include sewer backup coverage while another charges $75 extra for it. Another might apply a 5% wind deductible while a competitor uses a flat $1,000 deductible. These differences compound significantly over time.
Identify Discounts and Optimize Your Coverage
Ask each insurer about available discounts specific to your situation. Bundling auto and home insurance generates substantial savings with many carriers. If your home is newly renovated or less than five years old, mention this because many insurers offer new home discounts. Some carriers provide discounts for safety features like deadbolt locks, smoke detectors, and security systems. As an independent agency serving Connecticut since 1989, we compare multiple top carriers to identify which combination of coverage and discounts delivers the best value for your home and circumstances.
Final Thoughts
Your homeowners insurance coverage options should match your actual life, not a generic template. A young family with modest belongings and a newer home faces entirely different risks than an empty-nester with valuable collections in an older property near a flood zone. Life changes constantly-when you renovate your kitchen, add a pool, or purchase expensive jewelry, your coverage needs shift accordingly.
Annual policy reviews catch gaps before they become expensive problems. Many Connecticut homeowners set their coverage once and ignore it for years, only to discover during a claim that their circumstances have changed dramatically since they bought the policy. When your kids move out or you pay off your mortgage, you might adjust your liability limits or loss-of-use coverage downward to reflect your actual situation.
Working with a local agent transforms this process from overwhelming to straightforward. At Evaristo Insurance, we’ve served Connecticut families since 1989, and we compare multiple top carriers to identify which combination of coverage and pricing fits your home and budget. Contact us today to discuss your home’s specific characteristics and find the right protection for what matters most.
Disclaimer: This blog post is for general informational purposes only and does not represent actual coverage, policy terms, or legal requirements. Insurance details vary by individual and jurisdiction. Please consult a licensed insurance professional for advice specific to your situation.

