
Home Insurance Quotes CT: Shop Smart, Save More
Getting home insurance quotes CT is one of the smartest moves you can make as a Connecticut homeowner. Rates vary significantly between carriers, and the difference between quotes can easily reach hundreds of dollars annually.
At Evaristo Insurance, we’ve helped countless homeowners navigate this process and find coverage that actually fits their needs and budget. This guide walks you through everything you need to know to shop effectively and save more.
Why Connecticut Homeowners Need Multiple Quotes
Connecticut’s weather patterns create legitimate insurance challenges that directly affect your rates. The National Weather Service records detailed reports on thunderstorms and hail damage across the state. Winter ice storms regularly damage roofs and gutters, while coastal properties face hurricane risk. Your home’s exposure to these specific hazards shapes how insurers price your policy, and multiple quotes reveal which carriers weight these risks differently. Some insurers heavily penalize older roofs in Connecticut, while others focus more on proximity to trees or property age. A quote isn’t just a number-it’s a window into how that particular carrier evaluates your home.
Price differences between carriers are substantial and predictable
Insurance industry data shows that home insurance quotes for identical properties in Connecticut can vary by 40% or more between carriers. A homeowner with a 2,000 square-foot house built in 1995 might receive a quote of $1,200 annually from one insurer and $1,680 from another for the same coverage limits. These differences stem from each carrier’s loss history in Connecticut, their underwriting philosophy, and their appetite for specific risk types.
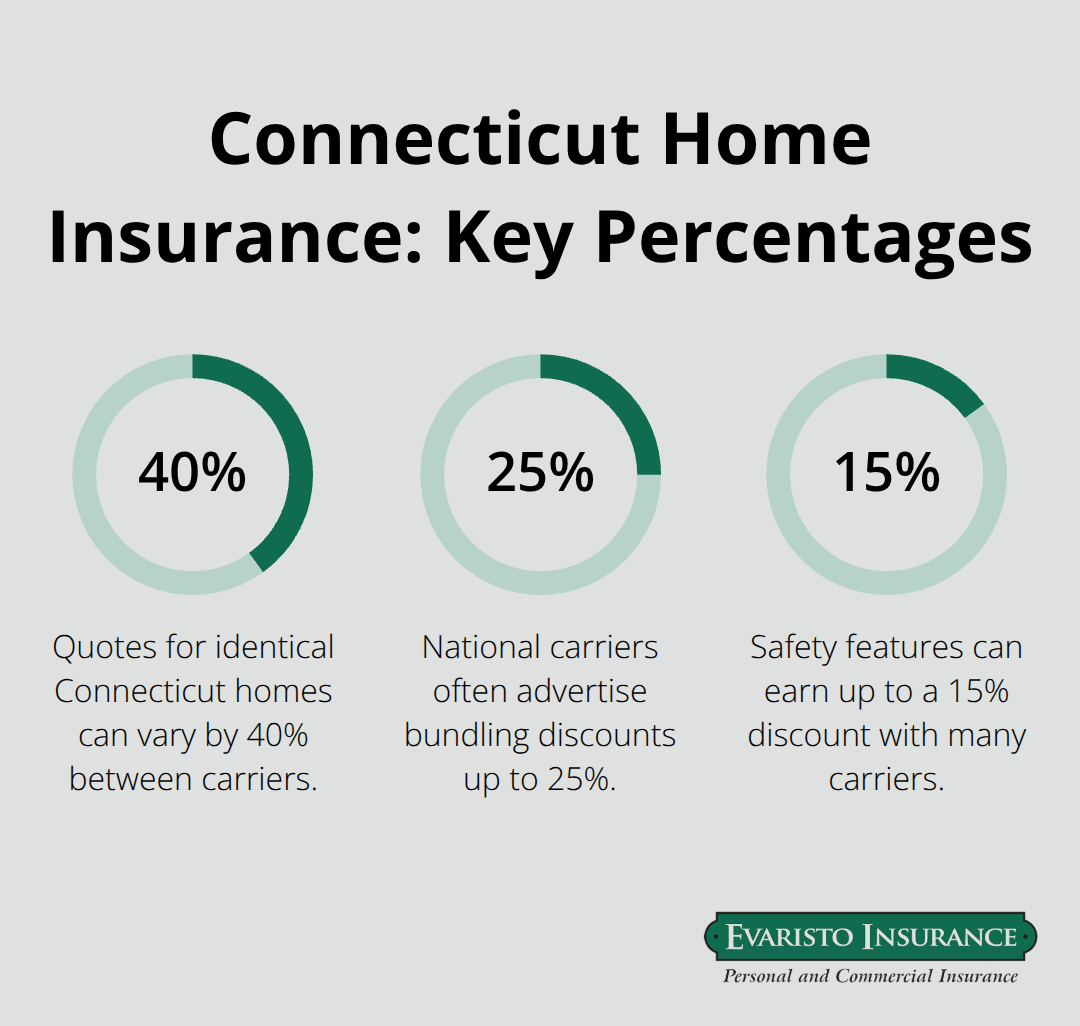
Some national carriers treat Connecticut as a high-risk state and price accordingly, while regional carriers and local specialists often bring more competitive rates because they understand the nuances of Connecticut properties. Three to five quotes take roughly 30 minutes of your time and can identify savings of $300 to $600 yearly-money that compounds over time.
Coverage options vary more than most homeowners realize
When you request quotes from different insurers, you’ll notice variations in what they actually cover and at what price point. One carrier might include water backup coverage as standard, while another charges $150 to $200 extra for it. Replacement cost coverage for personal belongings differs significantly in how much actual cash value they’ll pay versus full replacement. Deductible options range from $500 to $2,500, and each level produces a different premium. Some insurers bundle discounts aggressively if you add auto coverage, while others keep their pricing separate. Without reviewing multiple quotes side-by-side, you won’t know whether you’re overpaying for coverage you don’t need or missing protection that matters.
What carriers actually look for in Connecticut homes
Each insurer applies its own underwriting criteria to Connecticut properties, which explains why one company quotes significantly lower than another. Carriers examine your roof age, construction type, distance from fire hydrants, and claims history with intense scrutiny. Some focus heavily on whether your home has updated electrical systems and plumbing (factors that reduce fire and water damage risk). Others prioritize your credit score or the condition of your foundation. This variation means the cheapest quote might come from a carrier that doesn’t care about your roof age, while a more expensive quote could reflect an insurer that penalizes older homes heavily.
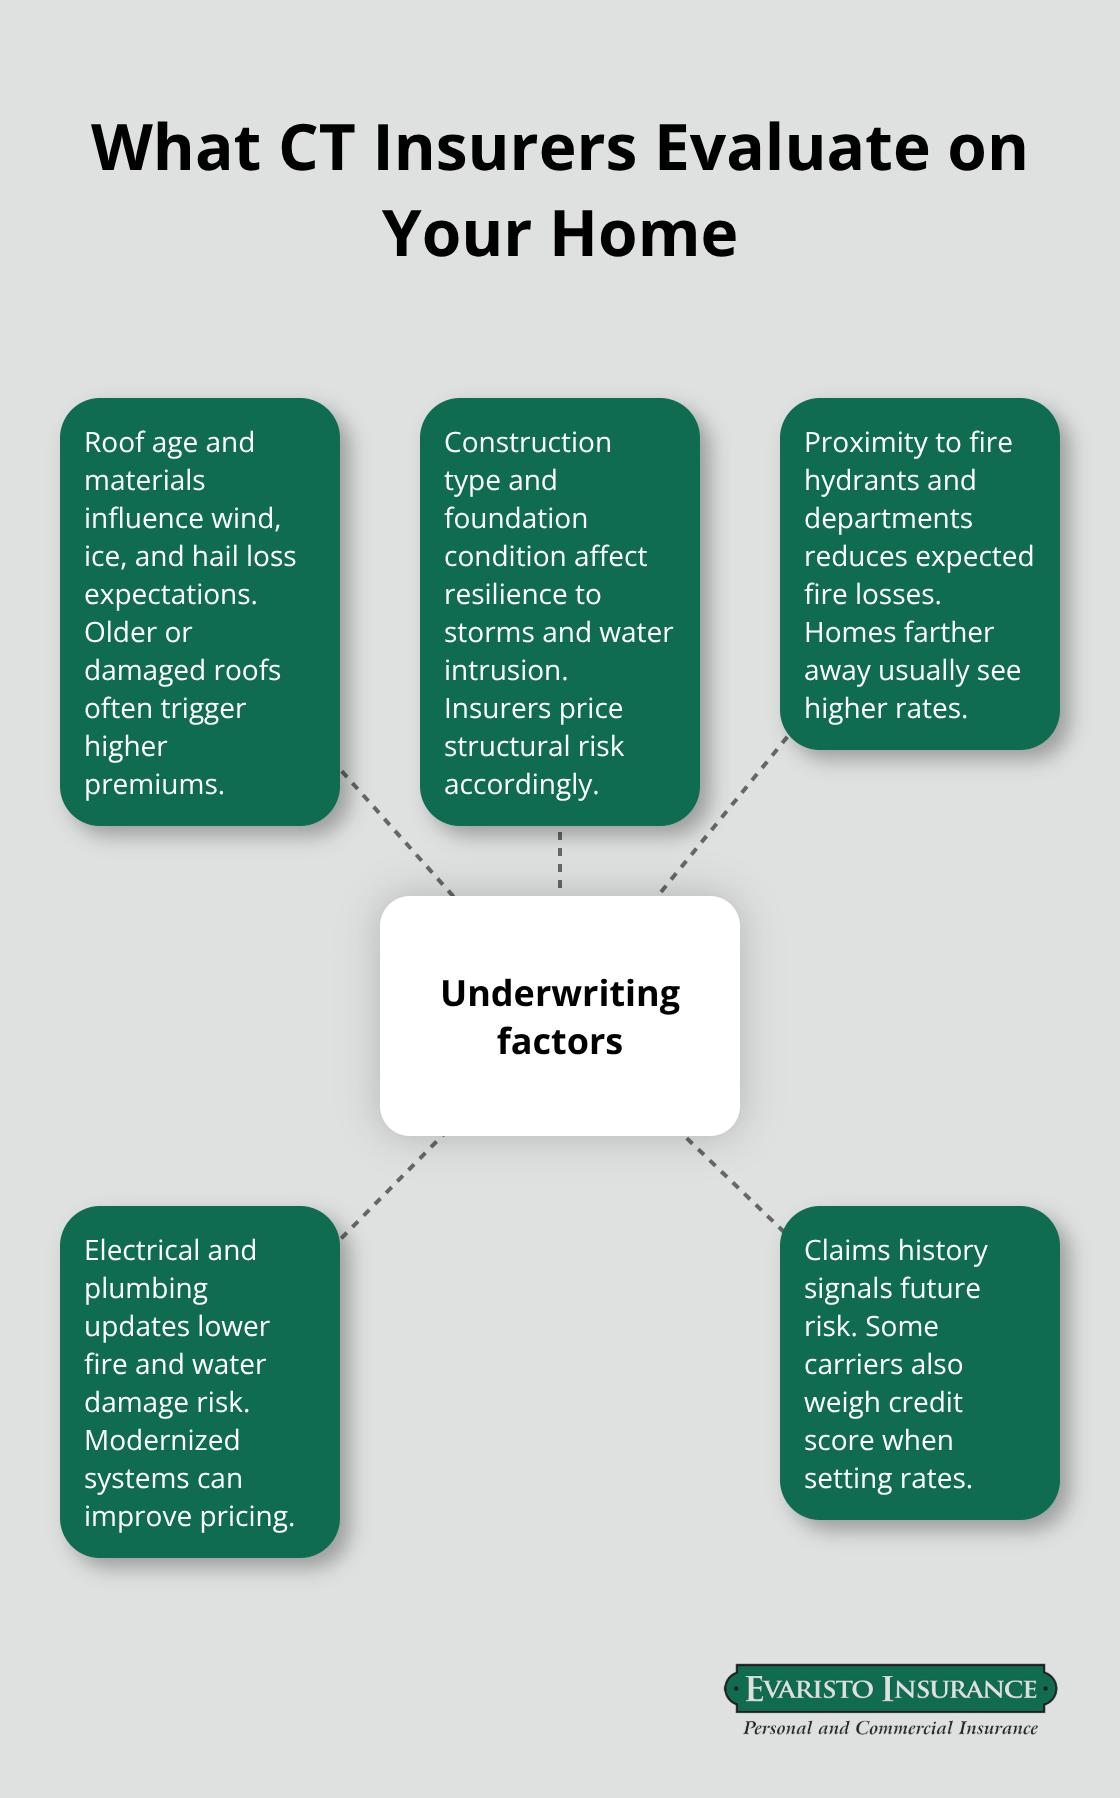
Understanding these differences helps you move forward with confidence about which carrier actually fits your specific property.
How to Get Accurate Home Insurance Quotes
Accurate quotes require you to provide insurers with specific details about your property. Vague information produces inaccurate numbers and wastes your time through endless follow-up conversations. The more precise you are upfront, the more reliable your quotes become-and the better you can compare them side-by-side.
Collect the details insurers require before requesting quotes
Start with your home’s construction specifics: the year built, square footage, number of stories, roof material, and when you last replaced the roof. Connecticut insurers scrutinize roof age intensely because ice storms regularly damage roofs across the state. Next, document your home’s protective features. Do you have deadbolt locks, a security system, smoke detectors, and carbon monoxide detectors?
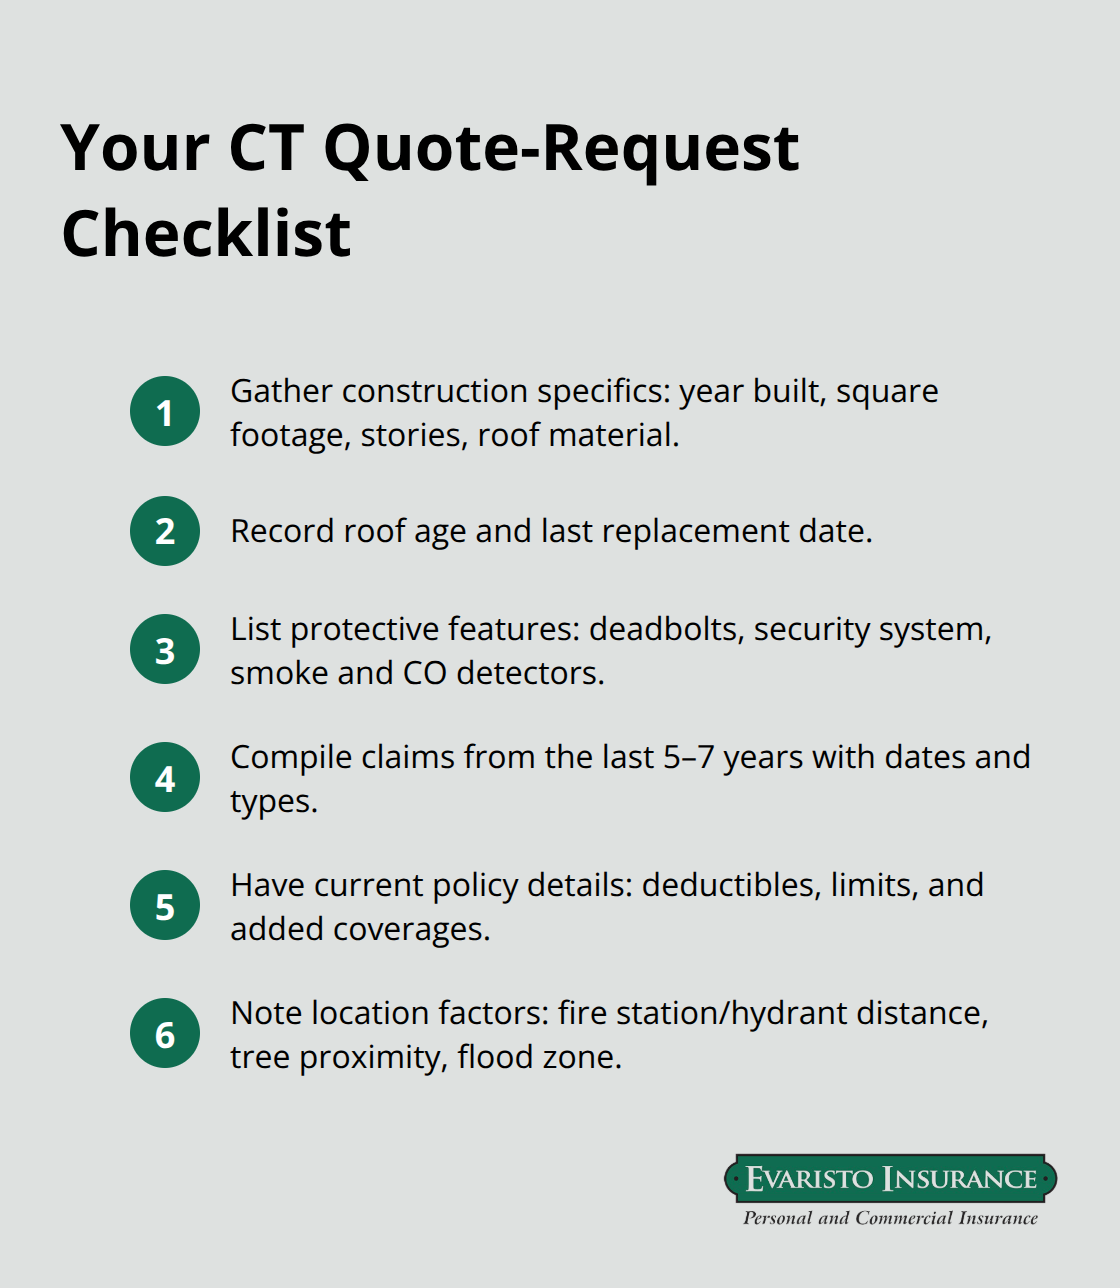
Carriers offer discounts ranging from 5% to 15% for these safety features, so omitting this information could cost you hundreds annually.
List any claims or losses from the past five to seven years, including water damage, theft, or fire incidents. Your claims history directly impacts pricing, and some carriers weight older claims more lightly than others. Have your current coverage details available if you’re switching insurers-your deductible, liability limits, and any additional coverages like water backup or scheduled personal property protection.
Finally, gather information about your property’s location: distance to the nearest fire department and fire hydrant, proximity to trees that could damage your roof, and whether you live in a flood zone. Properties within 5,000 feet of a fire station typically receive better rates than those farther away.
Ask agents these specific questions before accepting any quote
Press agents on what their quote includes and excludes rather than simply accepting the number. Ask whether the quote includes replacement cost coverage for your personal belongings or actual cash value, which pays significantly less. Request clarification on water damage coverage: does it include water backup from sewers and storm drains, or only water that enters through the roof? This distinction matters enormously in Connecticut, where basement flooding from heavy rains occurs regularly.
Ask about the deductible structure-some carriers offer percentage-based deductibles that increase your out-of-pocket cost for major losses. Inquire whether the quote includes coverage for detached structures like sheds or garages, and at what percentage of your dwelling coverage. Ask about discounts you might qualify for beyond the obvious ones: some carriers offer discounts for paying your bill in full annually rather than monthly, for completing a home safety course, or for bundling multiple policies.
Request the agent explain any exclusions or limitations specific to Connecticut properties. Some carriers exclude or limit coverage for older roofs, foundation issues, or properties in certain flood zones. Finally, ask what happens to your premium after the first year. Many carriers offer introductory rates that jump significantly at renewal, and knowing this upfront prevents surprises later.
Identify red flags when comparing quotes side-by-side
If one quote is dramatically lower than others-say 30% or 40% less-investigate why before celebrating the savings. The cheaper option might exclude water backup coverage, offer actual cash value instead of replacement cost, or carry a much higher deductible. Compare the liability limits across quotes because some carriers default to lower limits like 100/300/100 while others quote at 250/500/250. The liability section matters more than most homeowners realize: Connecticut courts have awarded judgments exceeding $1 million in homeowner liability cases, so inadequate limits create serious exposure.
Check whether quotes include the same personal property coverage limits and whether items like jewelry, art, or electronics require scheduled coverage at additional cost. Be suspicious if an agent cannot clearly explain why their quote differs from competitors. A legitimate explanation might be that they exclude water backup or use actual cash value for belongings, but vague answers suggest they don’t understand their own product.
If an agent pressures you to decide immediately or claims their rate is only available today, that’s a pressure tactic that indicates you should shop elsewhere. Finally, verify that all quotes use the same deductible and coverage limits-comparing a $500 deductible quote to a $2,500 deductible quote tells you nothing about actual pricing differences. Once you’ve narrowed your options based on coverage and price, the next step involves understanding which discounts and bundling strategies actually deliver the savings you’re looking for.
How to Actually Save Money on Connecticut Home Insurance
Bundling Auto and Home Policies Delivers Real Savings
Bundling your auto and home policies remains the single most effective way to lower your overall insurance costs, but the savings structure matters far more than most homeowners realize. National carriers like State Farm and Allstate typically advertise bundling discounts between 15% and 25%, but Connecticut insurers apply these discounts differently depending on which policies you combine and your risk profile. Some carriers calculate the discount on your home premium only, while others apply it to both auto and home. A homeowner paying $1,400 annually for home coverage and $900 for auto might save $315 to $525 yearly through bundling, but only if they choose a carrier that applies the discount generously to both policies.
The trap is accepting the first bundle quote without checking whether a competitor offers better bundling terms. Regional carriers and local independent agencies often structure bundling discounts more favorably than national carriers because they compete on service rather than brand recognition. Request quotes for both auto and home coverage from at least three different insurers, then compare the bundled total rather than individual policy prices. Some carriers won’t discount aggressively on home insurance if your auto history includes claims, so the bundling benefit varies significantly based on your specific situation. Additionally, timing matters when you bundle: switching your auto policy to coincide with your home renewal date allows you to lock in bundling discounts immediately rather than waiting months.
Focus on Discounts That Reduce Your Premium Substantially
Connecticut homeowners should target discounts that reduce your premium substantially rather than chasing every minor discount available. Safety feature discounts for smoke detectors, carbon monoxide detectors, and security systems typically range from 5% to 10%, which translates to $70 to $140 annually on a $1,400 premium. Paying your annual premium in full rather than monthly installments generates a 3% to 5% discount with most carriers, worth $42 to $70 yearly. Some insurers offer discounts for completing home safety courses through the American Red Cross, which costs around $30 to $50 but can deliver a 5% discount that pays for itself within the first year.
The discount that matters most varies by carrier, so your agent should identify which three to four discounts apply to your specific property and explain the total dollar impact. Homeowners often qualify for discounts they never claimed simply because their agent didn’t ask the right questions during the initial quote process. Your agent should walk through your property details and claims history to uncover every applicable discount rather than listing only the obvious ones.
Request Quotes During Off-Peak Times for Better Rates
Request quotes during off-peak times rather than during hurricane season or immediately after major storms hit Connecticut. Insurance agents handle higher volume during these periods and sometimes rush through quotes less carefully. Requesting quotes in April or May, when weather threats feel distant, typically produces more thorough underwriting and occasionally better rates because carriers have more capacity to compete aggressively for new business. This timing advantage applies whether you work with a national carrier or a local agency-agents simply have more time to evaluate your property thoroughly and present competitive options.
Final Thoughts
Shopping for home insurance quotes CT requires patience and attention to detail, but the financial payoff justifies the effort. You now understand why multiple quotes matter in Connecticut, what information insurers need to evaluate your property accurately, and which strategies actually reduce your premium. The difference between accepting the first quote and comparing three to five options typically ranges from $300 to $600 annually, which compounds significantly over the years you own your home.
Gather the property details outlined earlier, request quotes from at least three carriers, and compare them using the red flag checklist provided. Pay particular attention to coverage differences rather than fixating on price alone-a quote that costs $200 less but excludes water backup coverage or uses actual cash value for personal belongings might cost you thousands more when you file a claim. Once you’ve narrowed your options to two or three carriers, explore bundling opportunities and confirm which discounts apply to your specific situation.
Local expertise transforms quote shopping from a frustrating solo task into a partnership where someone with deep Connecticut experience guides your decisions. Evaristo Insurance compares multiple top carriers to deliver tailored protection and competitive pricing rather than steering you toward a single company’s products. Contact them to discuss your home insurance needs and receive personalized quotes that reflect your property’s unique characteristics.
Disclaimer: This blog post is for general informational purposes only and does not represent actual coverage, policy terms, or legal requirements. Insurance details vary by individual and jurisdiction. Please consult a licensed insurance professional for advice specific to your situation.

