
Independent Auto Insurance Agent: Compare Quotes and Save
Connecticut drivers overpay for auto insurance every single day. Most shop only with direct insurers and miss out on better rates and service that an independent auto insurance agent can provide.
At Evaristo Insurance, we’ve seen firsthand how working with an independent agent saves our neighbors hundreds of dollars annually. This guide shows you exactly how to compare quotes and find coverage that actually fits your needs.
Why Independent Agents Give You Better Rates
Direct Insurers Limit Your Options
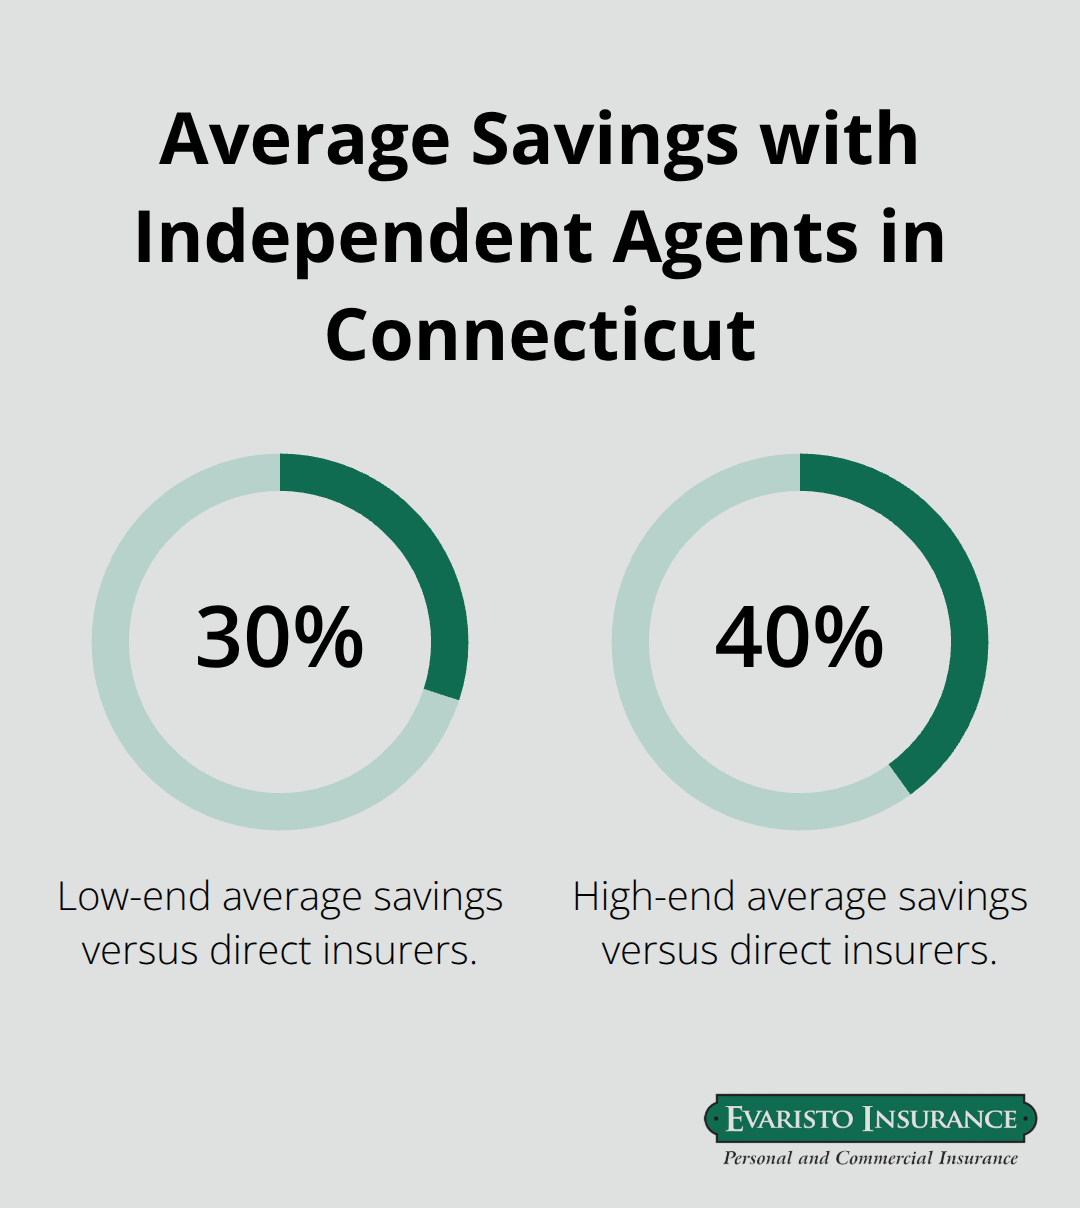
Direct insurers want you to think they’re your only option. They’re not. When you call State Farm, Geico, or Allstate directly, you shop with one company. That company sets the rates, controls the coverage options, and decides whether to fight for you when claims happen. An independent agent flips this completely. We represent multiple top carriers, which means we shop your coverage against 10, 15, or sometimes 20+ different insurance companies. Connecticut drivers who work with independent agents pay an average of 30-40% less than those locked into direct insurers.
How Independent Agents Find Better Rates
That savings doesn’t come from magic pricing-it comes from actual competition on your behalf. When you shop direct, one company’s rates limit you. When you work with an independent agent, we find the carrier that values your driving record, your vehicle, and your situation the best. A clean driving record might get you a 25% discount at one carrier but only 15% at another. We know these differences and apply them to your quote before you ever see a number.
Local Advocacy Makes the Real Difference
Independent agents provide something direct insurers simply cannot: local advocacy. We’re in Connecticut, we know Connecticut roads, and we handle claims differently than call centers in other states. When you file a claim with a direct insurer, a claims adjuster processes hundreds of cases weekly and has no relationship with you. When you file a claim with an independent agent, you work with someone local who knows you, knows your situation, and fights to get you fair treatment.
Annual Reviews Protect Your Coverage
We also review your coverage every year-not to upsell you, but to make sure you don’t pay for protection you don’t need while you avoid coverage gaps that could hurt you. Direct insurers send you a bill. Independent agents send you a policy review. That difference between a vendor relationship and a real partnership shows up most when you need to compare quotes and evaluate what coverage actually makes sense for your Connecticut driving situation.
How to Gather Information and Compare Quotes Effectively
Collect the Right Details Before Requesting Quotes
Accurate quotes require specific data points that insurance companies use to calculate rates. Start with your driving history: your license number, the date you obtained it, and any accidents or violations from the past three to five years. Insurance companies weight recent incidents heavily, so a speeding ticket from six months ago affects your rate differently than one from five years ago.
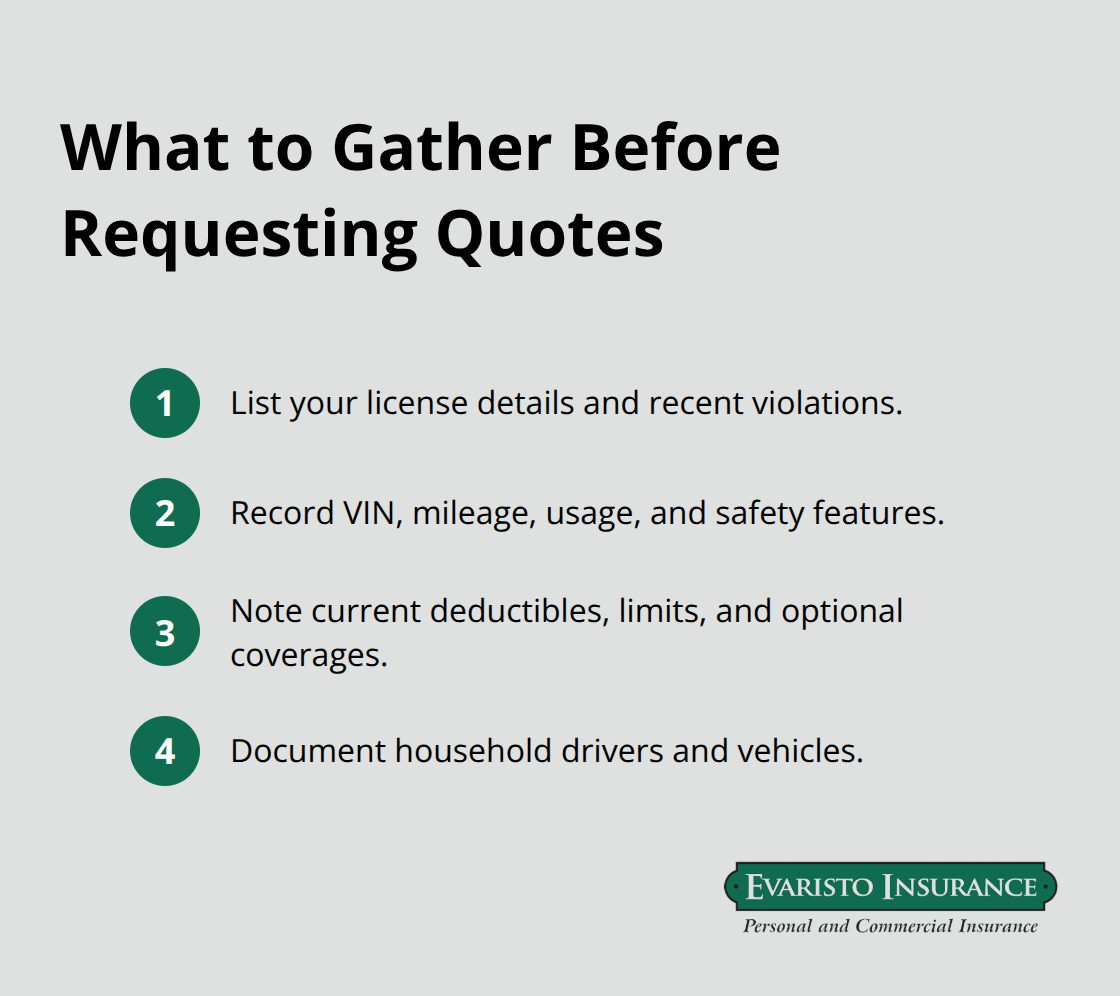
Next, gather your vehicle information including the VIN, current mileage, how you use the car (commute distance, annual miles driven), and any safety features like automatic braking or lane departure warning systems. Connecticut drivers with vehicles equipped with these technologies qualify for discounts ranging from 5% to 30% depending on the carrier. Your current coverage details matter too-know your existing deductibles, liability limits, and any optional coverages like uninsured motorist protection. Finally, document your household situation: whether you’re married, have teenage drivers, or maintain multiple vehicles. Each factor influences rates, and incomplete information means quotes won’t match reality when you’re ready to purchase.
Request Quotes from Multiple Carriers to Reveal Price Differences
Don’t settle for quotes from two or three companies. Independent agents access 15 to 20+ carriers simultaneously, which reveals how dramatically rates vary for identical coverage. A Connecticut driver with a clean record might pay $1,200 annually with one carrier but $900 with another for the same policy. That $300 difference compounds to $3,000 over a decade. When you request quotes, provide identical information to each carrier so comparisons remain valid. Many drivers accept the first quote without shopping further, assuming all insurers price similarly. They don’t. Your driving record, vehicle type, and zip code influence rates differently across carriers. Coastal Connecticut addresses typically pay more than inland locations due to accident frequency data. A Honda Civic costs less to insure than a Dodge Charger even with identical drivers, reflecting actual claims data by model. Request quotes online, by phone, or through an independent agent-each method yields different results because some carriers offer better rates through specific channels.
Look Beyond Price When Evaluating Coverage Options
Lowest price means nothing if your coverage leaves you exposed. Connecticut requires minimum liability coverage of 20/40/10 (20,000 bodily injury per person, 40,000 per accident, 10,000 property damage), but this minimum protects only the other driver, not you. A serious accident in Connecticut easily exceeds these limits-medical bills, vehicle damage, and lost wages accumulate quickly. Most financial advisors recommend 100/300/100 coverage for Connecticut drivers, which costs roughly 15% to 20% more than state minimums but provides realistic protection. Collision and comprehensive coverage become critical decisions.
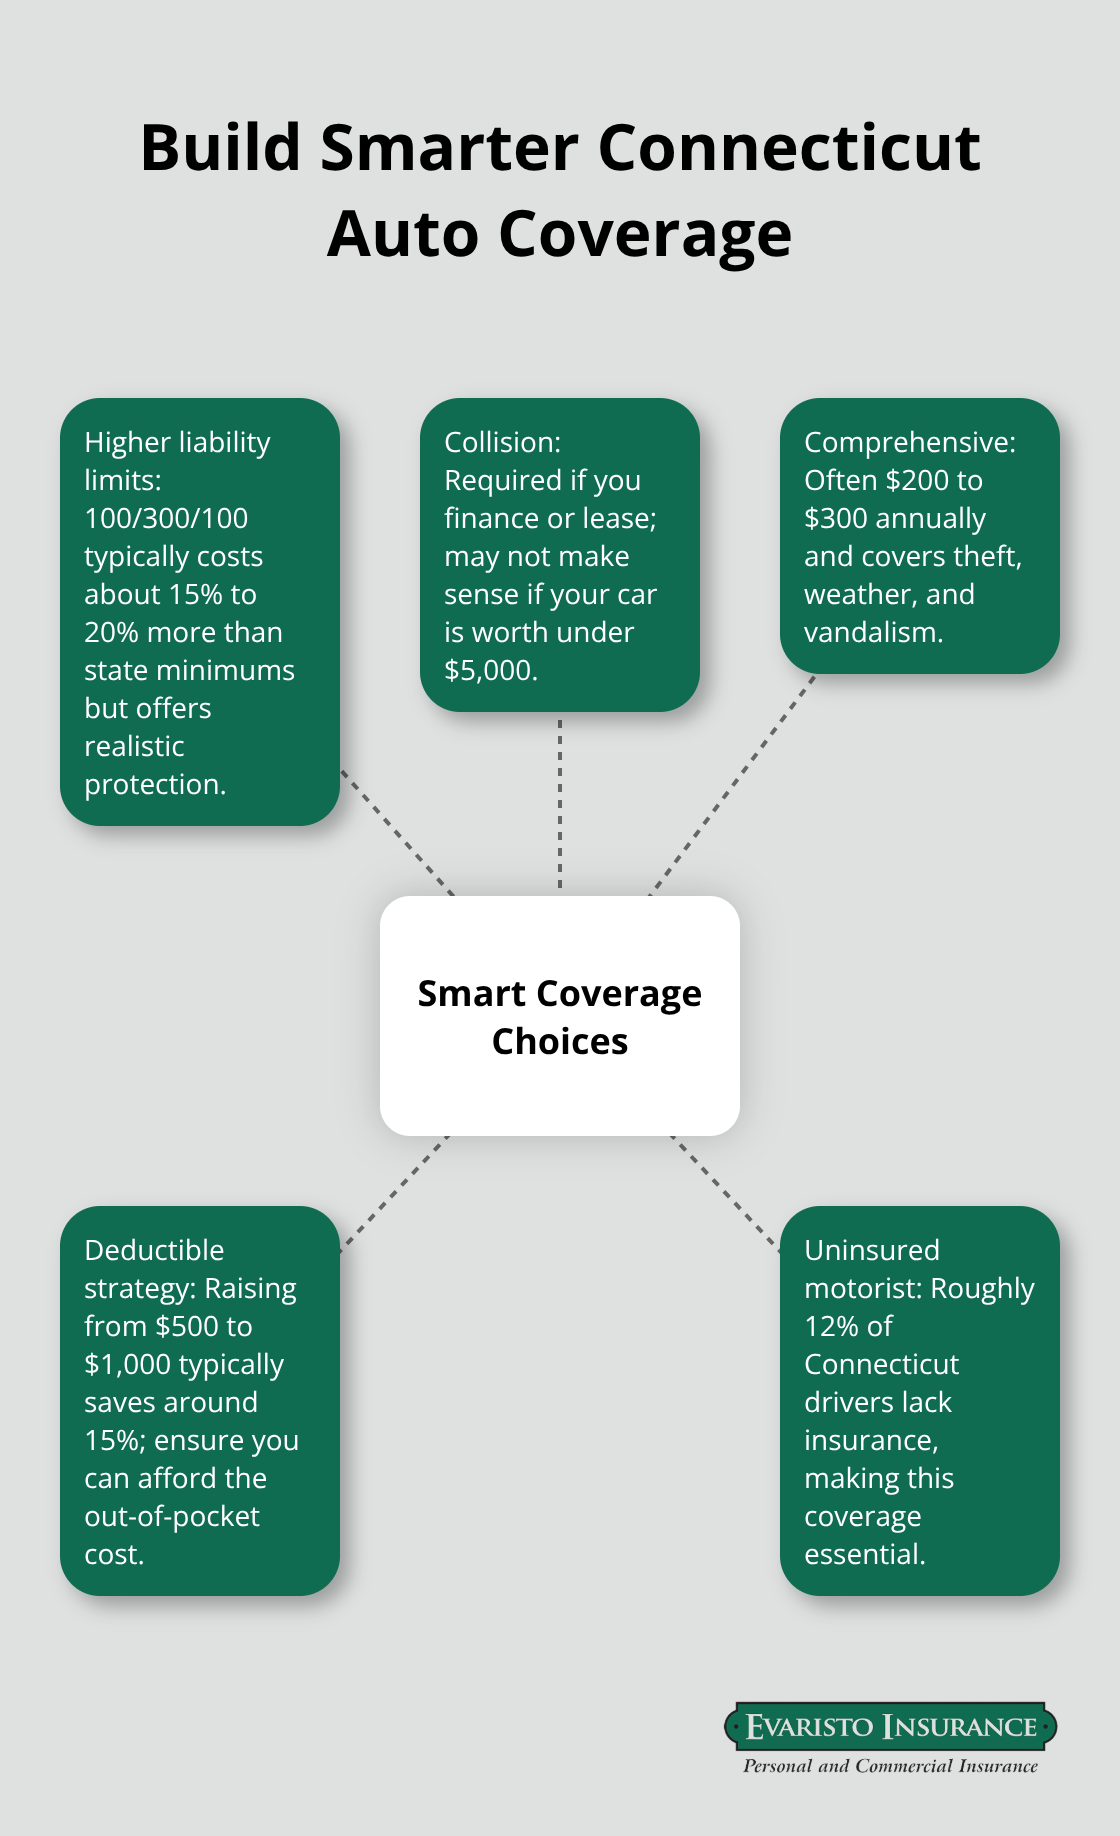
If you financed or lease your vehicle, your lender requires collision coverage. If you own the car outright and it’s worth less than $5,000, collision might not make financial sense. However, comprehensive coverage (theft, weather, vandalism) costs $200 to $300 annually for most Connecticut drivers and covers incidents you can’t control. Raise your deductible from $500 to $1,000 and you typically save 15% on premiums, but only if you can afford that out-of-pocket amount during a claim. Review uninsured motorist coverage, which protects you if an uninsured driver causes the accident. Connecticut sees roughly 12% of drivers operating without insurance, making this coverage genuinely valuable rather than optional.
Work with an Independent Agent to Simplify the Process
Shopping multiple carriers individually takes hours and produces incomplete comparisons. An independent agent handles this work for you, accessing carriers simultaneously and presenting side-by-side quotes with identical coverage options. This approach eliminates the tedious process of contacting multiple insurers while guaranteeing you see competitive options. An agent also explains how coverage differences affect your actual protection, not just your premium. When you move forward to selecting a policy, you’ll understand exactly what you’re purchasing and why that coverage makes sense for your Connecticut driving situation.
Cost-Saving Strategies for Connecticut Auto Insurance
Bundle Home and Auto Policies for Immediate Savings
Bundling home and auto policies delivers the fastest savings for Connecticut drivers, and the numbers prove it. Connecticut residents routinely see discounts of 10% to 25% when they consolidate both policies under a single insurer, which translates to meaningful annual savings on a typical Connecticut home and auto package. An independent agent accesses multiple carriers simultaneously, revealing which company offers the best bundled rate for your specific situation rather than forcing you to contact each insurer individually.
The catch: you need to compare bundled quotes across multiple carriers because the discount percentage varies significantly. Some insurers offer lower bundling discounts while competitors offer higher percentages for identical coverage. Shopping multiple insurers ensures you find the best rate rather than accepting the first quote you receive.
Leverage Safety Features and Good Driver Discounts
Safety features integrated into your vehicle reduce premiums substantially. Connecticut drivers with automatic emergency braking, lane departure warnings, or adaptive headlights qualify for discounts between 5% and 30% depending on the carrier. If your vehicle includes multiple safety technologies, some insurers stack these discounts, potentially reducing your premium by 40% or more.
Good driver discounts apply when you maintain a clean record for three to five years without accidents or violations. These discounts typically range from 10% to 30%, but the specific percentage depends on the carrier’s underwriting standards. A driver with no incidents for five years might receive a 30% discount at one carrier but only 15% at another-this is why shopping multiple insurers matters.
Review Coverage Annually to Eliminate Overpaying
Annual policy reviews prevent Connecticut drivers from overpaying on coverage they no longer need while identifying gaps that could expose them to serious financial risk. Most drivers pay the same premium year after year without questioning whether their coverage matches their current situation.
Your needs change: a vehicle depreciates in value, your commute distance shifts, or your driving habits evolve. If your car drops below $5,000 in value, collision coverage might cost more annually than the vehicle’s worth, making it financially illogical to maintain. Conversely, if you added a teenage driver to your household or increased your commute distance, your current coverage limits might prove insufficient during a claim.
Connecticut drivers should review coverage every 12 months, comparing current rates against what new quotes reveal about market pricing. A policy review identifies whether your deductible still makes sense for your financial situation-raising it from $500 to $1,000 saves approximately 15% on collision and comprehensive premiums, but only if you can afford that deductible during an actual claim.
Review your liability limits too. Connecticut’s minimum requirement of 20/40/10 protects only the other driver, leaving you exposed if you cause a serious accident. Increasing to 100/300/100 costs roughly 15% to 20% more but aligns with actual accident costs in Connecticut. These reviews take time when you shop alone, but an independent agent completes this analysis annually without requiring you to contact multiple insurers or spend hours comparing options.
Final Thoughts
An independent auto insurance agent represents your interests, not a single company’s bottom line. You access multiple carriers simultaneously, compare actual competitive rates, and receive personalized service from someone who knows Connecticut’s roads and insurance landscape. Direct insurers can’t match this approach-they’re designed to sell you their coverage at their price, period.
Smart comparison shopping reveals savings that most Connecticut drivers never find. The 30-40% average savings that independent agent customers enjoy comes from requesting quotes across multiple carriers, evaluating coverage options beyond price alone, and understanding how bundling, safety features, and good driver discounts apply to your specific situation. Annual policy reviews prevent you from overpaying on unnecessary coverage while identifying gaps that could expose you financially.
At Evaristo Insurance, we’ve served Connecticut families and businesses since 1989 as a second-generation, family-owned independent agency. We compare multiple top carriers to deliver tailored protection and competitive pricing while providing the hands-on customer advocacy that direct insurers simply cannot offer. Contact Evaristo Insurance to request quotes from our local offices in Ellington and West Hartford and experience the difference that genuine local expertise makes.
Disclaimer: This blog post is for general informational purposes only and does not represent actual coverage, policy terms, or legal requirements. Insurance details vary by individual and jurisdiction. Please consult a licensed insurance professional for advice specific to your situation.

