
Average Auto Premium Connecticut: What Averages Mean for Your Budget
Connecticut drivers pay widely different premiums depending on where they live, what they drive, and their history behind the wheel. Understanding the average auto premium in Connecticut helps you set a realistic budget and spot when you’re overpaying.
At Evaristo Insurance, we’ve helped countless Connecticut residents find coverage that fits their finances. This guide breaks down what influences your rates and shows you concrete ways to lower them.
What Really Drives Your Connecticut Auto Insurance Rate
Your Driving Record Sets the Foundation
Your driving record is the single biggest factor insurers examine when pricing your policy, and Connecticut carriers take violations seriously. A speeding ticket raises your premium by 10 to 15 percent, while an at-fault accident typically increases rates by 25 to 40 percent depending on severity and your carrier. Some insurers in Connecticut offer accident forgiveness programs, but these usually apply only after three to five years of clean driving, so your history matters immediately.
Vehicle Type and Safety Features Impact Your Cost
The type of vehicle you drive affects pricing substantially because insurers analyze real crash data and repair costs. A Honda Civic costs significantly less to insure than a Dodge Charger, not because of perception but because collision repairs for performance vehicles run higher and replacement parts cost more. Automatic emergency braking and blind-spot monitoring lower premiums with many carriers, so checking the Insurance Institute for Highway Safety ratings helps you make a financially smarter choice when shopping for a car.
Age and Experience Create Significant Premium Gaps
Your age and driving experience create stark premium differences across Connecticut. Drivers under 25 pay roughly 50 to 100 percent more than drivers aged 30 to 59, simply because statistical data shows younger drivers file more claims. A 19-year-old insuring a vehicle in Connecticut typically pays $2,500 to $3,500 annually for basic coverage, while a 45-year-old pays $1,000 to $1,500 for identical protection.
Location and Commute Distance Matter More Than You Think
Where you live in Connecticut matters more than most drivers realize because urban areas like Hartford and New Haven have higher claim frequencies than rural towns like Litchfield or Norfolk. Your commute distance directly influences your rate because more miles driven means higher accident exposure. A commuter driving 45 miles daily pays more than someone driving five miles to work, though this varies by carrier.
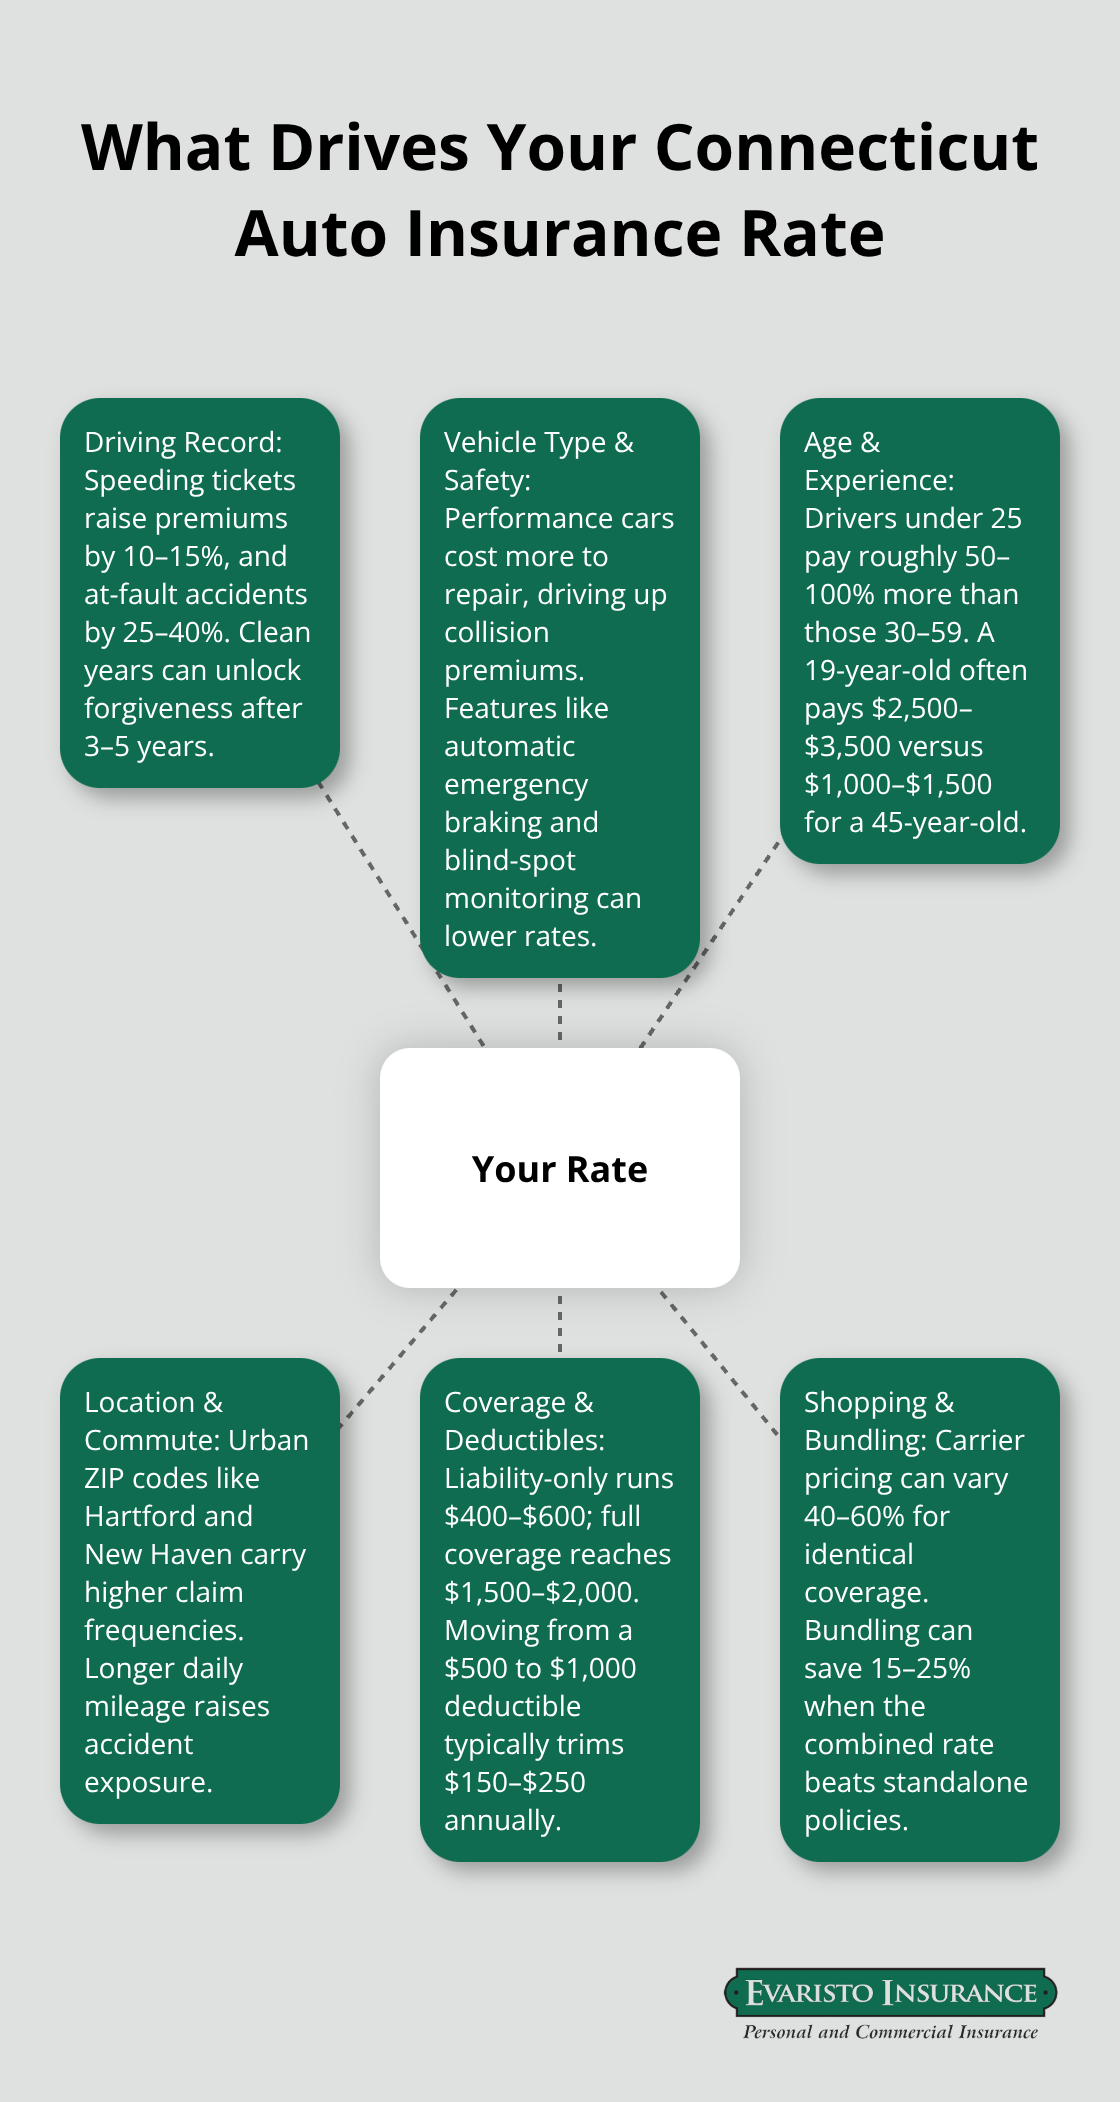
These factors combine to create your individual rate, and understanding which ones apply to your situation helps you identify where you actually have control and where market forces set the price floor. Once you know what influences your premium, you can explore the actual costs across different Connecticut regions and coverage types.
Average Auto Insurance Costs Across Connecticut
Urban Premiums Run Significantly Higher Than Rural Areas
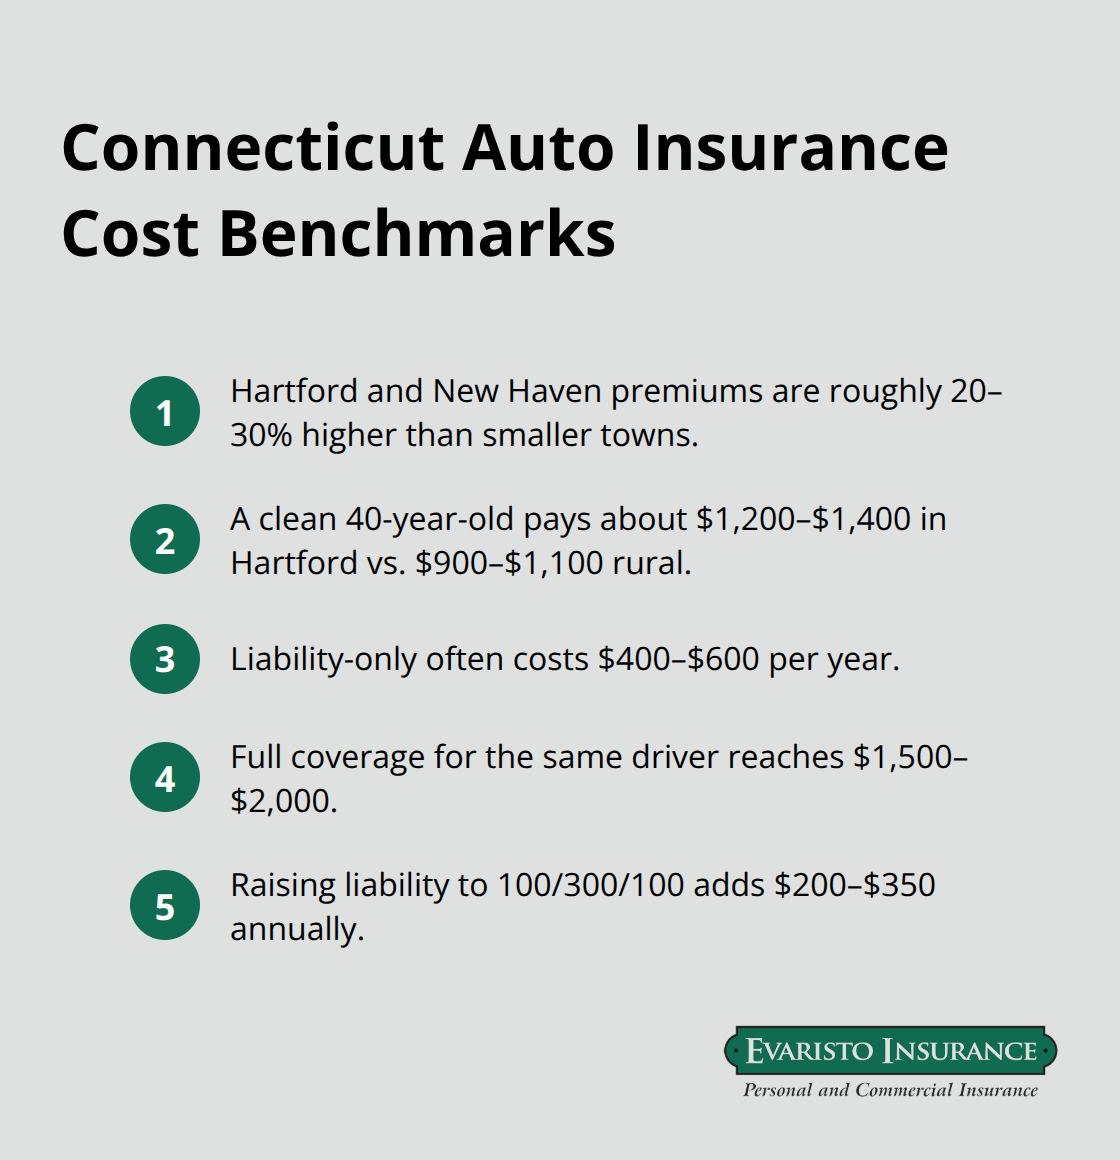
Hartford and New Haven drivers pay premiums roughly 20 to 30 percent higher than those in smaller towns like Avon or Glastonbury, primarily because urban areas generate more claims and theft reports. A 40-year-old driver with a clean record pays approximately $1,200 to $1,400 annually in Hartford for liability and collision coverage, while the same driver in a rural area pays $900 to $1,100. Insurers price based on historical claim data specific to each ZIP code, and urban density directly correlates with accident frequency. The difference compounds when you add comprehensive coverage, which protects against theft and weather damage that occurs more frequently in denser areas.
Coverage Type Selection Dramatically Shifts Your Total Cost
Liability-only policies run $400 to $600 yearly while full coverage including collision and comprehensive reaches $1,500 to $2,000 for the same driver. Most Connecticut drivers carry liability limits of 25/50/25, meaning $25,000 for individual bodily injury, $50,000 for total injuries per accident, and $25,000 for property damage. Higher limits provide substantially better asset protection when you cause a serious accident. Increasing liability to 100/300/100 adds $200 to $350 annually but shields your finances far more effectively than minimum coverage.
Your Deductible Choice Creates Direct Control Over Monthly Payments
Your deductible choice requires honest assessment of your emergency fund rather than chasing the lowest rate. Choosing a $500 deductible versus $1,000 typically reduces your annual premium by $150 to $250, but only if you can actually cover that $500 out of pocket after an accident. This decision matters because it balances immediate affordability with realistic financial protection.
Connecticut Rates Run Higher Than National Averages
Connecticut rates run 8 to 12 percent higher than the national average, primarily because the state has higher medical costs and more congested driving conditions than most regions. This premium difference means shopping multiple carriers matters intensely because rate variation among Connecticut insurers reaches 40 to 60 percent for identical coverage. A driver paying $1,600 with one carrier might pay $1,000 with another, making comparison shopping worth your time. Taking time to compare quotes from at least three carriers typically saves $300 to $500 annually, making this effort worth roughly $25 to $40 per hour of your time spent shopping.
How to Actually Lower Your Auto Insurance Costs
Bundle Policies Strategically, Not Automatically
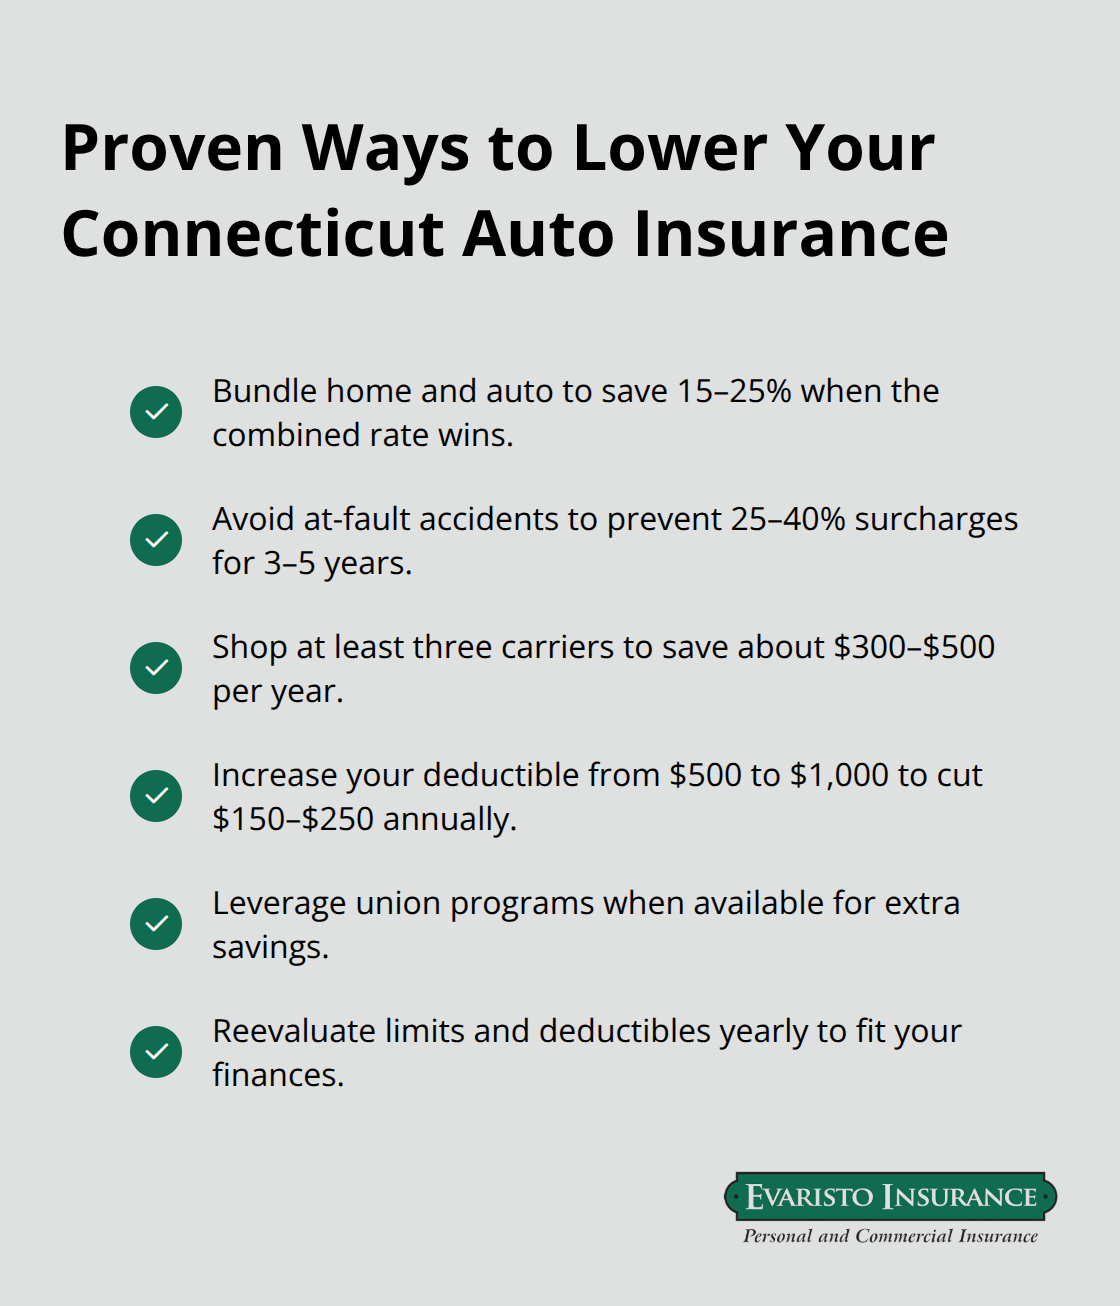
Bundling home and auto policies with the same carrier typically saves 15 to 25 percent on your combined premiums. This discount works because insurers reward customer loyalty and reduce their acquisition costs when you consolidate coverage. However, bundling only makes financial sense if the combined rate beats what you’d pay shopping each policy separately, so always compare the bundled quote against standalone quotes from other carriers before committing. Request itemized quotes showing your bundled discount explicitly so you see exactly what discount you’re actually receiving rather than accepting the carrier’s word for it. Sometimes splitting policies between two carriers produces better overall savings than accepting a bundled package from a single insurer.
Maintain a Clean Driving Record for Maximum Leverage
Your driving record produces the single largest savings opportunity available to you, yet most drivers underestimate this leverage. Each year without an accident or violation keeps your rates stable or potentially lowers them through loyalty discounts, while one at-fault accident increases your premium by 25 to 40 percent for three to five years. This means avoiding one accident saves you $1,500 to $3,000 over that period compared to paying elevated rates after a collision claim. Your history directly determines whether insurers view you as low-risk or high-risk, and that classification affects every quote you receive.
Shop Multiple Carriers to Expose Rate Variations
Connecticut insurers vary their pricing by 40 to 60 percent for identical coverage, meaning you could pay $1,200 with one carrier and $1,800 with another for the same 40-year-old driver with the same clean record. Obtain quotes from at least three different carriers because the lowest quote typically saves $300 to $500 annually compared to your current rate, making the 30 minutes spent shopping worth approximately $10 to $15 per minute. Union members can access special savings on auto insurance through dedicated programs. Rate variation exists because each carrier weights factors like age, location, and vehicle type differently, so your profile fits some carriers’ pricing models better than others.
Adjust Coverage Annually to Match Your Finances
Review your coverage limits and deductibles annually because your financial situation changes, your vehicle ages, and carrier rates shift yearly. If your emergency fund grew substantially, raising your deductible from $500 to $1,000 reduces your premium by $150 to $250 annually, while decreasing liability limits when your assets shrink protects your finances more appropriately than overpaying for unnecessary coverage. Your deductible choice requires honest assessment of your emergency fund rather than chasing the lowest rate. This annual review prevents you from carrying outdated coverage that no longer matches your actual needs and financial capacity.
Final Thoughts
Understanding the average auto premium Connecticut shows you what others pay, not what you must pay. Rate variation among Connecticut insurers reaches 40 to 60 percent for identical coverage, meaning your effort to compare quotes directly translates to hundreds of dollars in annual savings. Shopping three carriers typically saves $300 to $500 annually, while bundling policies saves 15 to 25 percent and adjusting your deductible based on your emergency fund creates immediate monthly relief.
Local expertise matters when navigating Connecticut’s insurance landscape because an agent familiar with your state’s specific conditions, carrier options, and regional pricing patterns identifies savings opportunities you’d miss shopping alone online. Evaristo Insurance has served Connecticut since 1989 as a family-owned independent agency with offices in Ellington and West Hartford, comparing multiple top carriers to deliver tailored protection and competitive pricing. Their hands-on approach means you receive personalized guidance based on your actual situation rather than generic online quotes.
Your next step is straightforward: gather quotes from at least three carriers, review your current coverage against your actual financial needs, and take action on the savings opportunities this guide identified. The strategies outlined here produce measurable results that Connecticut drivers implement successfully every year. Contact Evaristo Insurance to explore how their local expertise can help you find competitive rates that fit your budget.
Disclaimer: This blog post is for general informational purposes only and does not represent actual coverage, policy terms, or legal requirements. Insurance details vary by individual and jurisdiction. Please consult a licensed insurance professional for advice specific to your situation.

