
Home Insurance Discounts Revealed: How to Save On Your Premiums
Home insurance doesn’t have to drain your budget. Connecticut homeowners leave thousands of dollars on the table every year by missing out on available discounts.
At Evaristo Insurance, we’ve helped countless local families uncover savings they didn’t know existed. This guide reveals the discounts you qualify for and shows you exactly how to claim them.
The Discounts That Actually Matter
Bundling Policies Saves Thousands
Bundling your home and auto policies with the same insurer cuts your premiums significantly. According to Liberty Mutual, customers who bundle home and auto policies save over $950 annually. If you’re paying separate bills for home and auto, you’re overpaying. Many Connecticut homeowners don’t realize their current insurer may offer bundling discounts they haven’t activated. Start by asking your agent exactly what discount applies to your bundled policies and whether that percentage matches what competitors offer. As a second-generation, family-owned independent agency, Evaristo Insurance compares multiple top carriers to find you the best bundled rates in Connecticut-sometimes beating what you’d pay with a single large national company.
Safety Features Lower Your Monthly Costs
Your safety features lower what you pay each month. Dead-bolt locks, smoke detectors, fire extinguishers, sprinkler systems, and monitored security systems all reduce your risk profile in the eyes of insurers. Newer smart home devices like water leak sensors add real value because they prevent costly damage before it happens. If you’ve installed storm shutters, that’s another discount trigger-especially important along Connecticut’s coast where wind damage risk is highest. The installation cost pays for itself through premium reductions over just a few years.
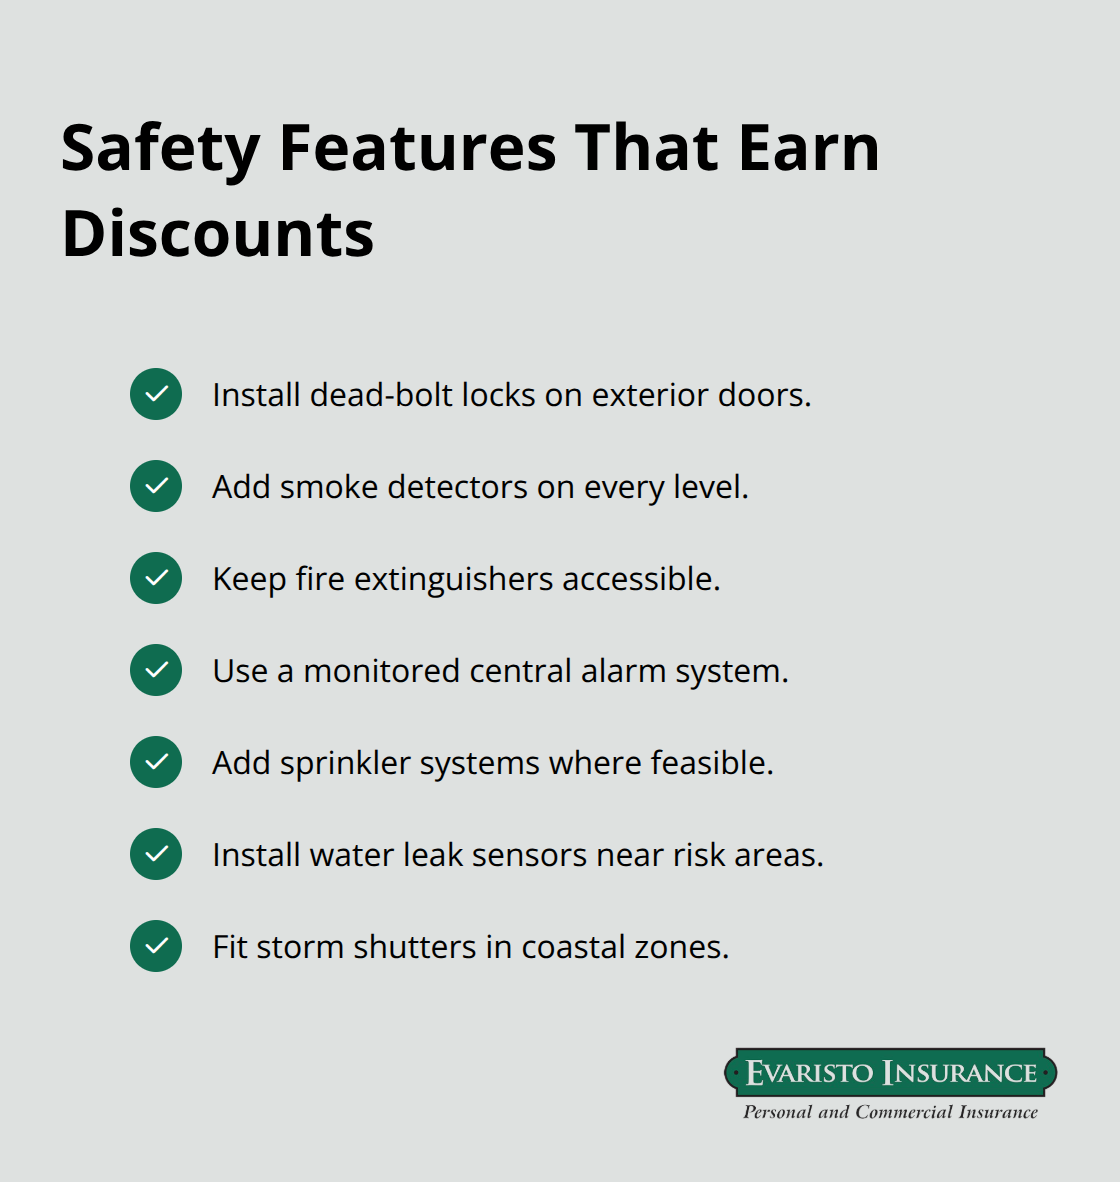
Homes with central alarm systems monitored by professionals typically receive larger discounts than those with basic smoke detectors alone.
Claims History Shapes Your Rate
Your claims history directly impacts your rate going forward. Homeowners who haven’t filed a claim in five years qualify for claims-free discounts with most carriers. Connecticut’s average annual home insurance cost sits around $1,575, according to NerdWallet data, but that number shifts dramatically based on your claims record. A single claim can raise your premium by 10 to 25 percent, depending on the insurer and claim severity. This creates a real incentive to handle minor issues out-of-pocket rather than filing small claims. If you’ve maintained a clean record, make sure your insurer knows it-some carriers don’t automatically apply this discount.
Home Age and Renovations Matter
Your home’s age affects pricing substantially. Newer homes cost less to insure because they have modern systems and less wear and tear. If you’ve completed recent renovations or upgrades, inform your agent immediately. Some carriers offer new or renovated home discounts that many homeowners miss simply because they don’t mention the work they’ve done. The key across all these discounts is verification: get written confirmation of every discount applied to your policy and check your renewal statement to confirm nothing disappeared. Once you understand what discounts you qualify for, the next step involves taking action to maximize those savings even further.
How to Lower Your Premiums Without Sacrificing Protection
Raise Your Deductible Strategically
Raising your deductible from $500 to $1,000 can reduce your annual premium by 20% to 40%, depending on your carrier and location. The math is straightforward: if you raise your deductible by $500 and save on your premium, you break even within a few years. After that, you pocket the difference.
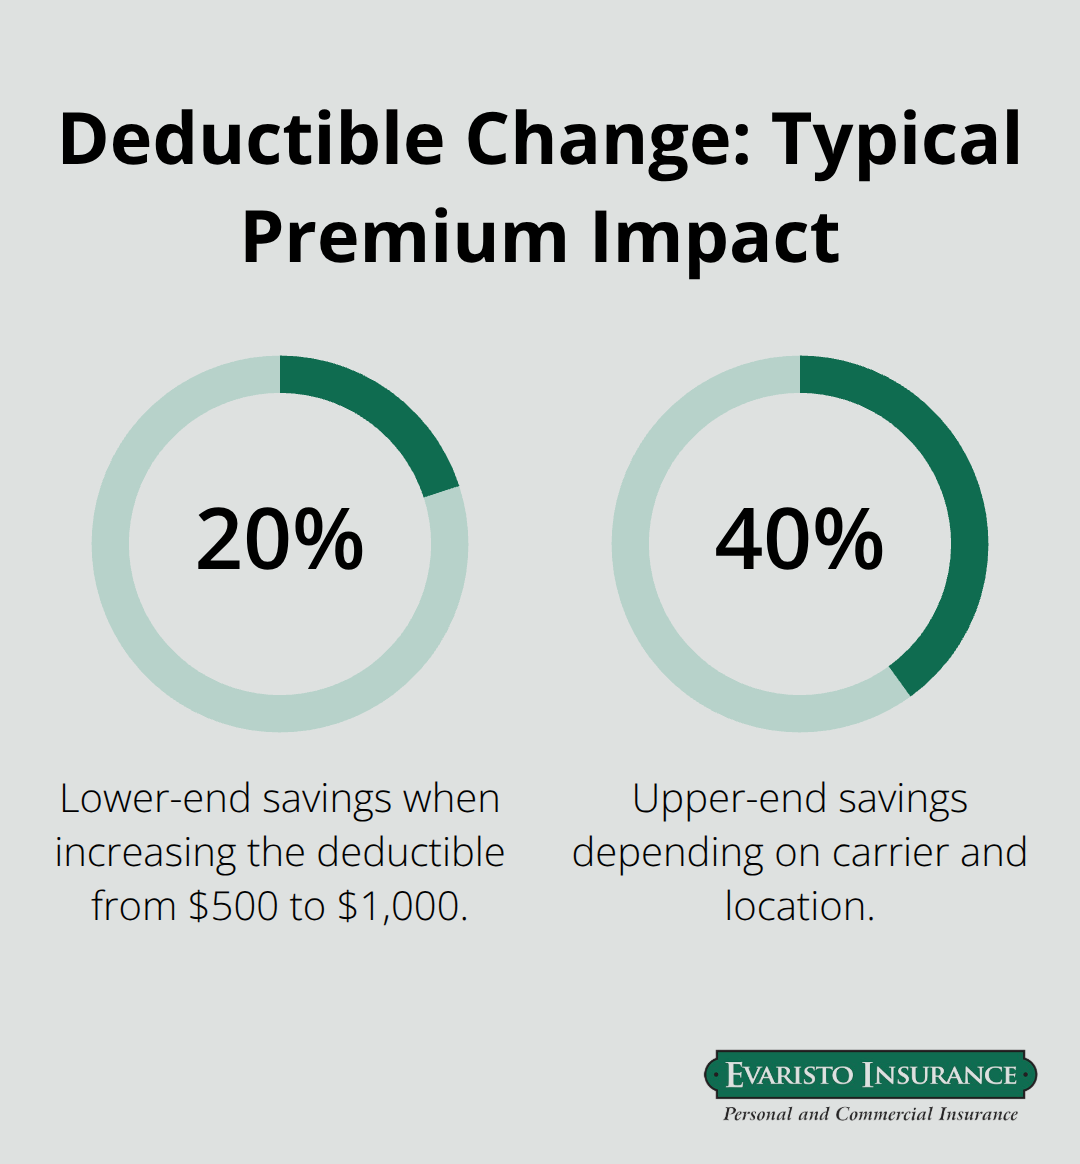
The catch is real-you must have $1,000 available when a loss occurs. Too many Connecticut homeowners choose deductibles they cannot actually afford, which defeats the purpose. Set your deductible at a level that will not force you to skip the repair if something happens.
Install Protection Systems That Insurers Reward
Once you settle on the right deductible, prevention becomes your next lever. Installing monitored security systems, water leak sensors, and smoke detectors signals to insurers that you take protection seriously. Homes with central alarm systems monitored by professionals receive substantially larger discounts than those with basic detectors.
If you live near Connecticut’s coast, storm shutters become essential-they prevent wind damage and qualify you for meaningful discounts that offset installation costs within a few years. Smart home devices like water sensors are becoming standard in newer homes, and insurers increasingly reward their installation because they catch problems before they become expensive claims.
Maintain Consistent Payment History
Your payment history and credit profile influence rates more than most homeowners realize. Insurers use payment patterns as a proxy for risk-homeowners who pay on time consistently pose lower risk than those with late payments or lapses in coverage. Some carriers now offer discounts for setting up automatic payments, which removes the possibility of accidental lapses.
Gaps in coverage can trigger surcharges that stick around for years. Local independent agents track policy renewals, coordinate timing with other carriers, and help ensure no gaps occur. Staying with the same carrier for extended periods also rewards customer loyalty with additional discounts at renewal.
Verify Discounts Actually Appear on Your Bill
The strategy is not to chase every discount-it is to identify the three or four that matter most for your situation, implement them deliberately, and then verify they actually appear on your renewal statement. Many discounts simply disappear at renewal if you do not actively confirm their presence.
Get written confirmation of every discount applied to your policy and check your renewal statement to confirm nothing vanished. This verification step separates homeowners who save money from those who think they are saving but are not. Once you have locked in your deductible, installed your protection systems, and confirmed your discounts, the next step involves finding the right carrier at the right price-something that requires comparing multiple options across Connecticut’s insurance market.
Finding the Right Carrier at the Right Price
Compare Quotes Across Multiple Carriers
Shopping for home insurance in Connecticut requires comparing quotes across multiple carriers because premium variations are substantial. The Connecticut Insurance Department confirms that premiums vary widely between insurers, making comparison essential to get the best value. A homeowner in Fairfield County might pay $3,188 annually with one carrier while another quotes $2,400 for identical coverage-that’s a $788 difference your budget cannot ignore. Online quote tools work quickly, but they only show you one carrier at a time.
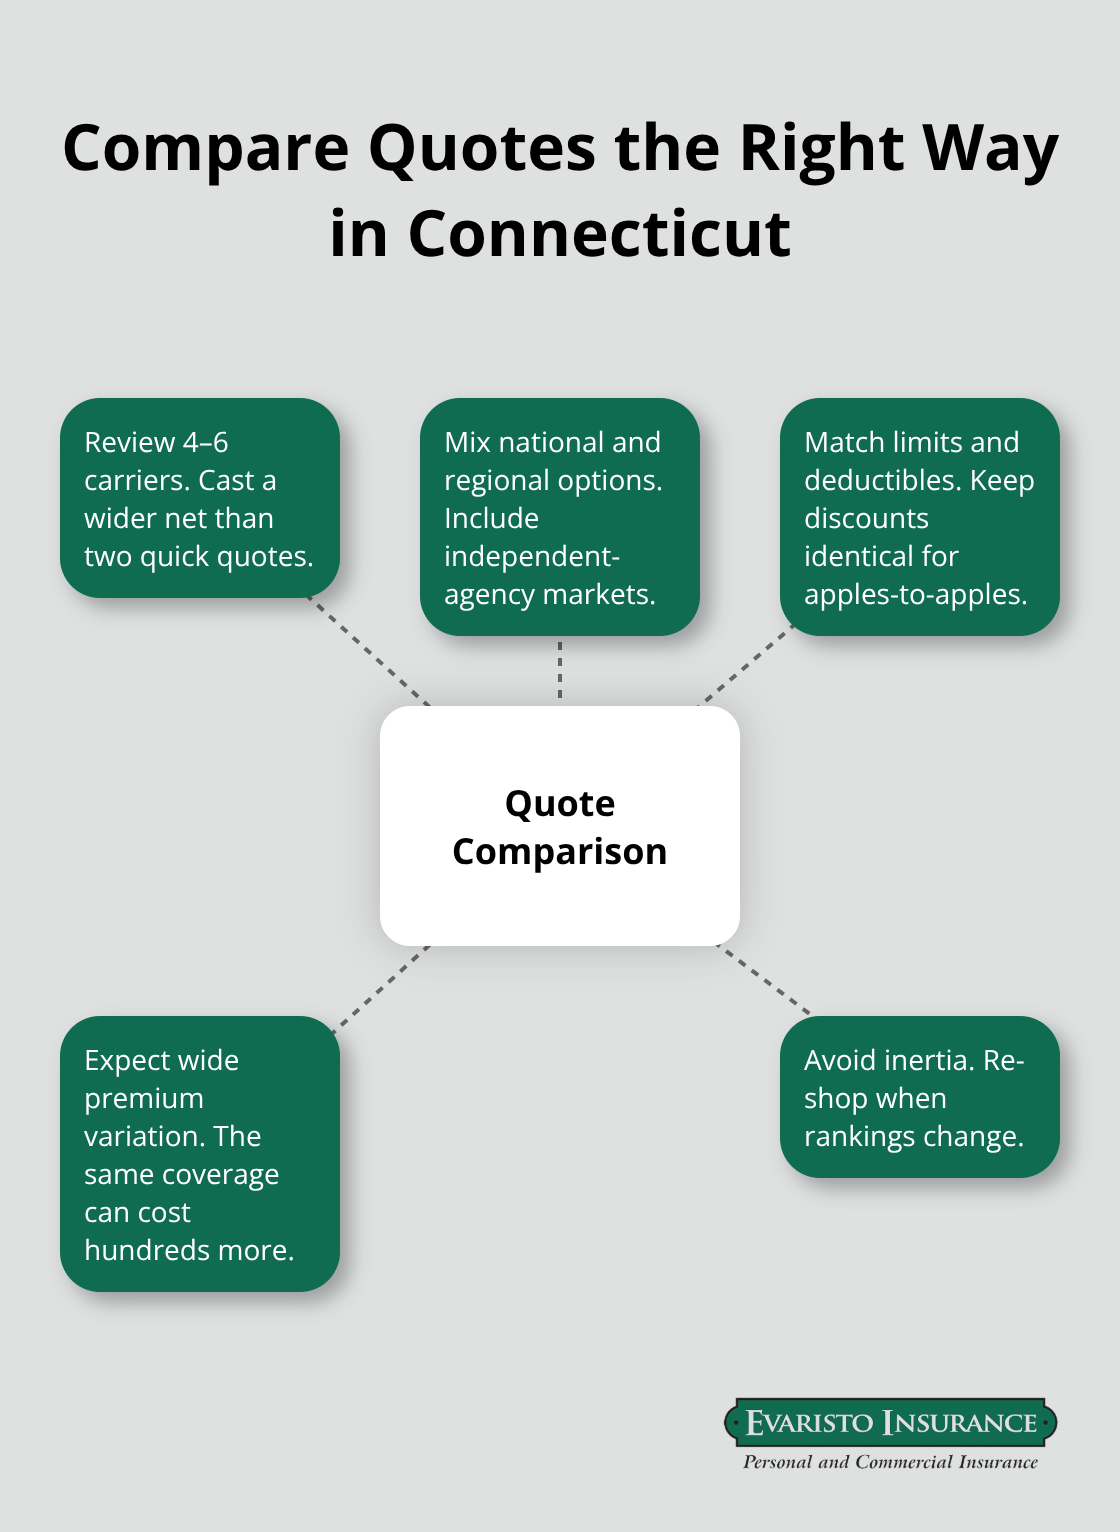
Most Connecticut homeowners stop after two quotes when they should review at least four to six options. Start with major national carriers, then add regional players and independent agency options to your comparison. Record the exact coverage limits, deductibles, and discounts each quote includes so you compare apples to apples. Many homeowners discover that their current insurer’s quote ranks third or fourth when they finally shop around, yet they stay put out of inertia.
Work with a Local Independent Agent
Local independent agents in Connecticut operate differently than captive agents who represent single insurers. An independent agent accesses multiple carriers simultaneously and pulls quotes that match your specific situation-your home’s age, location, construction type, and claims history all factor into pricing. Agents compare top carriers to find competitive rates you won’t discover shopping alone online. They also catch discounts you might miss: a renovation you completed last year, a security system you installed, or an affinity group membership that qualifies you for savings. Beyond the initial quote, independent agents handle renewals proactively, reviewing your coverage each year to confirm discounts still apply and that your protection keeps pace with your home’s value. When claims happen, local agents advocate on your behalf with the carrier rather than leaving you to navigate the process alone.
Schedule Annual Coverage Reviews
The annual review step matters more than most homeowners realize-your coverage needs shift as you age, improve your home, or purchase valuable items. Carriers also adjust rates yearly based on claims data and market conditions, meaning your renewal quote might differ significantly from last year’s premium. Schedule a review conversation before your renewal date arrives, not after the bill shows up. This timing gives you options: switch carriers if rates have climbed, adjust coverage if your needs have changed, or lock in discounts before they disappear at renewal.
Final Thoughts
Home insurance discounts revealed throughout this guide represent real money in your pocket, but only if you act on them. Start by gathering your current policy documents, a list of safety features you’ve installed, and your claims history from the past five years. Contact your current insurer and ask specifically which discounts apply to your policy right now, then request written confirmation that these discounts appear on your renewal statement.
Next, obtain quotes from at least four other carriers in Connecticut and record coverage limits, deductibles, and discounts side by side so you compare identical protection across different companies. Regional variations matter significantly in Connecticut-a Fairfield County home faces different rates than one in Hartford County due to coastal exposure and local fire protection differences. This comparison work takes time, but the savings often exceed $500 annually.
A local independent agent can handle this comparison work for you while accessing multiple carriers simultaneously rather than shopping alone online. Evaristo Insurance compares top carriers to find competitive rates and catch discounts you might miss, then advocates on your behalf during claims and renewals. Schedule your annual review before renewal dates arrive so you maintain control over your coverage and pricing rather than accepting whatever quote shows up in the mail.
Disclaimer: This blog post is for general informational purposes only and does not represent actual coverage, policy terms, or legal requirements. Insurance details vary by individual and jurisdiction. Please consult a licensed insurance professional for advice specific to your situation.

