
New Driver Auto Insurance: Tips for Navigating Your First Policy
Getting your first auto insurance policy can feel overwhelming with all the coverage options and pricing factors to consider. At Evaristo Insurance, we know that new drivers in Connecticut need straightforward guidance to make confident decisions.
This guide walks you through the coverage types you’ll encounter, what affects your rates, and how to find a policy that actually fits your situation and budget.
Understanding Auto Insurance Coverage Types
Connecticut requires you to carry a minimum of $25,000 per person/$50,000 per accident for bodily injury and $25,000 for property damage liability coverage. This is the bare legal minimum, but it’s dangerously low. A single accident involving another vehicle or property can easily exceed these limits, leaving you personally responsible for the difference. Most new drivers should try for at least 100/300/100 coverage, which costs only slightly more but provides substantially better protection.
Liability Coverage Protects Your Assets
Liability coverage pays for injuries and damage you cause to others, not your own vehicle, so it protects your personal assets if you’re found at fault. This protection matters because medical bills and property damage claims can reach tens of thousands of dollars. Connecticut law mandates this coverage, and your lender will require it if you finance your vehicle. The difference between minimum coverage and adequate coverage often amounts to just a few dollars per month, yet it shields you from catastrophic financial exposure.
Collision and Comprehensive Protection for Your Vehicle
Collision coverage pays to repair or replace your car if you hit another vehicle, object, or roll over. Comprehensive coverage handles theft, weather damage, vandalism, and animal strikes. If you finance or lease your car, your lender will require both. If you own the vehicle outright, the decision depends on its value and your financial cushion.
Insurance Institute for Highway Safety data shows that drivers under 25 are involved in crashes at roughly three times the rate of older drivers, making collision coverage particularly valuable for new drivers. The deductible you choose directly impacts your premium. A $1,000 deductible costs less than a $500 deductible, but you’ll pay more out of pocket when you file a claim. New drivers with limited savings should lean toward lower deductibles to avoid financial strain after an accident.
Additional Coverage That Protects You
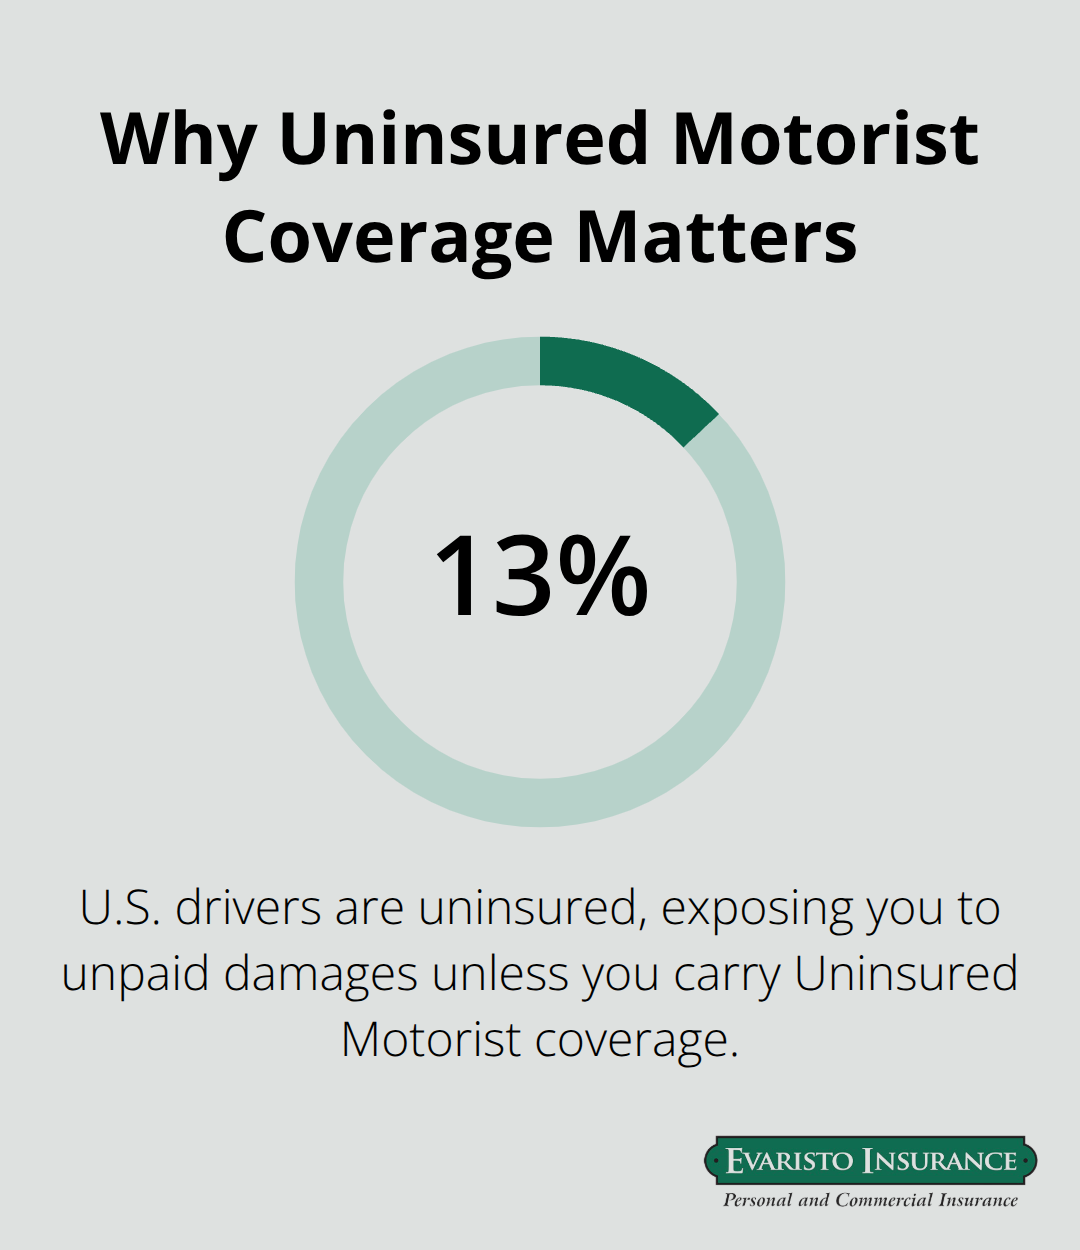
Uninsured motorist coverage protects you if someone without insurance causes an accident. Connecticut law doesn’t require it, but roughly 13 percent of drivers nationwide are uninsured, making it a smart addition. Medical payments coverage pays your medical bills after an accident, regardless of who’s at fault, and it covers passengers too (this coverage is inexpensive, typically adding $10 to $25 monthly, and it eliminates coordination hassles with health insurance).
Connecticut new drivers should strongly consider both protections because the financial risk of an uninsured driver hitting you far outweighs the small premium increase. Once you understand what coverage types exist and why they matter, the next step involves looking at the specific factors that insurers use to calculate your individual rate.
Factors That Affect Your Insurance Rates
Age Is Your Biggest Rate Factor
Your age as a new driver is the single biggest factor determining what you pay for auto insurance, and there’s no way around it. Insurance companies view drivers under 25 as statistically riskier, and the data backs this up-the National Highway Traffic Safety Administration reports that drivers aged 16 to 19 have crash rates of 4.8 fatal crashes per 100 million travel miles, compared to 3.3 for drivers aged 20 to 24. You’ll see substantially lower quotes once you turn 25, even if nothing else about your driving changes. Until then, focus on the factors within your control.
Your Driving Record and Vehicle Choice Impact Premiums
Your driving record matters immediately. A single at-fault accident or traffic violation can increase your premium by 20 to 40 percent for three to five years, so defensive driving isn’t just safety advice-it’s financial protection. The vehicle you drive also significantly impacts rates. Insurance companies charge more to insure sports cars, luxury vehicles, and models with expensive repair costs. A Honda Civic costs substantially less to insure than a Dodge Charger or BMW 3 Series. If you’re shopping for your first car, check insurance quotes before purchase to prevent sticker shock.
Location and Commute Patterns Shape Your Rate
Connecticut’s location-based rating system means your zip code affects your rate. Urban areas like Hartford and New Haven typically have higher premiums than rural towns due to increased accident frequency and theft rates. Your commute distance and driving patterns matter too-someone driving 50 miles daily on the highway faces different risk than someone driving 10 miles locally on back roads.
Discounts New Drivers Frequently Miss
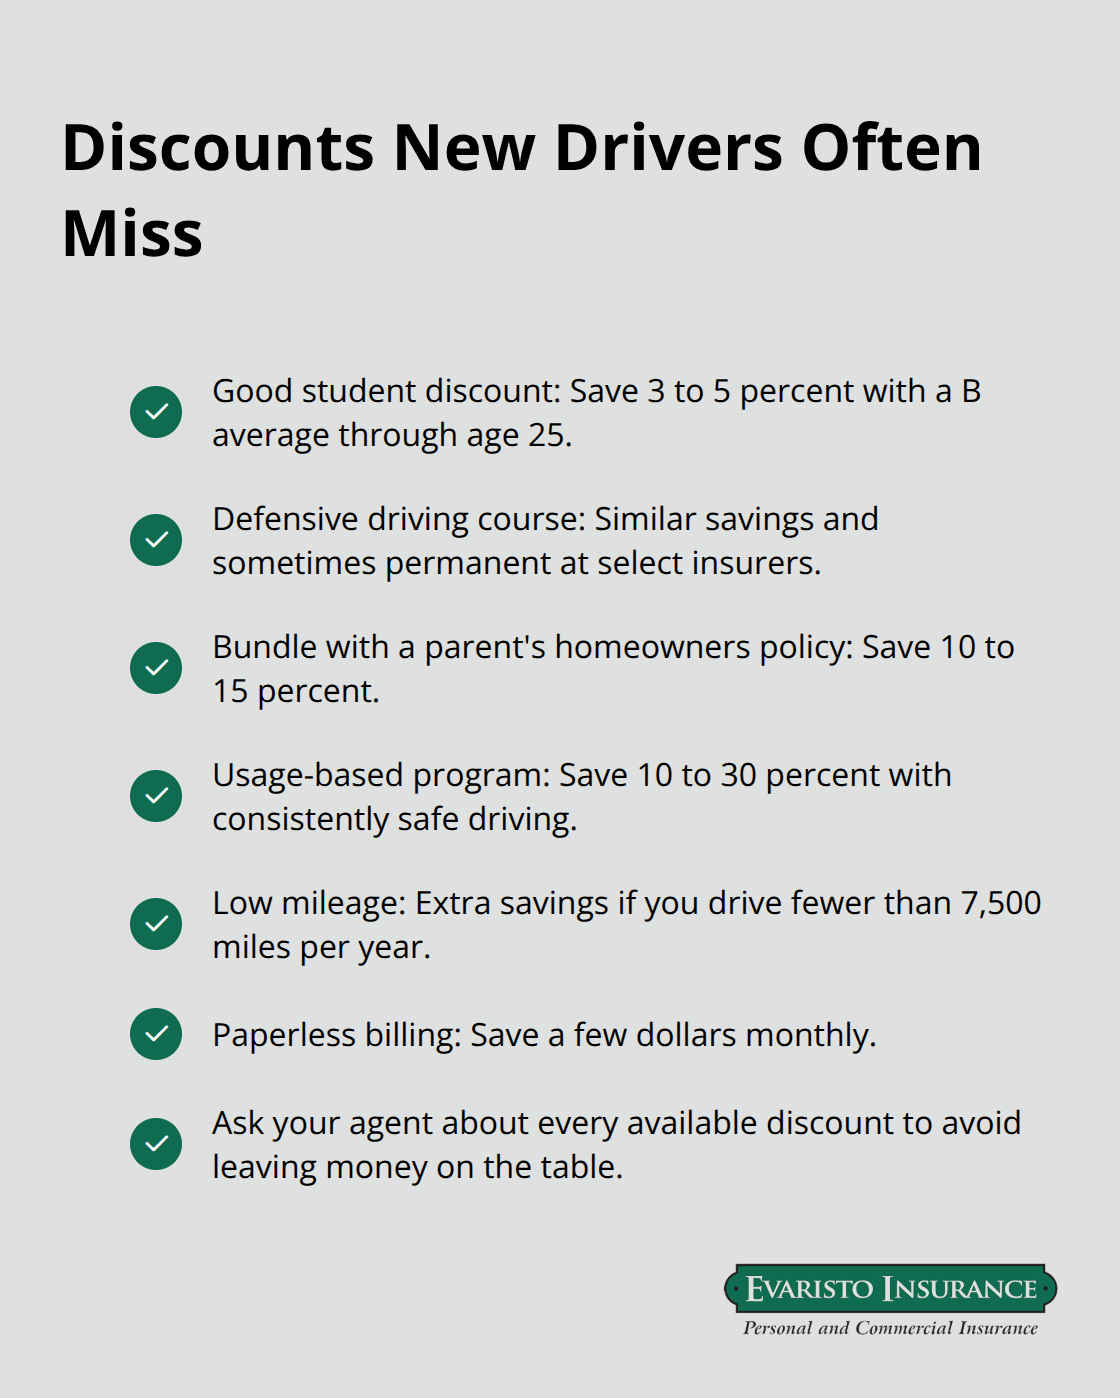
Insurance companies offer several discounts that new drivers frequently overlook. Good student discounts typically reduce your premium 3 to 5 percent if you maintain a B average or higher, and this applies through age 25 at most carriers. Defensive driving course discounts provide similar savings and may lower your rate permanently at some insurers. Bundling auto insurance with a parent’s homeowners policy often yields 10 to 15 percent in combined discounts.
Usage-based insurance programs that monitor your actual driving habits through a mobile app can save new drivers 10 to 30 percent if you demonstrate safe driving, though some programs penalize nighttime driving or frequent acceleration. Low mileage discounts apply if you drive fewer than 7,500 miles annually, and paperless billing discounts typically save a few dollars monthly. The key is asking your agent about every available discount rather than accepting the first quote-many new drivers leave money on the table simply because they don’t know discounts exist.
Understanding what drives your rates helps you make smarter choices about coverage and vehicle selection. The next step involves comparing actual policies and carriers to find coverage that matches your specific needs and budget.
How to Find the Right Policy for Your Situation
Compare Multiple Quotes to Avoid Overpaying
You must collect quotes from multiple carriers if you want competitive pricing. Many new drivers accept the first quote they receive, which costs them money. Insurance rates vary dramatically between carriers for identical coverage. You should obtain at least three quotes before deciding, and comparing quotes takes roughly 15 minutes per carrier if you have your vehicle information and driving history ready.
When you request quotes, use identical coverage levels across all carriers so you’re comparing apples to apples. Specify the same liability limits, deductible amounts, and additional coverages for each quote. Many online quote tools show estimates, but actual quotes from agents often differ because underwriters consider details that automated systems miss.
Match Your Coverage to Your Vehicle and Financial Situation
Your vehicle’s value and your financial situation should determine whether collision and comprehensive coverage makes financial sense. If you drive a 2015 Honda Civic worth roughly $12,000, a $500 deductible on collision coverage might cost $45 monthly, while a $1,000 deductible costs $32 monthly. Over three years with no claims, the $1,000 deductible saves you $468, which only makes sense if you have $1,000 available after an accident.
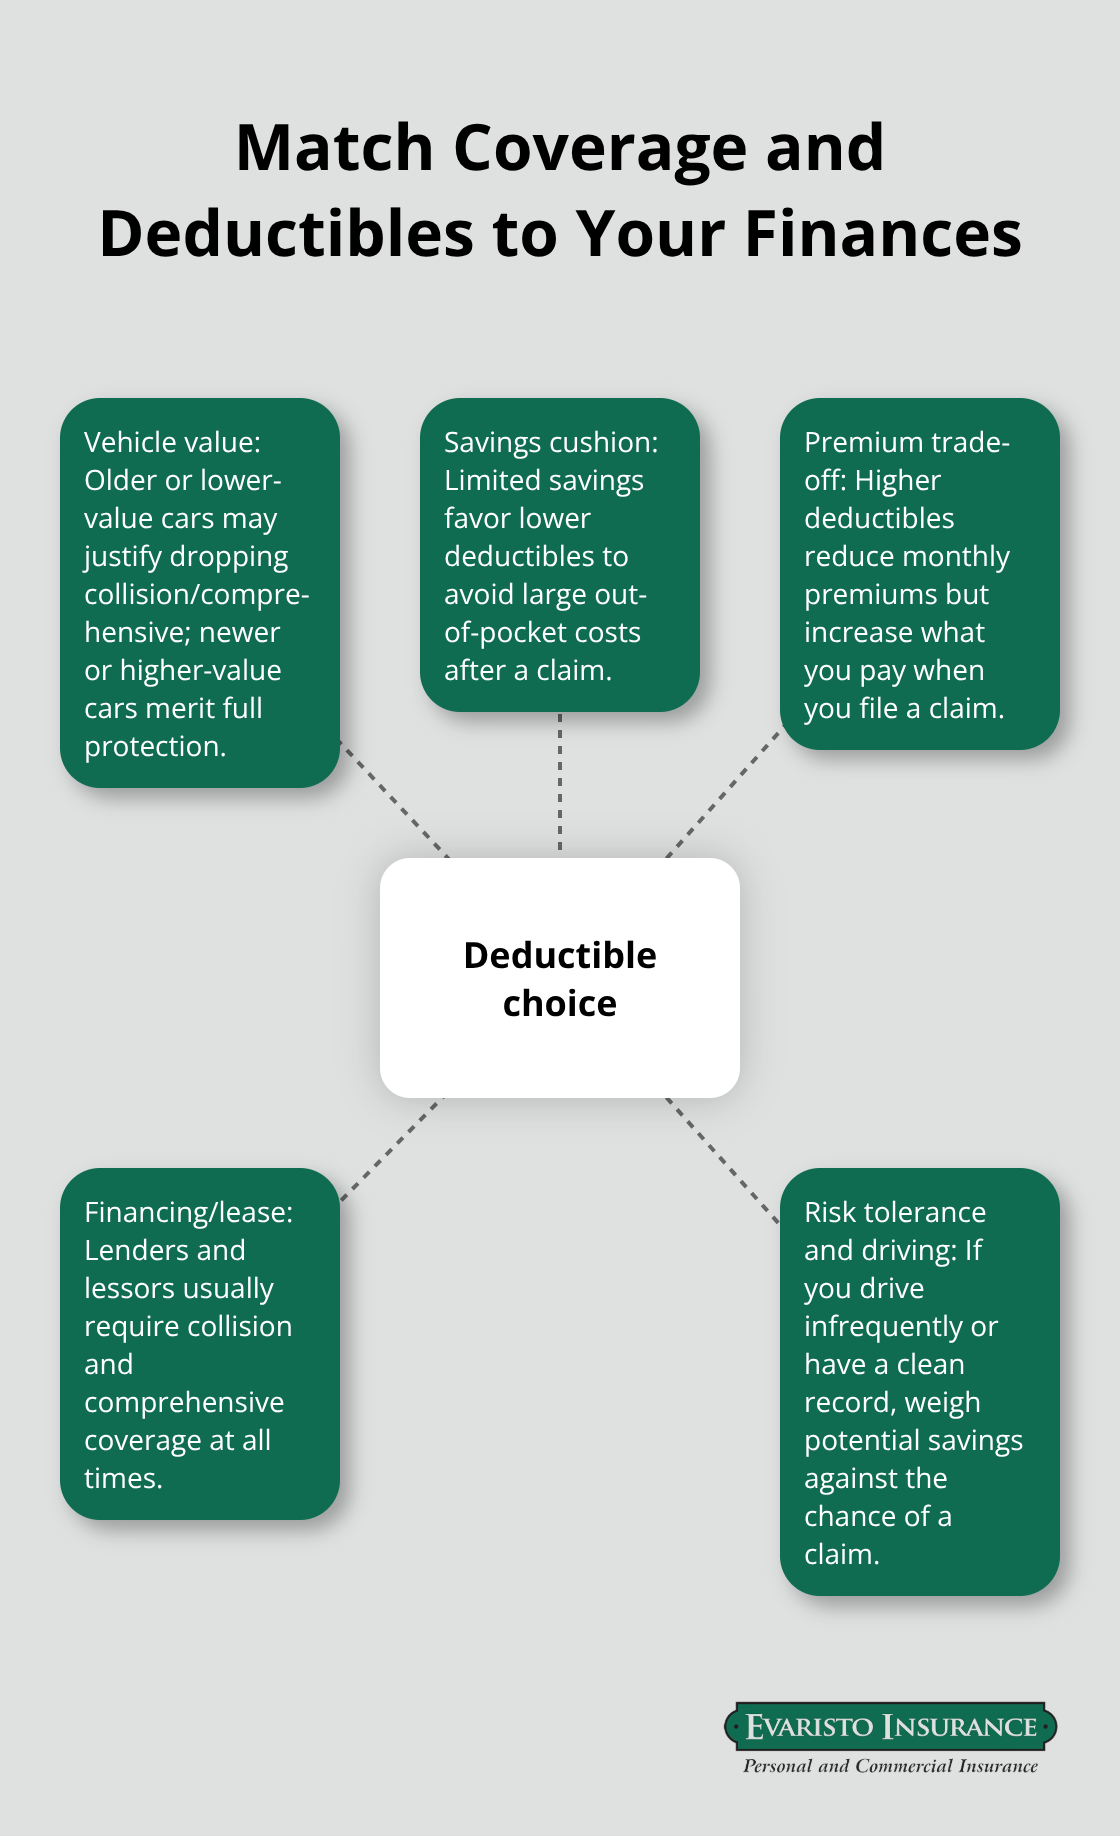
New drivers with minimal emergency savings should choose lower deductibles to avoid financial hardship following a collision, even if premiums cost more monthly. Conversely, if you own a vehicle outright and have six months of expenses saved, increasing deductibles to $1,000 or $1,500 reduces premiums without creating genuine risk.
Review Policy Details Before You Commit
Read the actual coverage documents rather than relying on summaries before finalizing any policy. Exclusions matter enormously. Some policies exclude coverage for rideshare driving if you use your vehicle for Uber or DoorDash, while others cover it with an endorsement. Rental car reimbursement limits vary, and some policies cap it at $30 daily while others allow $50. These details don’t appear in rate quotes but significantly affect what you’re actually protected for when you need coverage.
Final Thoughts
Getting your first new driver auto insurance policy doesn’t require perfection, just informed decisions. The coverage types you choose should reflect your vehicle’s value and your financial situation, not what sounds impressive. Your rates will be higher than older drivers face, but that’s temporary-focus on the factors within your control like maintaining a clean driving record and comparing quotes from multiple carriers before committing.
Gather your vehicle information and driving history, then request quotes from at least three different insurers using identical coverage levels. Review the actual policy documents, not just the summaries, to understand what’s covered and what’s excluded. Pay special attention to how each policy handles rideshare driving, rental car reimbursement, and uninsured motorist protection, since these details matter when you actually need coverage.
Connecticut’s insurance landscape offers plenty of options, but navigating it alone wastes time and money. An experienced local agent understands Connecticut’s specific requirements, knows which carriers offer the best rates for new driver auto insurance, and can explain coverage options in plain language. Contact Evaristo Insurance to speak with a local agent who will compare multiple top carriers and find coverage that actually fits your needs and budget.
Disclaimer: This blog post is for general informational purposes only and does not represent actual coverage, policy terms, or legal requirements. Insurance details vary by individual and jurisdiction. Please consult a licensed insurance professional for advice specific to your situation.

